Tag: houses

  • Prefab homes: A resolution for housing disaster?

    Prefab houses: A resolution for housing catastrophe? | Australian Broker Information

    Information

    Prefab residences: A answer for housing disaster?

    Prefab houses drawing new want

    Prefab homes: A solution for housing crisis?

    Prefab and modular housing have been touted as potential cures to Australia’s housing catastrophe.

    Prefabrication consists of the off-web web page growth of components or full constructions, that are then transported to the constructing web web site.

    This system, thought to be trendy methods of design or industrialised creating, is gaining authorities curiosity, in accordance to the Residence Council.

    Federal authorities initiatives and help

    In March, establishing ministers nationwide agreed to lower purple tape to extend prefabricated and modular constructing.

    “We want to tug nearly each lever to assist use revolutionary producing to steering the rollout of those residences,” stated Ed Husic, minister for market and science.

    The Queensland authorities’s new funds dedicated funding for as much as 600 new modular houses.

    “We’re utilising our public builder QBuild and Queensland corporations to produce a whole lot further modular households,” reported QLD Housing Minister Meaghan Scanlon.

    Point out-distinct prefab housing tasks

    Western Australia is piloting a $1 million job making use of prefabricated very small properties to extend social housing.

    “Our authorities is utilising a amount of possibility building approaches to ship extra social housing throughout the purpose out,” WA Housing Minister John Carey acknowledged.

    Equally, New South Wales and Victoria are investing in modular housing trials and tasks as part of broader housing initiatives.

    Qualified insights and points

    Professor Mathew Aitchison, CEO of Constructing 4. CRC, pressured the historic context and difficulties of modular housing.

    “Australia has been endeavor prefab on and off as a result of reality the mid-Nineteenth century,” Aitchison acknowledged.

    Having stated that, he cautioned versus viewing it as a overcome-all for the housing disaster.

    “It is one more useful resource within the software program bag… It can take pleasure in a place, and governments are proper to research it. But it’s by no signifies a ‘get out of jail free’ card.

    “We want to begin out capturing way more details to acknowledge this ingredient of {the marketplace} a lot better,” he talked about.

    The Building 4. CRC not too way back hosted an innovation showcase showcasing chopping-edge enhancements, underscoring the significance of continued funding resolution and growth.

    Sector views

    Home Council CEO Mike Zorbas (pictured over) advocates for larger inclusion of prefab and modular housing within the housing mix.

    “We might want to put money into innovation and arrange secure want pipelines to scale up industrialised constructing,” Zorbas defined.

    The House Council predominant acknowledged the challenges however identified the possible advantages of huge-scale creation.

    Get the most popular and freshest mortgage mortgage information despatched appropriate into your inbox. Subscribe now to our FREE day-after-day publication.

    Connected Tales

    Continue to maintain up with the most popular information and events

    Join our mailing document, it’s completely free!

  • Homebuilders are accomplished until eventually home loan premiums tumble Why design on one-loved ones houses is on maintain

    Tuesday’s housing commences report clearly displays that homebuilders are heading to be accomplished with single-household constructing until mortgage charges fall. Housing completion data is nonetheless having difficulties to get some traction, however within the coming months, builders actually must be able to get extra housing completions completed while housing permits and begins off for solitary-relatives properties are in drop. If it wasn’t for secure rental want boosting multifamily design this calendar yr — 18% yr thus far —this information line would have appeared a lot worse.

    From Census: 

    Privately‐owned housing begins in July have been at a seasonally adjusted annual worth of 1,446,000. This is 9.6 p.c (±8.6 p.c) beneath the revised June estimate of 1,599,000 and is 8.1 p.c (±11.9 p.c)* beneath the July 2021 cost of 1,573,000. Single‐household housing begins in July had been at a price of 916,000 this is 10.1 p.c (±10.8 p.c)* beneath the revised June determine of 1,019,000. The July price for models in properties with 5 fashions or further was 514,000.

    Of course, housing begins off as of late are not collapsing in the way in which they did from the height of 2005 as a result of we’ve not had a income credit score rating increase in newest years as we did from 2002-2005, which inflated new property income in the direction of 1.4 million.

    Presently, we are in a a lot completely different housing recession than what we had from 2005-2011. The credit score historical past cycle seems considerably varied now than the develop-up from 2002-2005.

    Why do I name it a housing recession? A financial downturn is when full exercise falls to a situation by which manufacturing reverses and work alternatives are misplaced. For now, the homebuilders will proceed to maintain labor just because they should have to finish the residences they’ve within the pipeline. However, as new home product sales have fallen, the long run development in development is carried out until the builders actually really feel snug constructing far more one-family begins.

    As we are able to see underneath, solitary-loved ones commences are falling far more considerably than whole housing begins off, which is even now changing into boosted by rental demand from prospects.

    Full motion within the current property product gross sales market is falling, which suggests significantly much less price switch in that sector. Personal loan originations are falling amid considerably much less need from refinancing and buy loans, which signifies jobs are shed within the home loan market. That half differs from the brand new residence product sales selector, which drives housing design, development work alternatives, and large-ticket buys for all these new houses. The new lower in copper costs is actually telling even with a contemporary rebound in prices, gadgets are slowing down on the housing improvement facet.

    In March I wrote that the brand new residence gross sales sector was in danger as soon as the 10-year generate broke over 1.94%. At current, the 10-year generate is at 2.81%, and mortgage fees beforehand talked about 5% have impacted this sector additional significantly than the present home product sales present market.

    Lately I talked about how low prices should go to get housing again in line. In the previous, builders benefitted when mortgage loan charges fell in the direction of 4% and beneath. Although we’ve had greater than a 1% + switch in charges, we are nonetheless round 5%. We can see that the builder’s self-confidence information has collapsed just lately, heading beneath 50 for the very first time in a despite the fact that, with the ultimate print staying at 49.

    NAHB:

    I elevated the fifth financial downturn pink flag tied to housing in June, understanding that the development quantity in design was completed for this cycle proper up until home loan charges fell once more. In 2018, when mortgage charges rose to five%, the builders paused constructing for 30 months they’d been aware of provide within the new dwelling product sales sector. We have 9.3 months of present however of that choice, 6.22 months of provide is underneath constructing and 2.24 months of provide has not even been started however

    For assured, it is a a lot distinctive housing cycle just because housing completion information has been extended at some stage in the COVID-19 restoration. Now that need is slipping, the builders will take into account their time ending these properties to make sure they’ve purchasers utterly able to switch in when the houses are completed.

    From Census: Housing Completions Privately‐owned housing completions in July have been at a seasonally modified yearly charge of 1,424,000. This is 1.1 % (±14.8 p.c)* above the revised June estimate of 1,409,000 and three.5 per cent (±15.5 %)* earlier talked about the July 2021 worth of 1,376,000. Single‐household housing completions in July have been being at a cost of 1,009,000 this is .8 p.c (±12.2 p.c)* beneath the revised June cost of 1,017,000. The July price for fashions in constructions with 5 fashions or far more was 412,000.

    During the housing bubble years, housing begins, permits, completions, credit score historical past, and charges moved collectively. That is not the case on this article, as housing completions nonetheless lag, while points are enhancing on the supply entrance.

    Above time, housing permits will tumble extra considerably so long as home loan charges preserve substantial. When the homebuilders’ confidence turns, housing permits ought to advertise development. We are not there but, however the builder’s confidence information will give us the first clues when issues are enhancing upon.

    From Census: Building Permits Privately‐owned housing fashions accredited by establishing permits in July have been being at a seasonally adjusted annual quantity of 1,674,000. This is 1.3 p.c beneath the revised June stage of 1,696,000, however is 1.1 per cent increased than the July 2021 quantity of 1,655,000. Single‐household authorizations in July have been at a charge of 928,000 this is 4.3 % down beneath the revised June determine of 970,000. Authorizations of fashions in properties with 5 fashions or extra had been at a quantity of 693,000 in July.

    The housing improvement particulars seems applicable to me the downtrend in exercise in permits and begins ought to actually even now be with us for a while. The homebuilders by no means create for charity — they’re listed right here to generate income. Also, they are experiencing additional aggressive inventory because of the reality the quantity of present properties is rising, and people are cheaper. So, they may get their time to assemble the houses by now beneath design and folks households they haven’t began on however.

    When mortgage costs drop, the narrative can modify, however we are not there however. Stable rental demand is attempting to maintain the multifamily development going, however the weak spot in one-household commences is beneath to stay hope solitary-loved ones commences to have their preliminary drop as a result of 2011.

    

  • Prices are dropping and houses are starting up to sit on the industry

    The mortgage payment pendulum swings however but once more

    By Didier Malagies
    •
    18 Apr, 2024

    Expect 2024 to be mildly superior than 2023 with property finance mortgage prices slipping in the subsequent 50 % of the yr, housing gurus opined in their forecasts at the cease of the calendar yr. Cuts to the Federal money payment (and subsequently to mortgage prices) are imminent, merchants enthused instantly after December’s convention of the Federal Open Marketplace Committee through which committee customers predicted 3 quantity cuts in 2024. Some gurus forecasted as quite a few as 6 worth cuts in the calendar yr primarily based on this information. Rate cuts are however coming, simply not in March , merchants and present market authorities reasoned much more not way back as the financial system continued to run scorching. And now on the heels of research of extra sturdy than predicted employment progress and stickier than predicted inflation , the market’s shift from optimism to pessimism greater than payment cuts is complete. Some even depend on quantity hikes proper earlier than quantity cuts. The pessimism is seen in property finance mortgage charges. Freddie Mac‘s weekly Key Property finance mortgage Market Study is climbing once more towards 7%. HousingWire’s Mortgage mortgage Charge Centre , which relies upon on information from Polly, is already above 7.2%. Premiums have been as decreased as 6.91% for Polly and 6.64% for Freddie as these days as February. On Tuesday, they attained 7.50% on Mortgage News Everyday, the next for this 12 months. Home finance mortgage charges preserve main electrical energy in the housing sector most significantly, important prices exacerbate the current affordability catastrophe by walloping the purchasing for electrical energy of would-be customers and discouraging some would-be sellers – folks with minimal, fastened-fee house loans – from itemizing their houses, a drain on accessible inventories. All this leaves housing industry consultants at the time as soon as extra battling for his or her share of shrinking pies – as we have now noticed with not too long ago launched mortgage mortgage particulars and RealTrends Verified’s brokerage data , as successfully as additional dives on the brokerage landscapes in Jacksonville and San Diego . It is unsurprising, then, that critical property shares have skilled contemplating that the FOMC’s March assembly and the current process and inflation experiences. That consists of the nation’s main homebuilders (DR Horton and Lennar), house finance mortgage originators (United Wholesale Mortgage mortgage and Rocket Property finance mortgage), brokerages (Wherever and Compass) and family analysis portals (Zillow and CoStar, which owns Houses.com). There are different dynamics at play for a few of these firms, nonetheless. The brokerages are additionally contending with the rule variations bundled in a proposed settlement by the Countrywide Association of Realtors some merchants additionally imagine people rule changes benefit CoStar at the expense of Zillow . UWM, in the meantime, is contending with a scathing investigative report by a hedge-fund-affiliated information agency whose hedge fund shorted UWM and went intensive on Rocket it is usually coping with pending litigation . UWM denies the allegations in-built the report.  High house mortgage fees, fewer property finance mortgage packages and fewer house earnings are nonetheless not the solely outcomes housing specialists may see from a further extended significant-rate pure surroundings. There are additionally spillover penalties from different industries, particularly administrative center genuine property. Regional banking firms – which usually have been key residential house mortgage originators – went main on enterprise critical property loans as larger banking establishments scaled again on this spot in newest a long time. That improved their publicity to downtown enterprise workplace towers, which have witnessed an exodus of tenants and a bottoming out of appraised values simply as a report $2.2 trillion in industrial genuine property bank card debt comes owing above the subsequent a number of yrs. That ties up capital that might if not circulation to family mortgages and in some situations stresses banks like New York Community Financial establishment, dad or mum of Flagstar Bank — the Seventh-greatest monetary establishment originator of family house loans, Fifth-premier sub-servicer of mortgage mortgage monetary loans and the 2nd-premier mortgage mortgage warehouse lender in the nation. Homebuilders, too, sense the penalties of prolonged greater charges. Whilst homebuilder self-confidence is proceed to up considerably since closing slide, new housing begins off are slowing . The dim potential consumers for homebuyers have turned some consumers to the nascent build-to-rent sector , in essence a guess that giant fees are proper right here to hold for very lengthy sufficient that would-be potential consumers are now would-be renters.

  • Labour sets out golden rules to improve houses with gray belt improvement    – Property finance loan Technique

    Labour chief Keir Starmer has set out plans to make on “ugly gray belt land” to improve housebuilding, enhance infrastructure and enhance inexperienced areas.  

    He suggests the bash will launch areas for enhancement in the intervening time classed as eco-friendly belt land, ought to it return to govt quickly after the following normal election.  

    The transfer is a part of the opposition celebration’s plans to create 1.5 million houses above the up coming parliament, which it calls “a significant plank of Labour’s coverage programme”.  

    By distinction, Primary Minister Rishi Sunak final 12 months pledged to shield the inexperienced belt and goal development in cities and cities.  

    Having mentioned that, Starmer says a Labour governing administration will put in space 5 golden pointers for gray belt progress:  

    Brownfield first – throughout the environmentally pleasant belt, any brownfield land ought to be prioritised for improvement  

    Grey belt second – poor-top high quality and unpleasant components of the environmentally pleasant belt ought to actually be plainly prioritised over mom nature-wealthy, environmentally worthwhile land within the inexperienced belt  

    Economical houses – designs have to concentrate on at minimal 50% very inexpensive housing delivery when land is launched  

    Boost neighborhood companies and infrastructure – choices ought to strengthen public companies and neighborhood infrastructure, equivalent to much more instructional services, nursery websites and new well being centres  

    Boost genuine inexperienced areas – the event procedures out constructing on actual mom nature locations and includes packages to embody developments to present inexperienced areas, producing them accessible to the neighborhood, with new woodland, parks and taking part in fields  

    Starmer states: “Labour helps brownfield preliminary insurance coverage insurance policies. But we could have to be trustworthy we merely can not make the residences Britain wishes with out additionally releasing some land at current classed as inexperienced belt.  

    “We’ll prioritise unappealing, disused gray belt land, and set robust new conditions for releasing that land.   

    “Our golden insurance policies may even make sure any gray belt enchancment offers inexpensive houses, new infrastructure and improved inexperienced areas.  

    “We will get tough on the blockers to again once more difficult-performing aspirational Brits, produce the houses and native suppliers that communities have earned, all while defending receive to official inexperienced room.”  

    Very final 12 months the UK included 234,400 dwellings, unchanged in distinction to the previous 12 months, in accordance to Division for Levelling Up, Housing and Communities details in November.         

    This is beneath the 2019 Conservative manifesto purpose of including 300,000 houses a 12 months by the mid-2020s.      

    Shawbrook controlling director of development finance Terry Woodley claims: “Labour’s proposed concepts to want councils to make on the ‘gray belt’ and utilise brownfield web pages might be a stage within the best course.

    “The Uk is in pressing will want of strategies to handle the housing shortages, and creating brownfield websites might be a sensible piece of the puzzle.  

    “However, it isn’t the only reply, and it could actually seem with its issues.

    “Though our research shows that 77% of builders concur that locale is nevertheless crucial driver of house gross sales and brownfield internet pages allow for eye-catching metropolis residing choices, these web pages can usually pose a singular established of issues and will maybe not be as lovely to builders as compared to different choices.

    Woodley factors out: “While this might be a beneficial alter, any governing administration pondering of those methods ought to guarantee that they’re having a multi-pronged tactic which incorporates an overhaul of the getting ready system to sufficiently tackling housing issues if we’re to see actual improvement over the up coming 12 months and previous.” 

    Dwelling Builders Federation authorities chairman Stewart Baseley offers: “In the encounter of an acute housing catastrophe we assist strikes to ship forward way more acceptable land for enchancment.   

    “Many places of the eco-friendly belt aren’t lovely and beforehand developed web pages these sorts of as petrol stations or auto parks supply good possible for brand spanking new housing close to to transportation inbound hyperlinks and facilities.”  

  • Aussie houses slide brief of needs

    Aussie households fall small of needs | Australian Broker Information

    News

    Aussie houses tumble restricted of needs

    New PropTrack insights reveal housing mismatch

    Aussie homes fall short of needs

    Australia’s housing panorama faces a serious mismatch, with evolving resident requires and shrinking households shifting demand from prospects for various kinds of houses and highlighting a market place gap, in accordance to PropTrack.

    “The frequent Aussie family has adjusted noticeably across the earlier couple a few years,” acknowledged Anne Flaherty (pictured increased than), PropTrack economist.

    With an frequent family dimensions dropping from 4.6 in 1920 to only 2.5 in 2023, the change within the route of solitary-particular individual houses and pair-only households has develop to be pronounced.

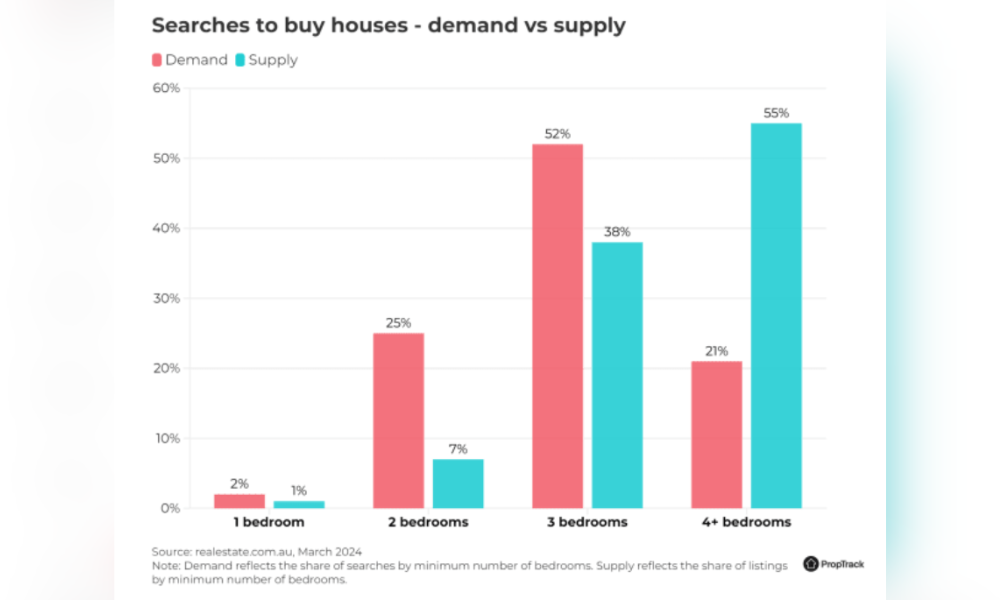
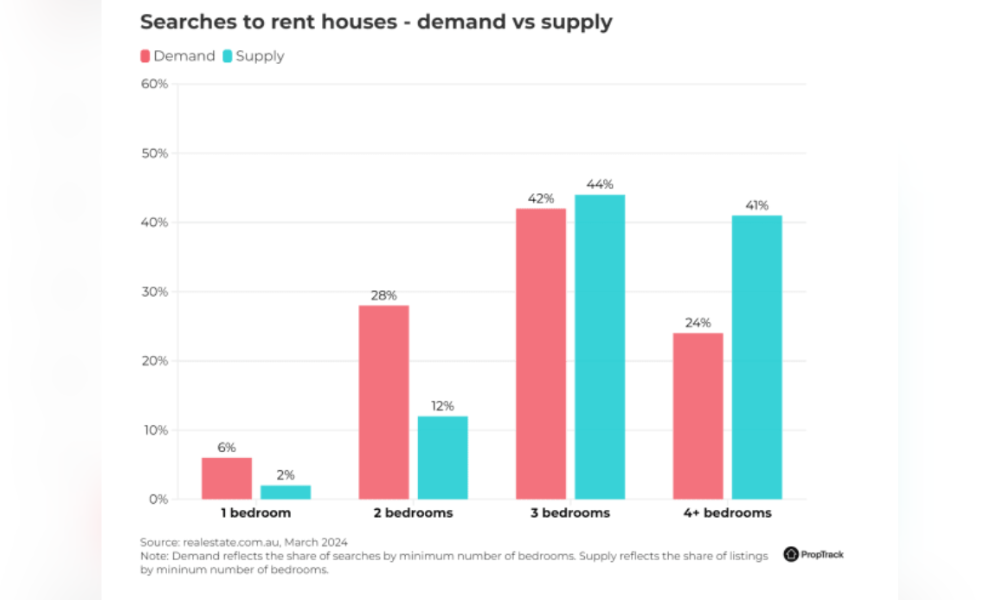
    “Among residence seekers seeking to purchase or lease residences, the shrinking family dimension has reweighted want absent from bigger properties to those with fewer bedrooms,” Flaherty acknowledged.

    Regardless of the prevalence of listings for houses with 4 or further bedrooms, the demand has shifted within the route of households with fewer bedrooms.

    Need and supply discrepancy

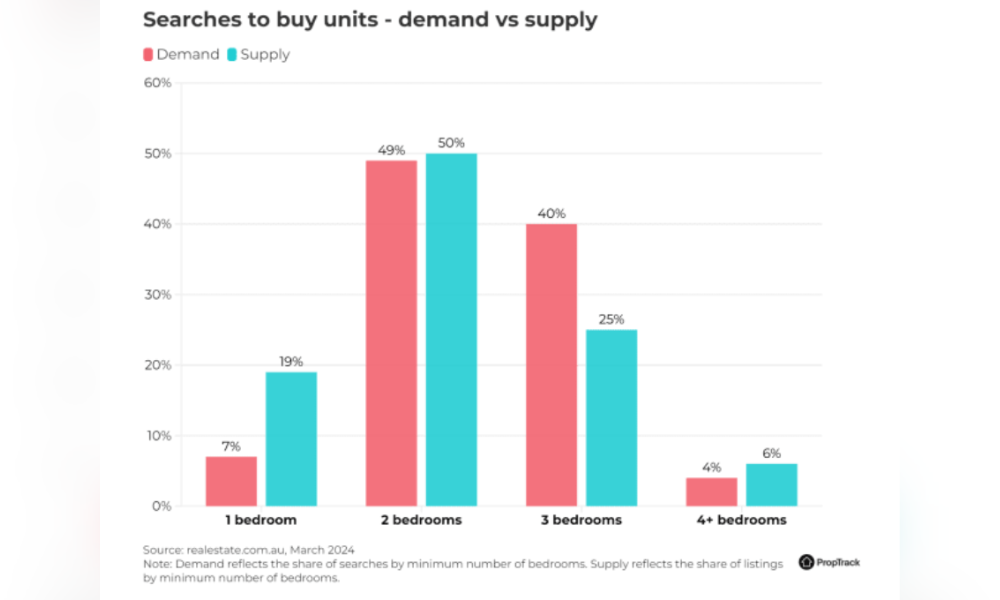
    The craze just isn’t solely minimal to properties. The unit sector has seen an reverse craze.

    “In the newest years, significantly post-COVID, there was growing demand from prospects for bigger fashions,” Flaherty acknowledged, stating the amplified want for three-bed room models amidst the rise of distant and hybrid doing work preparations.

    This want just isn’t staying met sufficiently, significantly in cities like Sydney, the place the supply of 3-bedroom models falls brief of the demand from prospects.

    Implications for pricing and progress

    The mismatch amongst supply and wish has a number of implications for the housing present market, along with the potential for a decrease within the worth high-quality for houses with many bedrooms and an improved prime quality for fashions with an extra bed room.

    “Understanding the mismatch involving demand from prospects and the current supply of housing has implications for potential development and pricing,” Flaherty defined, indicating a doable change in the direction of producing extra two-bed room properties and bigger models to fulfill the modifying necessities.

    Your ideas? Go over how altering housing needs are reshaping the sector.

    Continue to maintain up with the latest information and events

    Sign up for our mailing report, it’s free of cost!