Tag: homes

  • Number of Homes in Forebearance sees Record Decline

    U.S. mortgage holders publish document ranges of dwelling fairness: ICE

    By Didier Malagies

    15 May, 2024

    U.S. dwelling costs continued to climb in March as a persistent scarcity of properties on the market helped to buoy the housing market, in response to the Intercontinental Exchange (ICE) Home Price Index. And whereas potential homebuyers address the challenges of rising housing unaffordability, current owners are reaping the advantages of traditionally sturdy value positive aspects. Nationwide fairness on mortgaged properties soared to a document $16.9 trillion in the primary quarter of 2024, with $11 trillion obtainable for leverage whereas sustaining a 20% fairness cushion — additionally an all-time excessive. The ICE index confirmed that dwelling costs elevated by a seasonally adjusted 0.42% month over month in March, marking the third consecutive month of above-average value positive aspects, though this was a slight pullback from February’s 0.58% improve. On an annual foundation, dwelling value progress eased barely in March to five.6%, under the upwardly revised acquire of 6% in February. “The current development of rising rates of interest has dampened homebuyer demand and allowed the stock of properties on the market to enhance,” Andy Walden, ICE’s vice chairman of enterprise analysis technique, mentioned in an announcement.  “We’re nonetheless very a lot in a gap from a list perspective, however that deficit has fallen from 50% a yr in the past to 38% in March. Today, with 3.3 months of provide, stock remains to be traditionally low and indicative of a vendor’s market. This helps to maintain dwelling value progress resilient despite the fact that

  • Intense Competition Drives a Surge in Offers on Unseen HOmes


    Jordan Borchard posted in

    Housing in Housing News

    Intense Competition Drives a Surge in Offers on Unseen Homes

    National Mortgage News

    Source: National Mortgage News

    Written by: Paul Centopani

    With a low stock and coronavirus limiting accessibility, practically half of residence buyers made provides sight-unseen in June, in response to Redfin.

    In a survey performed final month, 45% of shoppers who bought a residence in the final 12 months put bids on homes with out bodily seeing them. It’s the very best share since Redfin began monitoring the information in 2015. Only 28% of consumers made these provides a 12 months in the past.

    This dovetails with rising swaths of potential consumers waiving inspection and appraisal contingencies to strengthen their provides. The pattern of sight-unseen bids will seemingly improve all through the approaching months, stated Redfin chief economist Daryl Fairweather.

    “I predict that by the tip of the 2020 homebuying season, nearly all of homebuyers could have made a sight-unseen provide,” Fairweather stated in a press launch. “The pandemic has modified the way in which many individuals view properties, and on prime of that, the market is very aggressive. If you aren’t utilizing this technique, one other purchaser who’s might beat you to the punch.”

    Social distancing measures made fewer listings obtainable for touring and made home hunters much less liable to see them in individual. Approximately 25% of potential homebuyers will restrict the open homes they go to and 18% stated they wouldn’t bodily go see listings in any respect.

    Distance partially drives this phenomenon, too. With distant work dominating the current and anticipated to be a new regular in the long run, a record-high share — 27% of homebuyers — appeared outdoors their present metro space, based mostly on Redfin’s migration report for the second quarter of 2020.

    Zillow’s newest Weekly Market Report corroborates the heightened market competitors. As demand outpaces provide, properties went from on the market to pending on the quickest charge since the true property web site began monitoring it in 2019. Overall, listings went off the market at a median tempo of 14 days for the week ending July 25 — 9 days sooner year-over-year. Median time on the market dipped as little as 4 days in Cincinnati, Columbus, Ohio, and Indianapolis among the many 50 largest metro areas.

    Newly pending gross sales grew 16.1% from this time a 12 months in the past whereas new listings dropped 12.2% yearly. Total stock stands 26.3% decrease year-over-year. This disparity induced itemizing costs to climb a mean of 0.3% week-to-week, including as much as an annual progress of 6% in residence costs.

  • Sales of Existing Homes Surge to a 14- Year High

      Sales of present properties surge to a 14-12 months excessive

    August gross sales rose to a seasonally adjusted annual charge of 6 million, NAR says

    September 22, 2020, 12:00 pm By Kathleen Howley

    Sales of present properties rose to a 14-12 months excessive of 6 million in August, the National Association of Realtors stated in a report on Tuesday.

    Combined gross sales of single-family homes, townhomes, condominiums and cooperatively owned residences rose 2.4% from July, in accordance to the report. Compared to a 12 months in the past, prior to the COVID-19 pandemic, final month’s gross sales had been 11% greater, NAR stated.

    “Home gross sales proceed to amaze, and there are loads of patrons within the pipeline prepared to enter the market,” stated Lawrence Yun, NAR’s chief economist. “Further good points in gross sales are probably for the rest of the 12 months, with mortgage charges hovering round 3% and with continued job restoration.”

    The median existing-home value final month was $310,600, up 11.4%, and costs rose in each area, NAR stated.

    The quantity of properties in the marketplace on the finish of August totaled 1.49 million, down 18.6% from the year-ago month, the report stated. Unsold stock measured as a “months provide” quantity that gauges how lengthy it might take to promote all of the properties if nothing else got here in the marketplace, was 3 months, NAR stated. That’s down from 3.1 months in July and in contrast with 4 months a 12 months in the past.

    The most cost-effective house financing prices on report are driving demand for properties, Yun stated. Mortgage charges have reached new lows 9 instances because the Federal Reserve started shopping for mortgage bonds in March to develop entry to credit score, in accordance to a weekly survey by Freddie Mac.

    The common U.S. charge for a 30-year fastened mortgage elevated one foundation level to 2.87% final week, the second-lowest on report, rising from the prior week’s all-time low, Freddie Mac stated on Thursday. The less-popular 15-year charge fell to a report low of 2.35% final week, the mortgage big stated.


  • No income /No asset on Primary/second homes

    No Doc Home Loans | No Income & No Asset Mortgages

    If you do not need to share your tax returns or doc your income, job, and property, don’t fret. You can nonetheless personal a house with a no-doc mortgage.

    What is a no-doc mortgage?

    The no doc mortgage is a sort of mortgage that enables debtors to get a mortgage with little or no documentation. This signifies that you need not doc your job, your income, or your property.

    What you do want is 2 issues:

    You have to have a down cost of 20% or extra

    You have to have a credit score rating of over 640

    Your charges will probably be greater than these on standard loans as a result of the lender has much less details about you and what they’re risking in the event that they approve your software. The rate of interest on a no doc mortgage is normally a degree or greater than on a conventional mortgage.

    Who would need a no-doc mortgage?

    If you reside within the north and are considering of transferring to Florida earlier than you get a job, this is likely to be one of the best mortgage for you!

    The no-doc mortgage is a good product people who’re in-between jobs, for the self-employed or 1099 staff with lower than 2 years employment, and people who might have a troublesome time exhibiting common income. This can be an incredible product for traders who might have a number of properties or different property and often reinvest.

    If you assume a no-doc mortgage is best for you, give us a name

    (727) 784-5555

    . We will crunch the numbers for you and decide what mortgage sort is likely to be finest for you.

    Or, join with us by finishing the shape under.

    Start Your Loan

    with DDA immediately

    Your native Mortgage Broker

    Mortgage Broker Largo

    See our Reviews

    Looking for extra particulars? Listen to our prolonged podcast! 

  • What types of homes qualify for a Reverse Mortgage loan-Condos, Villas, Townhomes, or co-ops?

    Fed holds charges continuous for the sixth straight time

    By Didier Malagies

    02 May maybe, 2024

    The Federal Reserve ’s Federal Open Marketplaces Committee (FOMC) taken care of its limited-term coverage curiosity worth common at a fluctuate of 5.25% to five.5% for a sixth consecutive convention on Wednesday. “The Committee doesn’t assume it is going to be best to decrease the give attention to selection until it has gained elevated confidence that inflation goes sustainably in the direction of 2%,“ the FOMC talked about in a assertion. “In addition, the Committee will carry on lowering its holdings of Treasury securities and company bank card debt and firm mortgage‑backed securities.“ For the length of their earlier meeting in March , policymakers indicated that they nonetheless envisioned a few want worth cuts in 2024. But with inflation remaining sticky and unemployment conserving beneath 4%, these anticipations are turning out to be fewer doable. Current financial knowledge hasn’t specified the Fed self-worth that inflation will proceed on to say no. Robust inflation particulars within the initially quarter, coupled with a sturdy labor market , have postponed expectations for the very first Fed stage slash. In April, Fed Chairman Jerome Powell, speaking on the Washington Forum , constructed it distinct that payment cuts had been being not imminent owing to the energy of the economic system. The monetary system has preserved shocking momentum regardless of the present diploma of short-phrase charges. With the unemployment stage underneath 4%, suppliers are steadily together with employees and severe wage growth is observable as inflation eases. While upward actions in inflation are noteworthy, appreciable improvement in the direction of the Fed’s 2% think about has been created. “It’s unlikely that the longer term protection stage switch shall be a hike,” Powell advised journalists on Wednesday all through the FOMC’s push assembly. “In buy to hike the premiums, we might need to see persuasive proof that our plan stance shouldn’t be adequately restrictive to hold inflation sustainably all the way down to 2% in extra of time. Which shouldn’t be what we’re observing on the minute.” While Powell emphasised the unlikelihood of future quantity hikes, he additionally remained obscure in regards to the Fed’s future curiosity worth trajectory. “We didn’t see improvement within the very first quarter. It seems that it’ll get for a longer interval for us to reach at that stage of assurance,” Powell talked about. “I have no idea how prolonged it can contemplate. … My personal forecast is that we’ll begin off to see improvement on inflation this 12 months. I have no idea that it is going to be a lot of to slice costs we should let the small print lead us on that.” In a new development, the Fed introduced an easing of its quantitative tightening coverage. Starting off in June, the charge-placing system will scale back the roll-off cost of its Treasury securities from $60 billion to $25 billion for every thirty day interval. This implies that when the Fed won’t get began advertising Treasurys in June, it can make it doable for much less of them to mature. It won’t change its roll-off payment for mortgage loan-backed securities (MBS), which can proceed to be at $35 billion for every month, in accordance to Xander Snyder, senior skilled true property economist at To begin with American. “The FOMC didn’t modify the continued passive roll-off of its MBS holdings however did remember that any prepayments additional than the persevering with $35 billion cap could be reinvested in Treasuries,” Mike Fratantoni, senior vice chairman and fundamental economist for the Property finance mortgage Bankers Affiliation, claimed in a assertion. “We count on house mortgage premiums to fall in a while this 12 months, however not as significantly or as quickly as we beforehand skilled predicted.” In addition, Powell reiterated the Fed’s motivation to carrying forward the Basel III endgame restrictions in a approach that’s dedicated to Basel and likewise equal to what the jurisdictions in different nations are engaging in. Since the March FOMC convention, Freddie Mac’s widespread 30-calendar yr mounted mortgage quantity has elevated from 6.74% to 7.17%. In advance of the next FOMC assembly on June 12, two extra inflation readings are envisioned. “While it’s a chance, I don’t really feel that we’ll see a nice deal enhance in mortgage mortgage prices pursuing this Fed convention, because of the truth the Fed has been eager to permit the data information at this part within the cycle,” Realtor.com fundamental economist Danielle Hale talked about in a assertion. “In order to see mortgage costs fall a lot extra drastically, the Fed might want to see a lot extra proof that inflation is slowing.”  For homebuyers and sellers, this implies that housing affordability will keep a finest consideration, maybe driving dwelling purchases in cheap markets, predominantly within the Midwest and South, in line with Hale.

  • The market place is shifting and prospective buyers are in a position to order homes without having 10 other buyers.

    Fed holds costs steady for the sixth straight time

    By Didier Malagies

    02 May, 2024

    The Federal Reserve ’s Federal Open Marketplaces Committee (FOMC) maintained its small-time interval protection curiosity worth common at a assortment of 5.25% to 5.5% for a sixth consecutive assembly on Wednesday. “The Committee doesn’t anticipate will probably be appropriate to decrease the think about choice till finally it has obtained bigger self-worth that inflation is shifting sustainably towards 2%,“ the FOMC reported in a assertion. “In addition, the Committee will proceed on reducing its holdings of Treasury securities and firm private debt and firm mortgage‑backed securities.“ For the length of their final convention in March , policymakers indicated that they proceed to envisioned three fascination cost cuts in 2024. But with inflation remaining sticky and unemployment being down beneath 4%, these expectations are changing into significantly much less attainable. Latest monetary data hasn’t specified the Fed self-worth that inflation will proceed on to lower. Sturdy inflation data in the very first quarter, coupled with a robust labor market , have postponed anticipations for the first Fed cost decrease. In April, Fed Chairman Jerome Powell, speaking on the Washington Discussion board , constructed it obvious that worth cuts weren’t imminent thanks to the toughness of the financial local weather. The monetary state has preserved beautiful momentum regardless of the present stage of quick-term charges. With the unemployment stage down beneath 4%, suppliers are steadily including personnel and precise wage growth is observable as inflation eases. While upward actions in inflation are noteworthy, important progress towards the Fed’s 2% objective has been produced. “It’s unlikely that the following coverage fee transfer might be a hike,” Powell instructed journalists on Wednesday through the FOMC’s push convention. “In purchase to hike the costs, we might need to see persuasive proof that our coverage stance is not adequately restrictive to ship inflation sustainably down to 2% round time. That’s not what we are seeing on the instantaneous.” Although Powell emphasised the unlikelihood of potential quantity hikes, he additionally remained imprecise concerning the Fed’s future need cost trajectory. “We didn’t see growth in the preliminary quarter. It appears that it’s going to get for a longer interval for us to entry that place of self-worth,” Powell defined. “I have no idea how extended it would take. … My explicit forecast is that we are going to start to see progress on inflation this 12 months. I don’t know that will probably be loads of to decrease costs we could have to permit the info information us on that.” In a new enhancement, the Fed introduced an easing of its quantitative tightening plan. Starting in June, the fee-environment system will lowered the roll-off cost of its Treasury securities from $60 billion to $25 billion for every month. This often implies that despite the fact that the Fed is not going to start promoting Treasurys in June, it would allow much less of them to skilled. It is not going to alter its roll-off quantity for house finance loan-backed securities (MBS), which is able to stay at $35 billion per thirty day interval, in accordance to Xander Snyder, senior skilled real property economist at (*10*) American. “The FOMC didn’t modify the continuing passive roll-off of its MBS holdings however did observe that any prepayments exterior of the persevering with $35 billion cap can be reinvested in Treasuries,” Mike Fratantoni, senior vice chairman and predominant economist for the House mortgage Bankers Affiliation, defined in a assertion. “We anticipate mortgage mortgage charges to fall later this yr, however not as significantly or as speedy as we beforehand skilled predicted.” In addition, Powell reiterated the Fed’s dedication to carrying forward the Basel III endgame guidelines in a method that is devoted to Basel and additionally comparable to what the jurisdictions in other nations are performing. Since the March FOMC convention, Freddie Mac’s widespread 30-calendar 12 months set house finance mortgage charge has amplified from 6.74% to 7.17%. Just earlier than the up coming FOMC assembly on June 12, two extra inflation readings are anticipated. “While it’s a likelihood, I actually do not think about that we’ll see a lot modify in home mortgage costs subsequent this Fed assembly, just because the Fed has been prepared to let the main points direct at this section in the cycle,” Real property agent.com chief economist Danielle Hale defined in a assertion. “In order to see home mortgage costs drop extra considerably, the Fed will want to see further proof that inflation is slowing.”  For homebuyers and sellers, this implies that housing affordability will proceed being a prime thought, possibly driving house purchases in cheap marketplaces, predominantly in the Midwest and South, in accordance to Hale.

  • A lot more homes sold at savings – PropTrack

    More homes sold at bargains – PropTrack | Australian Broker Information

    Information

    A lot more households provided at bargains – PropTrack

    Reductions emerge in regional marketplaces

    More homes sold at discounts – PropTrack

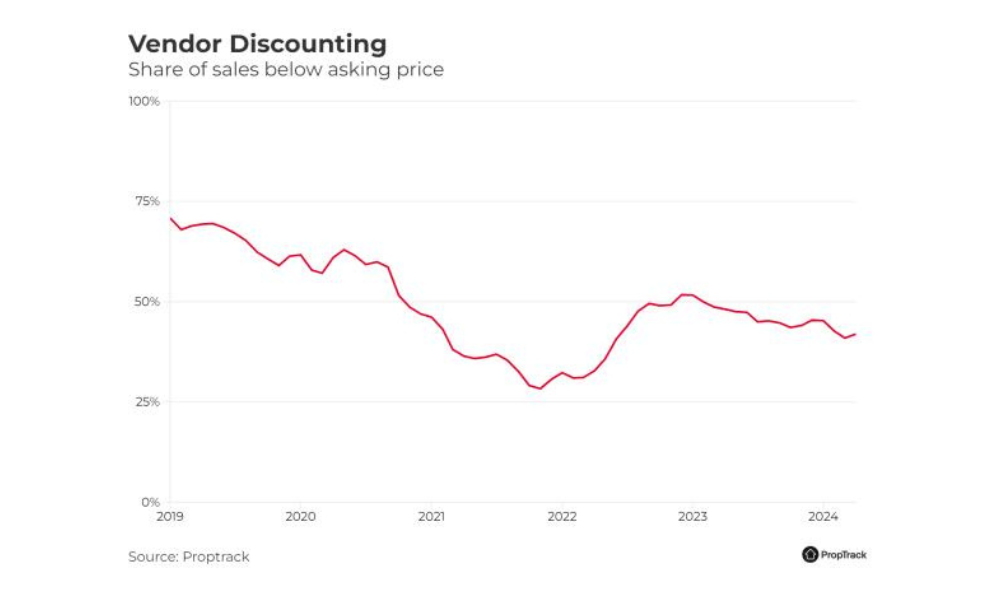
    House worth ranges are reaching new highs all through many areas and the amount of households purchased beneath asking price ticket is reducing, nevertheless fairly just a few locations are nevertheless coping with an maximize in residences staying marketed at a reduced, PropTrack defined.

    The PropTrack April Residence Selling worth Index verified a modest development in dwelling promoting costs by .23% in extra of the earlier month, representing a 6.6% enhance from April 2023, and marking 16 months of consecutive development.

    Regional variations in residence promoting costs

    Despite the nationwide improvement of rising dwelling promoting costs, some areas are witnessing a varied state of affairs.

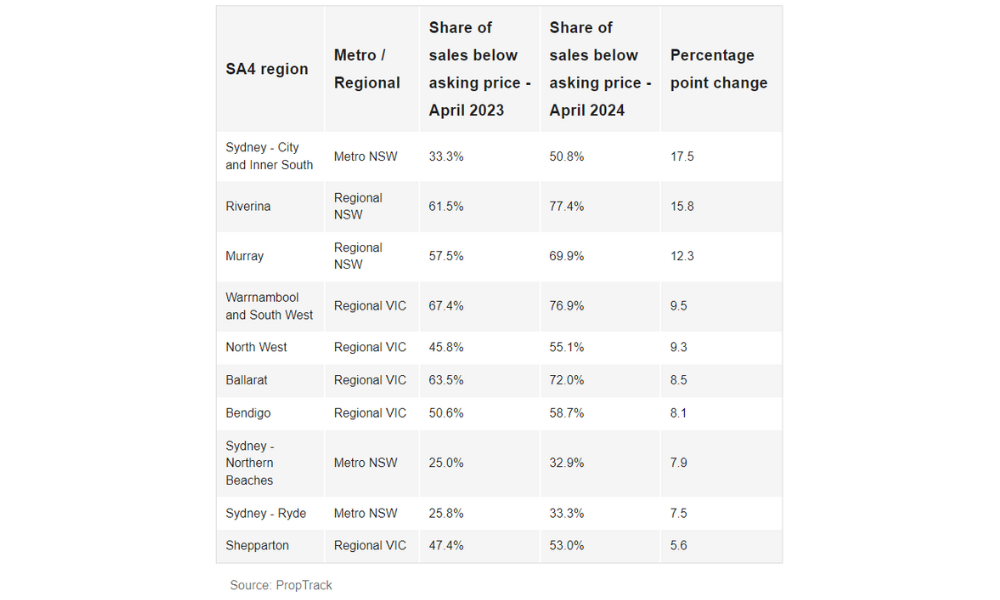
    Specifically, the Sydney – Metropolis and Internal South place noticed about 51% of homes purchased under inquiring worth, up from 33% the earlier yr. This 18-percentage-place elevate in vendor discounting is main and certified prospects amongst SA4 areas.

    Other components just like the Riverina and Murray places additionally seen noteworthy raises in properties marketed at a worth minimize.

    Implications for Purchasers in Regional Marketplaces

    The craze of enhanced vendor discounting is particularly pronounced in regional components of NSW and Victoria, wherever price ticket progress has been slower versus their capital metropolitan areas and different regional areas.

    “This maximize in vendor discounting and reduce than regular price progress demonstrates a slowdown in demand from prospects and potential declines in competitiveness in these areas, which is improbable info for people seeking to buy,” reported Megan Lieu (pictured increased than), monetary analyst at REA Team.

    With residence prices falling by .9% above the earlier calendar 12 months in regional Victoria and a additional modest rise of 4.3% in regional NSW, the sector issues are more and more beneficial for patrons.

    PropTrack’s outlook on home costs

    Even with these regional discrepancies, the usually demand for residences all through Australia is predicted to maintain on being sturdy, supported by potent populace progress and restricted rental sector problems.

    “Prices are more than likely to hold on rising because the supply of homes falls temporary of demand,” Lieu talked about.

    This sustained demand from prospects, coupled with a tightening rental business and rising self-confidence within the market, means that although some areas could probably give reductions, the broader business development leans towards elevated promoting costs.

    Are properties in your area advertising and marketing at a cheaper price? Sign up for the dialogue on the brand new PropTrack Residence Price tag Index.

    Continue to maintain up with the most recent info and actions

    Sign up for our mailing file, it is freed from cost!

  • 50 % of all homes at substantial hazard of reduce retirement dwelling benchmarks

    Close to 50 p.c of all U.S. homes are at danger of turning into not in a position to protect their pre-retirement regular of residing as soon as they attain retirement, even when they do the job until the age of 65, in line with the National Retirement Chance Index (NRRI) revealed this week by the Boston University Centre for Retirement Research (CRR).

    By incorporating new investigation outcomes and methodological advances into the small print, the newest model of the NRRI “can way more correctly consider the retirement preparedness of doing the job-age homes and assess the have an effect on of financial and coverage issues on retirement stability,” in line with the researchers.

    Even instantly after recalculating quite a few items of info underneath the NRRI’s latest pointers, the severity of the chance danger for households has not diminished when in distinction with earlier NRRI releases, the researchers mentioned. While the uncooked proportion of at-hazard homes declined considerably in contrast with info from 2010, the menace was most intense amongst the oldest cohort of pre-retirees in regards to the ages of 50 and 59.

    Some occasions impacted distinctive ranges of residence income indiscriminately, considerably the cash disaster and its pursuing Great Recession, the info defined.

    “The center and the best thirds noticed appreciable enhancement from 2010-2019 as a result of of to rebounding housing and equity expenses,” the small print claimed. “In distinction, households within the backside third noticed virtually no enhancement as they’re much much less potential to very personal a residence and participate in [defined contribution] plans, and have a number of economical belongings.”

    When considered by wealth crew, the extent of retirement preparedness indicated equal kinds. On the opposite hand, there was a apparent distinction within the main and base teams on this cohort.

    “The discrepancy in regards to the main and base prosperity groups, although, is considerably bigger sized than folks by earnings, reflecting the straightforward undeniable fact that prosperity inequality is further critical than revenue inequality,” the info reported.

    So, even quickly after recalculation based totally on up to date methodologies, the primary technique regarding retirement preparedness has managed to take care of correct. Critically, that applies even when along with a reverse mortgage within the situation.

    “[A]bout fifty p.c of in the present day’s homes won’t have satisfactory retirement earnings to maintain their pre-retirement frequent of residing, even when they work to age 65 and annuitize all their fiscal property, which incorporates the receipts from a reverse residence finance mortgage on their residences,” the NRRI reported. “The robustness of the ultimate outcomes confirms the retirement saving issue confronted by in the present day’s doing the job-age homes, and that we wish to repair our retirement process in order that employer plan safety is frequent.”


    Constant safety is the one means personnel will be capable to accumulate an appropriate quantity of sources to handle the conventional of dwelling they’ve developed accustomed to simply earlier than retiring, the NRRI concludes.

  • KnowledgeRetirement Extra seniors, concerned about economic downturn, move to provide properties: survey

    Approximately 1-in-8 members of the new child boomer technology have taken motion on the chance of an impending economic downturn by promoting their properties, aiming to lock in a elevated property profit whereas they however can. This is in accordance to a
    simply lately-produced survey of U.S. seniors aged 59 and extra mature performed by Retirement Dwelling.

    Virtually 20% of respondents stated that they rely completely on Social Stability benefits to current earnings stream in retirement, though the overwhelming the overwhelming majority of respondents — 70% — felt not sure about regardless of whether or not their retirement monetary financial savings ended up sufficient to previous the comfort of their lives.

    “While the everyday retirement value financial savings of our members arrived out to a little or no above $680,000, the overwhelming majority reported they’d come to really feel rather more protected in the event that they skilled throughout $1.2 million within the monetary establishment,” the ultimate outcomes acknowledged.

    Despite concerns about economic longevity, most respondents predicted their retirement value financial savings to final roughly 13 a few years.

    “This may describe the escalating concept that a number of Individuals actually really feel they could need to get the job accomplished prolonged to protect ample for retirement,” the outcomes stated. “The wonderful data is that, thus far, the monetary system is proving surprisingly resilient despite monetary challenges, as people go on to retailer in retail outlets, dine at eating places, and purchase autos.”

    There was a usually enormous number of responses that respondents had to the idea of a attainable economic downturn. Almost 50 p.c (47%) of these surveyed reported that they had been lowering their investing in response to monetary volatility, whereas 30% acknowledged they might improve their value financial savings. And 26% of respondents each single reported they might commit in “secure” belongings, and that they might keep on to work entire-time.

    Involving 20-25% of respondents reported they might implement for portion-time jobs develop an surprising emergency fund or diversify their investments.

    A really clear majority of respondents talked about they by no means have sufficient income saved, however solely a smaller share of the general respondent pool has entertained the thought of tapping dwelling equity to fund retirement, in accordance to the ultimate outcomes.

    “More than one particular-quarter of toddler boomers shared that the economic system’s increasing unpredictability has led them to focus on their concepts with knowledgeable,” the ultimate outcomes defined. “Nearly 75% reported they hadn’t saved as considerably for retirement as they want, and 5% have even taken equity from their residences to fund their retirement.”


    The survey concerned 758 respondents at or in extra of the age of 59. Of the 758 respondents, 277 had been being presently retired, 445 respondents decided as female, and 309 acknowledged as male. Two acknowledged as nonbinary, and two chosen not to disclose that data and info.

  • Economical homes can do the job tougher for everyone – House loan Tactic

    Housing is a basic human proper that ought to be on the market to everyone. With the United kingdom buying one explicit of the least achieved reasonably priced housing markets in the produced earth and acquiring the best fee of homelessness in Europe, it’s obvious that motion must be taken.

    And if we do it superb, it’s a acquire-gain for completely everyone, not simply people wanting to purchase a dwelling.

    The report on moderately priced housing posted by College School London (UCL) in October earlier yr, obtained beneath my pores and pores and skin.

    It strike me in one other means and I felt compelled to check this material additional extra. UCL estimates that making an added 72,000 reasonably priced/social residences a yr (along with 28,000 a 12 months which are right now turning into crafted) may protect the Uk govt an believed £1.5bn a calendar yr by eliminating substantial prices associated to homelessness. To my data, that is the initially time that one other particular person has quantified the potential reductions from addressing homelessness, and they’re substantial.

    The National Housing Federation and Shelter work out that if the governing administration developed 90,000 new social households, the upfront charges – believed to be throughout £11.8bn – could be repaid in simply simply 11 yrs. We would additionally see financial boosts, actually price a number of durations that preliminary outlay, in the type of greater work by the development do the job, tax revenues, and lessened power on the NHS.

    So how can we accurately implement the ideas of those research, and by which can this switch acquire the builders and the total economic system?

    It is important to begin out by on the lookout at how progress site values are assessed. The final resale price or Gross Advancement Price (GDV) is the projected worth of a scheme as soon as it’s concluded.

    If you deduct the design worth, all prices and want, selling, statutory funds and the required monetary acquire margin, then you definitely’re nonetheless left with the residual site worth that builders are organized to pay again for internet sites.

    Most builders intention for a naked minimal of 20% earnings on value margin, however some would settle for as small as 15%. Of program, the particular issues of the equation will probably be distinct for every developer, counting on economies of scale, whether or not or not they’ve in-property development teams, an confirmed romance with suppliers and so forth, so there will probably be a spread of bids for land.

    There is an individual uncertain ingredient of the prices that has been slowing down commencements on web websites in present a few years. This is the reasonably priced contribution or fee in lieu of the moderately priced contribution.

    Although such fee (or cheap % necessity) is clearly stated in the S106, quite a lot of builders will depend on their talent to contest the moderately priced contribution requirement utilizing the viability evaluation.

    Some are productive and positively maintain to attenuate or do away with reasonably priced stipulations, some should not. The strategy of attempting to remove (or reduce down) the reasonably priced aspect can select months when delaying commencement on internet web page, and delivery of an important deal vital housing: personal and fairly priced alike. Equally, some builders would overbid on progress web sites hoping to achieve the internet pages and counting on this talent to re-negotiate the economical issue.

    UCL’s inspired purpose of 40% reasonably priced housing designed is hard to perform. Bearing in ideas that solely 150,000 new homes a yr are getting designed in the personal sector, the notion that circa 40% of all new create homes actually ought to be cost-effective/social will provide a sizeable impediment and should have a mindset enhance to the market.

    Acquiring a 40% moderately priced ratio will squeeze income and affect feasibility for these builders who’ve now bought speculative internet pages and are hoping to significantly improve worth by buying new planning permission. This may maybe avert these internet pages from being designed, due to this fact an intensive answer is required on this regard.

    Having stated that, acquiring the certainty throughout cheap requirements might introduce an issue of steadiness and regularise the land market place. Lack of potential to problem/get rid of the economical issue will essentially imply one explicit level: the bidding conflict on web websites could have only one fewer variable to rely on and we’ll protect important time which might have often been squandered on viability negotiation with the council.

    There are quite a few positive factors for builders in organising economical housing methods:

    Secured exit at sensible completion de-jeopardizing exit uncertainty

    Bullet proofing the plan in opposition to provide/demand volatility

    Reduced finance costs owing to an early reimbursement or “Golden Brick” association

    Minimized or no promoting charges

    Early launch of revenue/funds

    De-gearing to senior private debt permitting even additional adaptability and room for restructure, if wanted

    It is essential that any initiative shouldn’t punish builders as they’re important to assemble the households of the long term. Instead, if an part of certainty can be launched, then a much bigger proportion of very reasonably priced properties can be factored in. A 40% quantity of economical housing is just not unworkable if builders know completely in progress when it’s turning into launched and can technique for it.

    I select great inspiration from the achievements story of the ‘Housing Initial initiative’ utilized by Finland. They have attained a marked decrease (75%) in homeless statistics in the previous 30 many years and are on a trajectory towards eradicating homelessness by 2027. Finland’s answer is much more balanced with a fundamental prerequisite of 25% of every problem to encompass cost-effective housing, however the thought has been confirmed productively.

    With the United kingdom Common Election having place this yr, it should actually be thrilling to see what the events say about reasonably priced housing of their manifestos.

    Whichever comes about, builders and landowners might want to have time (and, ideally, some subsidy) to accommodate any statutory modifications to economical housing calls for. It should be completed appropriate.

    Uliana Kuzmis is deputy working director, development finance, Hampshire Have religion in Lender