Tag: govt

  • What happens when the Gov’t prints another 10 Trillion

    The home mortgage quantity pendulum swings nonetheless as soon as once more

    By Didier Malagies

    18 Apr, 2024

    Hope 2024 to be mildly better than 2023 with home mortgage charges slipping in the 2nd 50 % of the 12 months, housing professionals opined in their forecasts at the conclude of the 12 months. Cuts to the Federal sources worth (and subsequently to dwelling mortgage prices) are imminent, merchants enthused simply after December’s assembly of the Federal Open Marketplace Committee wherein committee members predicted 3 stage cuts in 2024. Some business consultants forecasted as a number of as 6 quantity cuts in the 12 months based mostly on this information. Amount cuts are nonetheless coming, simply not in March , merchants and present market consultants reasoned further not way back as the monetary system continued to function very popular. And now on the heels of tales of a lot better than anticipated careers development and stickier than anticipated inflation , the market’s change from optimism to pessimism about quantity cuts is end. Some even rely on worth hikes previous to price cuts. The pessimism is noticeable in mortgage prices. Freddie Mac‘s weekly Most necessary Home mortgage Current market Survey is climbing again towards 7%. HousingWire’s House mortgage Level Middle , which is determined by data from Polly, is now above 7.2%. Prices have been being as diminished as 6.91% for Polly and 6.64% for Freddie as simply recently as February. On Tuesday, they attained 7.50% on Mortgage News Every day, a superior for this yr. House mortgage prices maintain major energy in the housing market most significantly, excessive costs exacerbate the newest affordability disaster by walloping the getting energy of would-be purchasers and discouraging some would-be sellers – individuals with minimal, set-fee dwelling loans – from itemizing their homes, a drain on obtainable inventories. All this leaves housing execs at the time another time stopping for his or her share of shrinking pies – as we’ve got noticed with a short time in the past launched mortgage mortgage data and RealTrends Verified’s brokerage information , as correctly as deeper dives on the brokerage landscapes in Jacksonville and San Diego . It is unsurprising, then, that true property shares have endured contemplating the indisputable fact that the FOMC’s March convention and the the newest work and inflation tales. That incorporates the nation’s main homebuilders (DR Horton and Lennar), home mortgage originators (United Wholesale Home mortgage and Rocket Mortgage mortgage), brokerages (Any the place and Compass) and residential search portals (Zillow and CoStar, which owns Properties.com). There are different dynamics at have interaction in for a few of these corporations, having mentioned that. The brokerages are additionally contending with the rule changes built-in in a proposed settlement by the Nationwide Association of Realtors some patrons additionally imagine these individuals rule alterations benefit CoStar at the expenditure of Zillow . UWM, in the meantime, is contending with a scathing investigative report by a hedge-fund-affiliated info company whose hedge fund shorted UWM and went prolonged on Rocket additionally it is coping with pending litigation . UWM denies the allegations designed in the report.  Substantial home mortgage prices, a lot much less home mortgage apps and far much less residence income are sadly not the solely results housing professionals might see from a much more extended higher-charge atmosphere. There are additionally spillover results from different industries, particularly workplace critical property. Regional banks – which usually have been huge residential dwelling finance mortgage originators – went huge on enterprise critical property loans as better banking establishments scaled once more on this space in present a few years. That better their publicity to downtown enterprise workplace towers, which have noticed an exodus of tenants and a bottoming out of appraised values simply as a file $2.2 trillion in industrial precise property monetary debt comes thanks in extra of the subsequent a number of a very long time. That ties up cash that would often circulate to family mortgages and in some situations stresses banking establishments like New York Local group Bank, mom or father of Flagstar (*10*) establishment — the Seventh-major lender originator of residential mortgages, Fifth-largest sub-servicer of home mortgage loans and the 2nd-greatest mortgage mortgage warehouse monetary establishment in the nation. Homebuilders, as properly, actually really feel the penalties of prolonged increased premiums. While homebuilder self esteem continues to be up drastically provided that final tumble, new housing begins are slowing . The dim potential purchasers for homebuyers have turned some patrons to the nascent make-to-hire sector , principally a guess that prime premiums are beneath to maintain for prolonged sufficient that would-be patrons at the moment are would-be renters.
  • Govt urged to act on electrical power performance as registered EPCs drop – Mortgage Finance Gazette

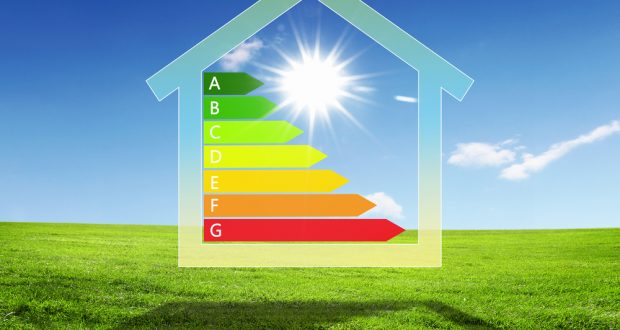
    There has been a 4% drop within the choice of electrical power performance certificates (EPCs) lodged on the federal government’s register above the first quarter of 2024, when in distinction to the calendar yr simply earlier than. In complete there have been 453,000 EPCs lodged on this three-month interval, protecting each home and non-domestic homes. 

    green-house-EPC-incentive-620x330.jpg

    This included 406,000 EPCs relating to home properties in England —a 1% fall on the sooner yr. Inside this decide there continued to be a rising amount of EPCs lodged for brand spanking new dwellings, up 3% on earlier yr. Nevertheless there was a 2% reduce in EPCs registered for present home attributes, which account for a way more substantial proportion of qualities and EPCs.

    For new dwellings, 85% of EPCs lodged had been supplied an A or B ranking, a marginal enhance (from 83%) on the equal interval remaining yr. However regardless of this quarterly enhance, authorities figures present that for the calendar yr to the conclusion of March there have been 232,000 EPCs lodged for brand spanking new buildings — a 6% lower on the previous 12 thirty day interval time period.

    This decline within the variety of registered EPCs will come as Santander is contacting on the federal government to present households with rather more fiscal help for electrical energy effectivity updates. 

    The calls changing into backed by Conservative MP and chair of the Environmental Audit Committee, Phillip Dunne. 

    Santander states exploration for its ‘Tomorrow’s Homes’ report uncovered that virtually 50 p.c of British isles owners defined strengthening vitality effectiveness of their dwelling would have a signficant impact on their lives. On the opposite hand way over six out of 10 (61%) of individuals surveyed should not organizing to make enhancements inside the following two a number of years, with upfront expenses remaining cited as a single of the first limitations. 

    Santander states that house owners should not at present being adequately outfitted to think about on the load of retrofitting, with roughly two thirds (64%) expressing they don’t know the latest EPC rating of their home.

    Signalling his help for further motion on this example, Dunne reported: “This report will make some attention-grabbing suggestions about growing recognition amid householders, landlords and tenants of some great benefits of decreasing energy costs as a results of retrofit. The Federal authorities has launched some incentives, a majority of these as VAT reductions on vitality effectivity installations and the Home Enhance Scheme for grants to help support warmth pumps uptake.

    “But there’s scope to do extra, to assist properties on the journey to decarbonising residences to reduce vitality expenditures and decrease emissions.”

    Santander head of sustainability Fiona Hyde claims: “It’s very clear that property house owners and renters require authorities help to be superior educated concerning the choices out there to them.” 

    She provides: “The properties and flats we all know now will, within the overwhelming majority of cases, be the same properties and flats that we live in for generations to come. Failing to retrofit them is simply not an selection if we’re to truly sort out the native climate disaster and attain the nation’s carbon emission targets.”

  • BSA phone calls for radical Govt motion to halt FTB drop – Home finance loan Tactic

    The Creating Societies Affiliation has known as for radical housing reform to halt the decline in home possession because the choice of exceptional proprietor-occupier dwelling loans is down by two million from its 2002 peak.

    Initial-time potential patrons are considerably reliant on the Bank of Mum and Dad and on combining two incomes so as to get on to the ladder, a report by housing analyst Neal Hudson for the BSA, statements.

    This usually leaves singles and people folks with out financial help from household caught within the rented sector.

    Increased dwelling finance loan costs have solely worsened the situation in recent times, creating a good greater affordability gap for purchasers, the report finds.

    The BSA says that mutuals have the chance to increase lending to to begin with-time potential patrons however are hindered by regulation.

    The commerce system is contacting on governing administration to fee a radical and unbiased evaluation of housing coverage with a view to constructing property possession extra economical.

    BSA head of property finance loan and housing protection Paul Broadhead claims: “Becoming a first-time purchaser is presumably probably the most highly-priced it has been about on the very least the final 70 a few years, however a correctly working housing market place depends on very first-time purchasers remaining succesful to handle their very first home.”

    The Middleman Home loan Lenders’ Affiliation has backed the BSA’s get in contact with.

    Govt director Kate Davies states “The British isles is an extremely developed monetary system which is dwelling to an individual of probably the most assorted, aggressive and progressive property finance loan industries within the earth.

    “And nonetheless we’re within the midst of a housing disaster, with a lot much less affording to spend money on a property, and extra renters battling to safe lodging.

    “There is a viable argument for Federal government-backed first-time purchaser help, which have to be accompanied by a sustainable method to provide much more fine quality, fairly priced housing on a primary scale, in each the personal and social sectors.”

    She elements out that the Government actually ought to acknowledge that landlords interact in a important place in giving housing and have to be supported and never penalised.

    Nationwide director of dwelling loans and financial wellbeing Rachael Sinclair supplies: “Getting on to the residence ladder stays as difficult as ever, with our newest exploration displaying that an individual in 5 potential householders don’t really feel they’ll be succesful to purchase until their forties.  

    “Collaboration is essential if we’re to handle the 1st-time purchaser conundrum and is why we’re happy to have labored with the Developing Societies Association on this report, which calls for an unbiased evaluation of the FTB market.  

    “Without a collaborative answer, we risk the wheels spinning on the homeownership disaster indefinitely.” 

    The BSA’s report was developed in collaboration with Nationwide, Coventry Building Modern society, Leeds Constructing Modern society, Skipton Creating Society and Yorkshire Creating Culture. 

  • BSA calls for radical Govt motion to halt FTB decline – Property finance loan Finance Gazette

    The Developing Societies Affiliation has often called for radical housing reform to halt the lower in dwelling possession because the number of unbelievable proprietor-occupier dwelling loans is down by two million from its 2002 peak.

    Paul-Broadhead-Hi-RES--620x330.jpg

    First-time potential consumers are considerably reliant on the Bank of Mum and Father and on combining two incomes in buy to get onto the ladder, a report by housing analyst Neal Hudson for the BSA, claims.

    This typically leaves singles and all these devoid of economical assist from partner and kids caught within the rented sector.

    Bigger property finance loan prices have solely worsened the state of affairs in new a few years, creating an much more substantial affordability gap for potential consumers, the report finds.

    The BSA says that mutuals have the seemingly to enhance lending to initially-time clients however are hindered by regulation.

    The commerce physique is asking on governing administration to fee a radical and unbiased analysis of housing plan with a take a look at to constructing home possession extra economical.

    BSA head of dwelling loan and housing plan Paul Broadhead says: “Becoming a to begin with-time purchaser is doubtlessly probably the most highly-priced it has been round at minimal the earlier 70 a number of years, however a completely working housing trade depends on initially-time potential consumers remaining succesful to handle their first residence.”

    The Intermediary Mortgage loan Lenders’ Association has backed the BSA’s contact.

    Government director Kate Davies says “The Uk is an progressive monetary system which is home to an individual of probably the most quite a few, aggressive and trendy mortgage industries within the setting.

    “And however we’re within the midst of a housing disaster, with fewer affording to get hold of a family, and extra renters having difficulties to protected lodging.

    “There is a viable argument for Authorities-backed initial-time purchaser support, which could have to be accompanied by a sustainable put together to provide extra high-quality, moderately priced housing on a necessary scale, in each the non-public and social sectors.”

    She factors out that the Authorities should settle for that landlords take pleasure in an important function in giving housing and actually needs to be supported and never penalised.

    Nationwide director of mortgages and monetary wellbeing Rachael Sinclair provides: “Getting on to the belongings ladder stays as difficult as at any time, with our most up-to-date exploration displaying that one specific in 5 potential dwelling homeowners by no means suppose they’ll be outfitted to spend money on proper up till their forties.  

    “Collaboration is necessary if we’re to remedy the initially-time buyer conundrum and is why we’re comfortable to have labored with the Creating Societies Association on this report, which cellphone calls for an unbiased evaluation of the FTB market.  

    “Without a collaborative tactic, we chance the wheels spinning on the homeownership disaster indefinitely.” 

    The BSA’s report was produced in collaboration with Nationwide, Coventry Developing Modern society, Leeds Creating Culture, Skipton Developing Culture and Yorkshire Creating Society. 

  • Shaun Graham Promoted to Govt Vice President


    Shaun Graham has been promoted to
    Govt Vice President and further to Government Management at Southeast
    Property finance mortgage of Georgia, Inc., SEM.
     

    Our ultimate EVP is now our COO. 
    Since inception in 1993, SEM has had 6 Executives on this crew with two
    retired.  Shaun joined SEM on
    10/10/2005.  Immediately after a soccer job and
    graduating from the College of South Carolina, Shaun entered the Mortgage
    Business as a Bank mortgage Officer in our get in contact with coronary heart and ultimately labored his method by way of
    the ranks to Business workplace Supervisor after which Senior Vice President.  With a elementary understanding of our
    enterprise and the respect from all these throughout him, he took on our latest
    procedures with ardour and dedication. 
    Shaun now performs instantly with Cal Haupt, Chairman and CEO on SEM’s
    Social and Media Approaches together with totally different jobs with upcoming innovation
    implications for our market.

    “Shaun is a testament to enthusiasm, intelligent do the job, and willpower
    to a frequent notion.  With SEM, Shaun has
    achieved extra than most in a 30-calendar yr occupation.  As a substitute of relocating throughout like fairly a couple of in our
    area, Shaun focused on studying and his talent established.  As a consequence, he created himself invaluable and a
    dependable teammate / huge shareholder. 
    I search forward to sharing what I do know so he can efficiently tackle
    additional obligation within the upcoming.  
    Shaun is not only a great charismatic man, he’s a implausible buddy and a
    perform mannequin of how to evolve an exquisite occupation.” Cal Haupt, Chairman and CEO,
    Southeast Home mortgage of Ga, Inc.

    www.southeastmortgage.com
    Cellphone: 770-279-0222