Tag: enhance

  • Glenigan expects article-election enhance for United kingdom housing – Home loan System

    The development subject will facial space shut to-time interval challenges together with sluggish financial development and persistently superior need charges. This is in accordance to Glenigan’s United kingdom Development Market Forecast 2024-2026 which does however assume the outlook to brighten because the forecast time interval progresses.

    Glenigan implies that the brand new Federal authorities, which has a considerable overwhelming majority, is by now slicing down political uncertainty and rallying markets.

    It goes on to say that protection picks throughout development initiatives will possible be made at a rather a lot faster velocity, boosting effectivity.

    This alerts restoration within the not-so-distant long run, with a modest enhance in project-commences predicted within the latter 50 % of 2024 lifting begins off by 3% this yr. As the general financial system picks up additional in 2025, Glenigan forecasts 7% growth, and 6% in 2026.

    Commenting on the forecast, Glenigan’s financial director Allan Wilen claims, “There are signs of development, signalling a gradual restoration. For instance, within the private housing sector, we foresee begins off will choose up within the latter half of this yr, pushed by improved affordability and brighter monetary potential purchasers.”

  • CBI, MRI Program greatly enhance rental payments

    CBI, MRI Computer software program improve rental payments | Australian Broker News

    News

    CBI, MRI Computer software program enrich rental payments

    Streamlining precise property transactions

    CBI, MRI Software enhance rental payments

    The Commonwealth Bank (CBA) and MRI Computer software program have launched a partnership to streamline fee procedures within the family genuine property sector.

    This collaboration goals to enhance the fee processes for Australian actual property brokers, property supervisors, and tenants by integrating CBA’s Smart Serious Estate Payments answer with MRI’s Assets Tree software program program.

    Enhancing the rental fee data

    The initiative will ship tenants with a much more economical solution to management their rental payments.

    Functions include versatile fee workflows, the capability to regulate fee approaches very simply, and visibility into fee historic previous and approaching expenditures.

    This method goals to reduce the time and vitality used on operating rental payments for all events related.

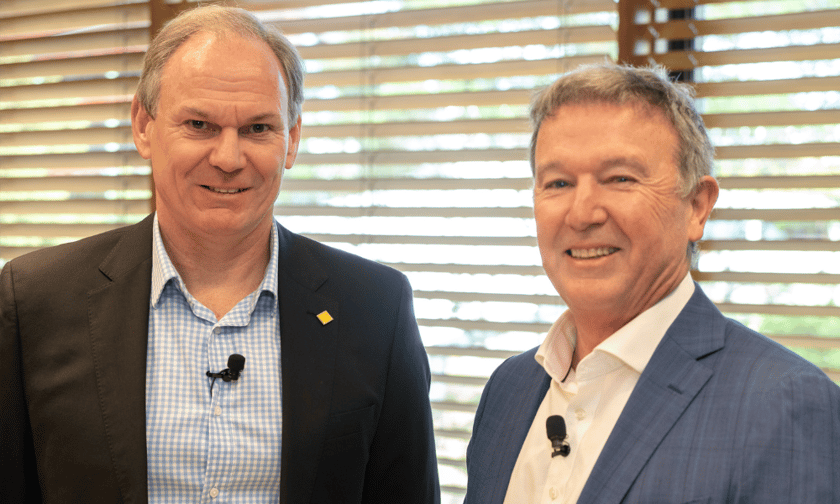
    “This digitised reply will make it uncomplicated and easy for each individual within the rental ecosystem to make and purchase rental payments,” stated Mike Vacy-Lyle (pictured beforehand talked about left), CBA group govt of group banking, in a media launch.

    Prioritising fundamental security and safety

    With the combination of predominant digital fee selections like BPAY, fast debit, PayTo, and playing cards, the Good True Estate Payments reply not solely simplifies the transaction technique but additionally boosts stability, based on CBA.

    “The safety of payments continues to be one in every of our core priorities and the brand new answer will provide a safer and extra safe digital data for tenants, actual property brokers, and residence professionals,” Vacy-Lyle claimed.

    The “announcement is a significant leap forward to addressing friction factors and fee safety for our Home Tree clientele,” stated David Bowie (pictured larger than appropriate), Asia Pacific senior vp and govt controlling director for MRI Computer software program. 

    Supporting development in critical property

    Outside of the fee answer, CBA can be devoted to supporting critical property brokers in rising their corporations. This comprises funding options for hire roll acquisitions and, for a confined time, waiving valuation charges to lower operational costs. These initiatives are designed to facilitate improvement and lower down financial strains on actual property organizations.

    Get the most well liked and freshest home mortgage data delivered correct into your inbox. Subscribe now to our FREE day-to-day e-newsletter.

    Similar Stories

    Maintain up with the latest information and gatherings

    Be part of our mailing guidelines, it’s no value!

  • Irrespective of moratoria, foreclosures enhance 20% in October

    In spite of foreclosures moratoria maintaining fixed in fairly just a few states, a present foreclosures report from ATTOM Knowledge Solutions revealed a complete of 6,042 U.S properties commenced the foreclosures process in October. That amount is up 21% from a month in the previous, however even now down 79% from this identical time final calendar 12 months.

    However, some specific particular person states did see that quantity climb year-in extra of-calendar 12 months comparable to Idaho, which was up 109%, and Nebraska, up 56%, contemplating the truth that ultimate October.

    As for foreclosures filings – which embrace default notices, scheduled auctions or lender repossessions – about 11,673 U.S homes submitted in October. That amount is up 20% from a month again, however even now down 79% from this identical time ultimate 12 months.

    According to the report, states with the optimum foreclosures charges have been South Carolina, Nebraska, Alabama, Louisiana and Florida. Some metros in specific ended up even worse off than folks, comparable to Peoria, Illinois, in which one specific in nearly each 1,543 housing fashions was in a foreclosures submitting. In Beaumont, Texas, that amount was one in every 1,880, and in Birmingham, Alabama, one in nearly each 1,993.

    “It’s a minor gorgeous to see foreclosures motion rising in spite of the quite a few foreclosures moratoria which can be in place,” reported Rick Sharga, government vp of RealtyTrac, an ATTOM Data Alternatives enterprise. “It’s possible that quite a few of these homes had been presently in the early phases of default previous to the pandemic, or are vacant and deserted, which may make them candidates for expedited foreclosures steps.”

    How servicers can prepare for seemingly default wave

    Sutherland Home finance mortgage Services President Krish Swaminathan discusses the upcoming wave of servicing, how servicers can handiest talk with their consumers and the know-how obtainable to assist with compliance, even in a perform-from-house environment.

    Presented by: Sutherland

    Bank repossessions on REO properties (actual-estate owned) had been additionally up 28% from previous month for a general of 2,577 U.S properties. Once extra, the amount is down 12 months-more than-year 81%.

    Sharga talked about it’s essential to retain the portions in context – even with these boosts, over-all foreclosures steps are nonetheless beneath previous 12 months’s ranges by about 80%.

    But these folks portions might maybe be intently affected by moratoria led by authorities entities. In accordance to Black Knight’s Mortgage Watch Report for September, widespread foreclosures moratoria have retained debtors who might probably in any other case confront foreclosures proceedings in a 90-day delinquency standing. The report additionally found much more than 2.3M dwelling house owners – 5 occasions the choice stepping into 2020 – keep 90 or way more occasions earlier owing, however not in foreclosures.

    On Aug. 27, in a bid for continued stability, the Federal Housing Finance Agency prolonged its moratorium on foreclosures and evictions for debtors with dwelling loans backed by Fannie Mae and Freddie Mac till Dec. 31. That very same day, the Federal Housing Agency additionally prolonged its moratorium to Dec. 31.


    Nevertheless there was no phrase on whether or not one other extension will arrive in 2021, the FHFA did say it would proceed to observe the COVID-19 pandemic and “replace pointers as wanted.”

  • Mortgage and hire charges enhance, leasehold ‘burden’ lifts: Barclays   – Mortgage Method

    Mortgage mortgage and lease funds rose 3.6% within the calendar 12 months to April, ending a slowdown of those costs within the 1st a couple of months of the calendar 12 months, info from Barclays reveals.  

    But housing costs keep beneath the 12-thirty day interval widespread of 6.5%, “indicating that expenditures are even now heading in the fitting method across the extra time expression,” says the big avenue lender from examination of 1000’s and 1000’s of client accounts.  

    Having mentioned that, it elements out that companies bills and ground hire will enhance have flip into “an shocking burden for quite a few bothered householders.”  

    It claims that simply 37% of its prospects regard these costs as inexpensive.   

    It offers: “On prime of the big charge tag, most leaseholders actually really feel blindsided by the charges, as simply 33% recall at present being made knowledgeable of the prices earlier than shopping for their home, and solely 23% said they acknowledged the speed at which these prices would enhance.”  

    The examine particulars out that couple of property house owners believed these charges stand for excellent worth.  

    It says solely 13% sense they get “good worth for cash” and simply 10% imagine their charges are “spent successfully”.   

    Also, 17% of people paying out service and ground lease charges are anxious they gained’t be ready to supply their properties because of the truth of those charges.  

    The analyze additionally elements out that home shelling out on areas these as homeware, electronics and Do it your self fell by 4.1 per cent within the yr to April, “with many purchasers opting to postpone renovations”.  

    Barclays head of financial savings and mortgages Mark Arnold suggests: “Consumers and collectors alike are anticipating a drop in curiosity charges this 12 months, however optimism is understandably tentative because the sector is however emotion the results of ultimate 12 months’s volatility.   

    “Our info reveals that Brits are nevertheless going by means of larger hire and mortgage mortgage funds, regardless that charges are nonetheless slowing down over the for an extended interval time period.  

    “Many residence house owners have moreover been hit by vital firm charges within the wake of elevated inflation.”  

    Barclays suggests its information is drawn from credit score rating and debit card transactions in between 17 February and 22 March as properly as mortgage and rental funds info from the lender’s current accounts amongst 23 March and 19 April.  

    Info company Opinium Research additionally surveyed shopper paying for Barclays, which concerned a consultant pattern of two,000 grownups amongst 19 April and 23 April.  

  • Mr. Cooper’s income triple as servicing’s fortunes enhance

    Mr. Cooper’s newest outcomes staged a restoration from the previous fiscal interval’s earnings drop reflecting an fascination-charge environment that shifted in servicers’ favor.

    The house mortgage enterprise described $181 million in internet income for the to begin with quarter, up from $46 million within the earlier a couple of months of 2024 and $37 million a 12 months earlier.

    The nonbank’s last outcomes embody to different indications that some components of the first quarter’s “higher for longer” quantity state of affairs have had an upside for mortgage firms with environment friendly servicing firms.

    “This setting is taking part in to the strengths of our nicely balanced group product,” claimed Mr. Cooper President Mike Weinbach in a push launch.

    Automation the enterprise is investing in leverages that method, executives talked about all through an earnings name.

    “Our technological know-how method has benefited from our balanced firm mannequin,” Mr. Cooper CEO Jay Bray stated.

    Although charges from a cyberattack and pissed off valuations of house finance mortgage servicing rights set a dent within the former quarter’s earnings, automation and MSRs ended up further useful contributors in the midst of the primary three months of this calendar 12 months.

    The group is also arranging to see additional advantages from its partnership with Sagent, which lets Mr. Cooper to be the to begin with to examine the trade vendor’s new Dara system.

    Automated efficiencies assisted servicing develop $273 million in pretax working earnings at some stage in the quarter, in line with the group. The equal determine for originations was $32 million, with that part additionally benefiting from the software program of automation to features.

    Pretax working income in servicing has grown steadily and considerably consistent with efficiencies of scale in its portfolio. It was up from $229 million the previous quarter and $157 million a 12 months beforehand.

    The firm’s servicing portfolio was simply shy of $1.14 trillion within the first quarter, firmly beforehand talked about the 13-digit benchmark degree that’s prolonged been its aspiration to maintain.

    Whilst Mr. Cooper ongoing to be an avid purchaser of bulk MSRs within the quarter, executives indicated that its urge for food was not numerous and that it’s attempting to maintain a watch the 2 on irrespective of whether or not pricing stays engaging and the soundness of its funds and liquidity.

    Mr. Cooper plans to extend throughout $100 billion in UPB break up amongst MSRs and subservicing to its portfolio within the second quarter, Weinbach talked about.

    “Following that, progress will depend on the yields available out there place,” he added. “Though we’re optimistic a couple of ongoing strong present and MSRs, we’re additionally viewing some signs of intense pricing.”

    In the meantime, in originations, the unpaid principal concord of property loans funded in the midst of the preliminary quarter was $2.9 billion, up marginally relative to $2.7 billion in each the fourth quarter of ultimate 12 months and the initially a couple of months of 2023. 

    The majority of originations at some stage in the quarter arrived in as a results of the correspondent channel, which produced $1.5 billion in loans by the time frame, in comparison with $1.4 billion from immediate-to-purchaser assets. 

    In the previous quarter, Mr. Cooper funded $1.5 billion mortgages as a results of the correspondent channel and $1.2 billion as a results of immediate-to-customer. In the course of very first-quarter 2023, the agency funded $1.4 billion in quantity by direct-to-buyer and $1.3 billion by the use of correspondent.