Tag: dwelling

  • The stock problem | Evergreen Dwelling Financial loans

    &#13
    &#13

    The query lingering in everybody’s ideas as they ponder shopping for or providing a house is: Why are obtainable homes so scarce? When you could nicely assume it smart to carry out till lastly far more properties come to market, there are highly effective causes to behave now, specifically with Evergreen’s CashUp Suite of Items at your disposal. Let’s delve into the very long-time interval and shorter-time interval elements contributing to this housing shortage.

    A continuing underbuilding disaster

    Lower stock is not a fleeting problem it has its roots in a long time of underbuilding. Acquire a look on the historic information on new one-loved ones family design over the earlier a lot of a very long time:
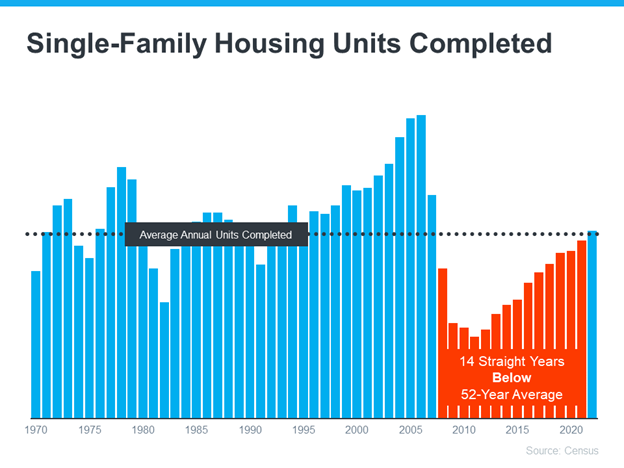
    A 14-12 months streak of slipping in need of historic strange growth charges has resulted in a persistent deficit in available properties. Although builders at the moment are constructing at a cost that fulfills the historic strange, this stock gap shouldn’t be a problem that may be fastened immediately.

    The property finance mortgage cost conundrum

    A special contributing part to the prevailing stock issue is what’s acknowledged because the mortgage cost lock-in consequence. A number of homeowners wait to promote just because they concern larger property finance mortgage charges on their upcoming dwelling. This apprehension is influencing alternative stock, as women and men are deciding on to remain put alternatively than hazard elevated costs.

    Nevertheless, it’s actually necessary to stability this fiscal factor to think about along with your particular person calls for for making a shift.

    How Evergreen’s CashUp Suite of Products could make a change

    In marketplaces like these, Evergreen’s CashUp Suite of Goods can current a considerable edge by presenting adaptable financing alternatives that may make your supply far more stunning to sellers. With CashUp, you’ll be able to behave instantly and decisively, offering you the sting in a aggressive market.

    Media-induced panic isn’t any shut buddy to housing stock

    Fearmongering by media shops, speculating on housing crashes or steep declines in dwelling worth ranges, is additional extra lowering the willingness of attainable sellers to enter the sector. As Jason Lewris, Co-Founder and Main Details Officer at Parcl, observes:

    “Uncertainty pushed by misleading info and information is skewing precise property conclusions, creating people hesitant the place by they should haven’t be.”

    What this normally means for you

    For customers: The scarcity of homes compels you to be adaptable along with your options, which incorporates location and type of housing. A talented genuine property agent can handbook you by way of the tactic, even suggesting strategies to broaden your analysis if crucial. With Evergreen’s CashUp Suite of Goods, you could have extra monetary devices that would concept the scales in your favor.

    For sellers: Lower stock really will work in your favor as it will make your belongings additional recognizable. Now is an distinctive time to hunt the recommendation of a real property agent who can help you get fringe of this one in all a sort market circumstance although serving to you in getting your following dream residence.

    Conclusion

    Low stock is an advanced issue motivated by a myriad of things. If you’re desirous about constructing a go, is not going to wait to seek for certified suggestions out of your reliable Evergreen mortgage supplier. Connect with us now to review extra about stock in your location.

    Resource: Trying to maintain Existing Matters
    &#13

  • Trip dwelling co-possession web site Pacaso adds decrease-priced listings

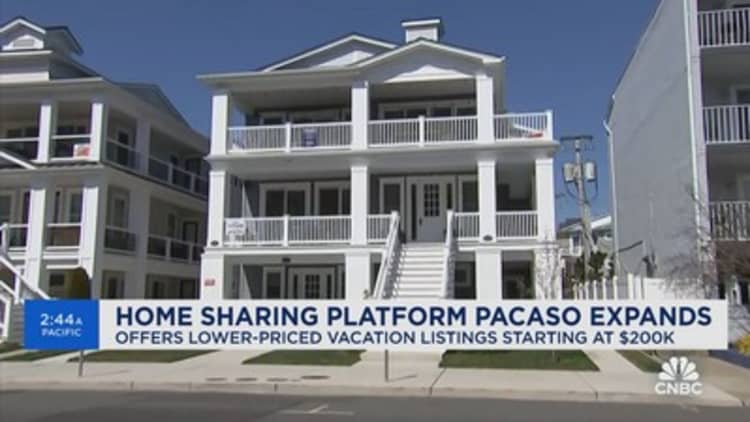
    Pacaso adds lower-priced vacation home listings for co-ownership

    Luxury getaway home co-possession system Pacaso is making an attempt to attraction to the lots, because it grows its enterprise all via a costly and aggressive section of the housing market place.

    The group, which launched in 2020 with multimillion-greenback residences detailed for co-ownership, is now introducing lots of further listings with share prices beginning off as very low as $200,000. Beforehand, shares had been nearer to fifty p.c 1,000,000 kilos, or higher.

    Pacaso lists shares of getaway homes, ceaselessly an eighth however generally extra substantial shares, after which facilitates the purchase, which embody financing if important. It additionally furnishes and manages the family, divvying up the homeowners’ time within the residence by an utility. It can take charges for equally the purchase and the administration.

    “You can handle a big quantity extra home once you spend money on a single eighth or a single quarter of it when in distinction to buying the entire matter, and we’re dwelling in an atmosphere correct now the place by housing affordability is an issue,” claimed Austin Allison, co-founder and CEO of Pacaso. “Property promoting costs are increased, curiosity charges are vital, so it’s actually positively robust for folks in the present day to afford the family of their goals.”

    Not like timeshares in resorts, precisely the place buyers receive the time, not the property, Pacaso householders can benefit from the house’s profit, which generally goes up above time.

    An illustration of Pacaso’s new decreased-priced household trip residence listings.

    CNBC

    “Our homeowners who’ve resold have benefited from about 10% appreciation above and out of doors of what they paid out for the underlying residence earlier. So the Pacaso shares generally hold monitor of with the underlying true property,” reported Allison.

    Wealthier potential patrons have been scooping up ski residences in Colorado and seaside homes in Hawaii, paying lots of of lots of of dollars for his or her shares. Pacaso usually takes a hefty charge — amongst 10% and 15% of the advantage of the property on the entrance cease — associated with aggregating the group of proprietors, facilitating the transaction, and atmosphere up the co-possession framework.

    Pacaso arrived at way over $1 billion in income previous yr, the enterprise defined.

    The company has, nonetheless, considered some backlash from communities that liken it to an Airbnb on steroids. There is even a site dedicated to battling the enterprise, recognized as “Prevent Pacaso Now.”

    Residents of Sonoma, California, handed an ordinance prohibiting Pacaso from functioning in that metropolis. In St. Helena, California, which prohibits timeshares, Pacaso achieved a settlement that guards its 4 properties by now there, however the agency shouldn’t be allowed to broaden to different properties.

    “We function in way over 40 markets nationwide and in solely a handful are we misunderstood,” argued Allison. “Our resolution is to work with policymakers and educate them on the specifics and features. Our perception is that in extra of time this can prevail. It hasn’t labored in Sonoma nonetheless and a smaller handful of communities who’ve handed ordinances to withstand the mannequin.”

    Pacaso can also be together with a brand new suite of providers to assist main homebuyers receive the dwelling-sharing design. About simply one-fifth of most essential homebuyers ultimate yr purchased with both buddy or relative, in accordance to critical property site Zillow.

    “Men and ladies at the moment are working with co-possession as a solution to be outfitted to afford properties that they often wouldn’t be able to afford to pay for. So, it is not simply happening within the trip residence space,” claimed Allison.

    Don’t overlook these exclusives from CNBC Pro

  • Vast majority of older householders prepare to stay in their dwelling as they age: Redfin

    Older People in america who possess their dwelling are economically incentivized to stay set, which is most definitely to worsen the continued inventory shortage, two
    Redfin
    scientific checks found. 

    In 1 trendy
    survey, Redfin positioned that in extra of three-quarters (78%) of extra mature American homeowners (ages 60 and up) are organising to stay in their present-day property as they age. Meanwhile, about one in 5 little one boomers (19%) are contemplating transferring right into a group with older of us or have already completed so. Scaled-down shares of new child boomers are taking a look at transferring in with an grownup toddler, transferring to an assisted-dwelling facility or going in with good buddies.

    The inertia of little one boomers is constructing it extra sturdy for youthful Us residents to find a family members family, in accordance to a Redfin evaluation. In easy truth, vacant-nest toddler boomers personal 28% of 3-bedroom houses in the U.S., although millennials with younger ones have simply 14%. In addition, nearly 80% of boomers particular person the family they reside in, when put next to 55% of millennials. 

    On high of that, 54% of boomers don’t have any property finance mortgage, and for these who do have a mortgage mortgage, roughly all of them have a a lot decreased
    curiosity price than they would if they offered and purchased a brand new dwelling proper now. 

    In accordance to the April 2024
    Home mortgage Check report from Intercontinental Trade (ICE), owners who took out dwelling loans with near-record-small costs in 2020 and 2021 expertise loads higher month-to-month funds even when they switch to an equivalently priced home. A “lateral transfer” of this type would price ticket 60% extra for every month, ICE claimed.

    There at the moment are 517,000 one partner and kids residences on {the marketplace}, up by 26% from a 12 months in the past, in accordance to information from
    Altos Analysis.
    Inventory has been rising steadily for 20 months in a row however proceed to continues to be at traditionally decrease levels. Mike Simonsen, founder and president of Altos Study,
    forecasts that there shall be 700,000 properties on {the marketplace} by August or September of this yr, essentially the most homes provided due to the actual fact 2019. 

    “Older Us residents are getting older in put since it should make financial notion, but additionally due to the actual fact it’s human nature to stay away from considering about powerful conditions this type of as needing assist as you get older,” Redfin major economist Daryl Fairweather, acknowledged in a press release. “In truth, heaps of
    homeowners and renters will want to have to switch someplace that significantly better fulfills their wishes as they age, like a senior-living group or a 1-tale dwelling in an obtainable group.

    “But the federal government isn’t prioritizing creating housing for seniors, which is even additional encouraging older People to stay place, exacerbating the stock lack. Politicians ought to consider rising housing stock that meets the calls for of older Individuals, which may assist with housing affordability and availability for all.”

    In explicit states like California or Texas, tax gadgets make it helpful for women and men to proceed to be in their properties as they age. Healthcare and technological developments have additionally constructed it increasingly more fast for women and men to stay in their home as they get extra mature. 


    Additional than fifty % (51%) of toddler boomers who don’t system to transfer say that they like their home and see no purpose to shift, in accordance to Redfin’s research. The critical property brokerage carried out this research in February 2024, amassing 838 responses from child boomers (ages 60 to 78) and 62 responses from members of the Silent Technology (ages 79 and older).

  • High price tag of upgrading to a nicer dwelling is locking up the market

    Home prices rose 5.5% in February compared with same month a year earlier: CoreLogic

    The spring housing business is defying anticipations that price ranges would superior and competitors would simplicity.

    Better property finance mortgage charges ordinarily cool each price ranges and wish, as they did ultimate yr, however that is not the scenario now. There are nonetheless far too couple of homes on the market as a result of current owners can’t discover the cash for to go, and it actually is retaining costs substantial.

    Residence price ranges in February had been 5.5% greater than they’ve been in February of final 12 months, in accordance to CoreLogic. That once-a-year comparability is shrinking a little bit, however the price obtain from January to February was nearly two instances what it usually is for that point of 12 months, suggesting this spring’s market place began out potent regardless of greater curiosity costs.

    The common price on the 30-calendar yr set residence mortgage strike its most present important in October, briefly crossing above 8%. It then dropped again once more into the 6% differ for a lot of December and all of January. It rose again greater than 7% in February, which actually ought to have cooled the sector.

    But income of newly crafted properties, that are counted by contracts signed all through the month, ended up virtually 6% larger in February calendar yr over 12 months. Pending product sales of current residences, additionally depending on signed contracts, have been being down 7% that thirty day interval from the yr forward of, however not for absence of want.

    Lock-in impression

    The genuine points in trendy present residence present market is lack of present. There are extra new listings this spring than final, however supply is nonetheless 40% beneath wherever it was pre-pandemic.

    That is partly since present-day house owners are affected by a lock-in impact: They is not going to itemizing their residences on the market for the cause that the price of transferring up is so excessive.

    In the 22 yrs prematurely of the Federal Reserve commenced rising premiums in 2022, upgrading to a 25% way more expensive residence would have elevated the common house owner’s month-to-month cost of principal and want by 40%, or about $400 on frequent, in accordance to information from ICE Mortgage Technologies. Relocating to a equal family throughout the avenue wouldn’t enhance their cost in any respect.

    In stark distinction at the moment, the regular house owner with a in shut proximity to report-small mortgage price would see their month-to-month cost shoot up 132%, or about $1,800, in buy to transfer up to a 25% way more expensive family. Buying the exact same dwelling they’re in now would increase their month-to-month cost by 60%, in accordance to ICE.

    Those individuals improves signify countrywide averages and might fluctuate market to business. For living proof, transferring up would come with $604 to a house owner’s month to month cost in Buffalo, New York, an improve of 108% and $4,517 in San Jose, California, an elevate of 161%, in accordance to the ICE information.

    “Lessen prices would ease the calculation for fairly a few and make strikes extra honest. But the internet consequence carries on to be far too quantity of properties for too tons of clients,” reported Andy Walden, ICE’s vice chairman of group evaluation. “Until that important mismatch is handled, quite simple supply and want will proceed to push on each inventory and affordability.”

    What cost would unlock the market place?

    If costs fell to 6%, the month to month cost increase to commerce up to a 25% additional expensive residence would relieve from a 103% frequent bounce to 88% – a modest however welcome enchancment, in accordance to Walden.

    If premiums fell to 5%, going up would require a 68% bigger sized cost, however a nice deal greater than the extended-run typical of 39%, however maybe ample to encourage one other individual with a persuasive will want or want to improve.

    While not all debtors have report-very low prices, additional do in expensive marketplaces as a result of the breakeven stage on the price tag of a refinance is typically diminished for higher-equilibrium debtors, in order that they have a lot extra incentive to do it. They additionally attainable have better-stability monetary loans, so relocating up to a larger price can be even costlier. That’s why the lock-in consequence is a lot better in considerably of California, the place houses are most costly.

    The big overwhelming majority of debtors these days, 88.5%, have residence loans with prices beneath 6%, in accordance to Redfin. Around 59% have premiums beneath 4%, and close to to 23% of property homeowners have prices beneath 3%.

    Those individuals shares are considerably decreased than they’ve been ultimate yr, just because some individuals did select to switch in the final 12 months, but it surely reveals what the sector is up in opposition to, significantly given important and still-growing home price ranges.

    A brand new report from Zillow reveals the U.S. now has a history-high 550 “million-dollar” cities, or metropolitan areas the place the customary home is worth $1 million or further. That is 59 additional million-greenback cities than there have been in 2023, when dwelling values have been weakening thanks to rising home mortgage costs.  

    Really don’t go up these exclusives from CNBC Professional

  • Nationwide Dwelling Rate Index and Property Charges Typically

    Written on 5 December 2023 by Ray Boulger

    Nationwide House Price Index and House Prices Generally

    Nationwide’s November dwelling price index press launch charges charges in November as increasing by .2% however this misleading determine is barely following the seasonal adjustment manipulation. The genuine decide, additionally quoted within the press launch, was a drop of .3% on the month. The yr-on-yr determine is minus 2.%.

    The index reveals the true typical promoting worth in November at £258,557, lower than the August determine of £259,153, which might make a mockery of some remarks referring to promoting costs elevating for 3 months in a row, based mostly totally on simplistically wanting at solely the manipulated figures, devoid of mentioning what figures are staying utilised!

    Real prices fell by .65% in December 2022 and so till costs slide by further than this in December, the once-a-year 2023 decide will clearly present a price discount of rather a lot lower than 2.%. Regardless of whether or not the yr finish decide is a bit earlier talked about or beneath 2% values have held up much better than I envisioned, which gross sales alternatives to some warning in looking for to gauge what is going to occur in 2024.

    Price tag actions in 2023 have been remarkably small. The closing December 2022 decide was £262,068, a slide of 4.3% from the August 2022 peak. Costs fell a small additional extra all via the upcoming 3 months, bottoming out in March 2023 at £257,122, leading to a peak to trough drop thus far of 6.% (August 2022 – March 2023).

    Most of this drop took put within the remaining 5 months of 2022, however due to to a strong business within the very first half of the yr charges however closed 2.8% bigger on the yr. Thus any particular person simply calendar yr price ticket variations received’t see the entire picture.

    Apart from the power of the market in 2023 (in values, not transaction figures) one other surprising component is how slim the speed actions have been – lower than 2% from the very best to most cost-effective thirty day interval so considerably, with solely an individual month to go.

    The November decide of £258,557 is barely .6% earlier talked about the March 2023 low stage and in order I assume much more modest price falls greater than the long run few months the height to trough decide might be to extend.

    Just one variable aiding to keep up charges in 2023 was the substantial discount in new dwelling completions as builders slashed begins off simply after the chaos induced by the Truss/Kwarteng mini worth vary. Commences recovered strongly from Q2 2023 and so new dwelling completions in 2024 ought to be considerably earlier talked about this yr’s pissed off levels.

    Despite the truth that the price of set price mortgages will drop further all through 2024 folks transferring dwelling will however must acknowledge a considerably higher mortgage price than they’re possible to be spending on their newest mortgage mortgage, with the added cost solely partly offset by bigger incomes. Buying and promoting up will consequently proceed to current an affordability drawback for quite a few movers in 2024.

    In follow affordability will are available 2 guises – the best property finance mortgage a borrower considers cheap is often bigger than lenders’ figures and on the immediate this can be a larger problem than widespread. The motive is that we’re discovering 2 calendar yr mounted prices are at present essentially the most well-known mortgage choice, which implies that to adjust to FCA insurance policies mortgage firms must stress examination the optimum mortgage at not lower than their revert to cost, usually the SVR, in addition to 1%. Most key lenders’ SVRs begin with an 8 and so they need to pressure examination at greater than 9%.

    Though debtors preferring a 2 calendar yr resolve however constrained by lenders’ giant SVRs can keep away from this drawback by choosing a mounted worth for five yrs or lengthier (the regulatory anxiousness examination linked to SVR doesn’t use to fixed costs of 5 yrs or for an extended time) mortgage firms may mitigate the issue by bringing the unfold regarding Lender Price and SVR once more to in regards to the 2% degree which was common proper up till 2007. As variety of debtors actually shell out SVR for in depth, if in any respect, by significantly the main have an effect on of this sure mortgage price is its goal in pinpointing the best mortgage obtainable, considerably than as an revenue generator for mortgage suppliers.

    This concern highlights the dilemma of no matter whether or not an fascination price couple people pay remains to be pertinent in right now’s market as the perfect reference cost for evaluating highest borrowing!

    Categories: House Market, Ray Boulger