Tag: desire

  • Desire charge rises cause issue for quarter of mortgage holders: LV= – Property finance loan Technique

    1 in 4 property finance loan holders are nervous in regards to the have an effect on of fascination quantity rises on residence finance loan repayments compared to 10% of the frequent public, an LV= survey reveals.

    A quarterly survey of 4,000 British isles adults highlights how the personal funds of Uk grown ups proceed to be affected by the superior expense of residing regardless of some indicators of development in purchaser sentiment.

    The survey signifies that the nation’s financial resilience has seen a sluggish however steady development.

    The Wealth and Wellbeing indices that observe latest funds and potential outlook exhibit a slight rise in client sentiment in comparison with a 12 months up to now, as Uk grownups ended up 5% extra more likely to take into account that their funds will increase within the subsequent just a few months.

    The index measuring value financial savings additionally noticed an increase, with a 3% enhance in pension value financial savings because of the reality March 2023.

    Other conclusions clearly present that 51% of renters are anxious in regards to the climbing worth ranges of working day-to-working day issues though 38% are frightened in regards to the rising prices of energy costs.

    LV= fundamental government David Hynam claims: “As a mutual, our Prosperity and Wellbeing exploration is crucial to us. It assists us to understand what’s impacting individuals throughout the United kingdom and informs the steering and suppliers on provide to our clients.”

    “Although our Prosperity and Wellbeing Study Programme demonstrates that fewer persons are financially struggling compared to 2023, fairly just a few are proceed to anxious about their funds and what the potential holds for them.”

    “Despite the nation step-by-step turning out to be much more fiscally resilient, our information exhibits that socialising shell out has remained regular as a number of individuals at this time are prioritising their everyday residing costs.”
  • The American Desire | Evergreen Residence Financial loans

    &#13
    &#13

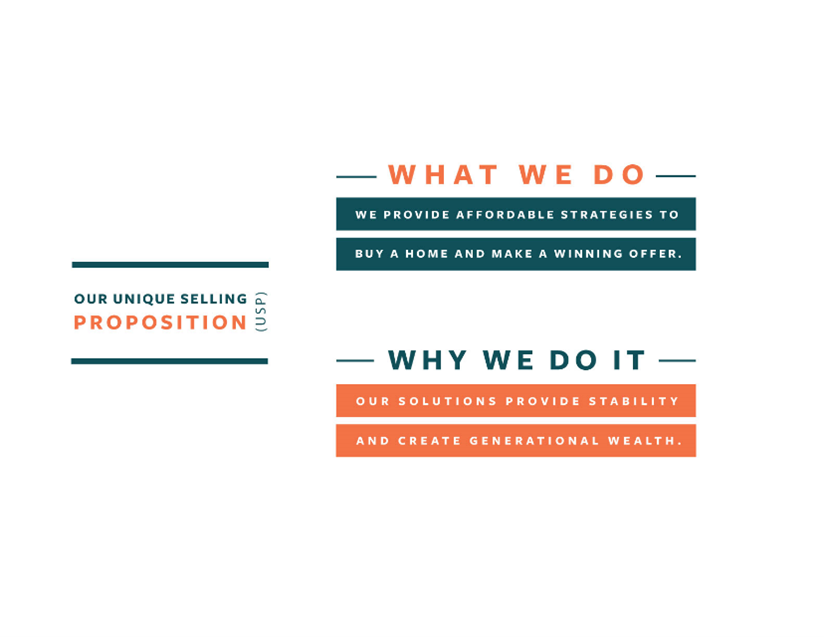
    At Evergreen Property Loans, we really feel within the electrical energy of homeownership as a important to carrying out the American Aspiration. Our mission is to ship very inexpensive methods to get a home and make a profitable give, given that we notice that proudly owning a residence is rather more than only a appreciable on a regular basis residing milestone – it may be a gateway to belonging, stability, and particular person flexibility.

    Why We Do It: Making Balance and Generational Prosperity

    Nicole Bachaud, Senior Economist at Zillow, underscores the enduring entice of homeownership: “The American Desire is nonetheless proudly owning a property. There’s a great deal of pent-up want for possession that’s not more likely to go absent.” We at Evergreen House Loans are devoted to turning this dream right into a actuality for our consumers, not simply as a place to reside however as a basis for extensive-term cash safety and generational prosperity growing.

    The Economical Benefits of Partnering with Evergreen Household Financial loans

    Our distinctive tactic amenities near creating homeownership obtainable and inexpensive. Jessica Lautz, Deputy Main and VP of Analysis on the National Association of Realtors (NAR), highlights the importance of homeownership in prosperity accumulation: “Homeownership is the amount 1 technique to set up prosperity in The us.” By deciding on Evergreen House Loans, you are not simply buying a residence you is likely to be investing in a future. Our tailored choices make it attainable to create fairness, maximize monetary safety, and established the stage for passing wealth to future generations.

    As Habitat for Humanity explains, “Overall, homeownership promotes prosperity setting up by performing as a pressured monetary financial savings mechanism and through family profit appreciation.” Our half is to guidebook you thru this course of, that includes custom-made home mortgage options that information to accruing fairness and bettering monetary independence.

    The Emotional and Social Benefits of Your Very personal Residence

    The constructive points of partnering with Evergreen Home Financial loans delay over and above the monetary. Proudly proudly owning a house delivers a notion of accomplishment, accountability, and a bunch of psychological and social advantages. In accordance to a Fannie Mae research, house owners cite management in extra of their dwelling home (94%), a notion of privateness and safety (91%), and supplying a nurturing pure atmosphere for his or her kin (90%) as main rewards.

    Making Your American Desire Arrive Legitimate with Us

    If you visualize a future loaded with independence, safety, and prosperity, Evergreen Home Financial loans is your ally. With favorable property finance mortgage costs and our dedication to inexpensive and efficient dwelling-purchasing methods, now could be a promising time to begin off your homeownership journey.

    As you embark on this route, take into account that the advantages delay past the bodily home. As Ksenia Potapov, Economist at 1st American, notes, “…homeownership continues to be an very important driver of prosperity accumulation and the key provide of entire prosperity amid most properties.” With Evergreen Household Loans, you aren’t simply getting a family you are growing a home for these days and a legacy for tomorrow.

    Picking out to purchase a property is a profound last resolution and a cornerstone of the American Desire. If you is likely to be looking out to discover a space to cellphone your very personal this calendar yr, let your dependable Evergreen Bank mortgage Officer tutorial you by the strategy. Make contact with us now to get began your journey towards homeownership.


    Resource: Retaining Current Matters


    &#13

  • Exactly where Are Home Personal loan Desire Premiums At the moment?

    Fed retains fees steady for the sixth straight time

    By Didier Malagies
    •
    02 Could, 2024

    The Federal Reserve ’s Federal Open up Markets Committee (FOMC) managed its short-term plan need fee continuous at a assortment of 5.25% to five.5% for a sixth consecutive convention on Wednesday. “The Committee doesn’t hope it is going to be correct to reduce the aim vary until it has obtained higher confidence that inflation is relocating sustainably towards 2%,“ the FOMC acknowledged in a press release. “In addition, the Committee will proceed on decreasing its holdings of Treasury securities and firm bank card debt and company mortgage‑backed securities.“ For the period of their previous convention in March , policymakers indicated that they nonetheless envisioned three curiosity degree cuts in 2024. But with inflation remaining sticky and unemployment remaining beneath 4%, these anticipations are turning into fewer in all probability. New monetary information hasn’t introduced the Fed self-worth that inflation will keep on to lower. Sturdy inflation data within the first quarter, coupled with a sturdy labor present market , have postponed expectations for the initially Fed charge decrease. In April, Fed Chairman Jerome Powell, talking on the Washington Forum , constructed it crystal clear that quantity cuts ended up not imminent as a result of energy of the general financial system. The monetary state has taken care of astonishing momentum irrespective of the present stage of shorter-phrase prices. With the unemployment quantity beneath 4%, companies are steadily including workers and true wage development is observable as inflation eases. Whilst upward actions in inflation are noteworthy, vital progress in direction of the Fed’s 2% goal has been made. “It’s not going that the longer term plan quantity switch can be a hike,” Powell knowledgeable journalists on Wednesday all by the FOMC’s press convention. “In buy to hike the charges, we’d might want to see persuasive proof that our coverage stance isn’t sufficiently restrictive to hold inflation sustainably right down to 2% over time. Which isn’t what we’re seeing on the minute.” While Powell emphasised the unlikelihood of future worth hikes, he additionally remained imprecise in regards to the Fed’s potential need quantity trajectory. “We didn’t see progress within the 1st quarter. It seems that it’s going to contemplate extra time for us to entry that stage of self-assurance,” Powell claimed. “I have no idea how intensive it should select. … My specific forecast is that we’ll start to see progress on inflation this yr. I have no idea that it is going to be adequate to chop costs we must enable the knowledge information us on that.” In a brand new progress, the Fed introduced an easing of its quantitative tightening coverage. Commencing in June, the charge-placing physique will decrease the roll-off cost of its Treasury securities from $60 billion to $25 billion for each month. This signifies that while the Fed is not going to begin off advertising Treasurys in June, it should enable for a lot much less of them to skilled. It is not going to change its roll-off cost for dwelling loan-backed securities (MBS), which can proceed being at $35 billion for every month, in accordance to Xander Snyder, senior industrial true property economist at Very first American. “The FOMC didn’t change the continued passive roll-off of its MBS holdings however did word that any prepayments additional than the persevering with $35 billion cap can be reinvested in Treasuries,” Mike Fratantoni, senior vp and chief economist for the Property finance loan Bankers Association, acknowledged in a assertion. “We count on dwelling finance loan costs to drop afterwards this yr, however not as a lot or as quickly as we beforehand skilled predicted.” In addition, Powell reiterated the Fed’s dedication to carrying ahead the Basel III endgame legal guidelines in a approach that’s dedicated to Basel and in addition similar to what the jurisdictions in different nations are performing. Considering the truth that the March FOMC meeting, Freddie Mac’s regular 30-12 months preset mortgage loan worth has amplified from 6.74% to 7.17%. Right earlier than the longer term FOMC meeting on June 12, two further inflation readings are envisioned. “While it’s a risk, I actually don’t assume that we’ll see considerably alter in dwelling finance loan prices adhering to this Fed assembly, primarily as a result of the Fed has been inclined to allow the data lead at this stage within the cycle,” Realtor.com chief economist Danielle Hale reported in a assertion. “In get to see mortgage loan premiums fall much more considerably, the Fed might want to must see much more proof that inflation is slowing.”  For homebuyers and sellers, this means that housing affordability will proceed being a number one factor to contemplate, fairly probably driving property purchases in very inexpensive markets, predominantly within the Midwest and South, based on Hale.

  • Why HELOC desire will surge

    Involving February 2020 and January 2022, we witnessed one thing within the dwelling finance mortgage subject that we thought-about we’d infrequently see — 30-year preset-rate dwelling loans beneath 3.5%. These costs drew a historical past quantity of individuals refinancing their properties, with money out refinances reaching $1.2 trillion in 2021.

    Then, in what felt like an prompt, in Q1 2022 mortgage charges skyrocketed and the refi increase ended. As individuals search for alternate signifies to accessibility the fairness of their households, residence equity strains of credit score rating (HELOCs) are poised to make a comeback. Here’s why:

    House house owners will even now wish to use the historical past ranges of fairness of their properties

    The residential true property enterprise faces an intriguing dynamic of mounting mortgage mortgage premiums though, on the comparable time, homeowners have report fairness of their properties. In accordance to CNBC, home-owner fairness is an combination $9.9 trillion. The common home proprietor has about $185,000 in equity they will entry although even now retaining a 20% stake of their residence. 

    Having out a HELOC is a viable chance for homeowners who wish to maintain their principal mortgage mortgage, and nonetheless faucet the fairness of their home. 

    A HELOC is now inexpensive than a refi

    Even although the fascination value on a HELOC at present is almost definitely higher than the extent on a major property finance mortgage, homeowners will attainable to return throughout that refinancing now not tends to make mathematical sense.

    Most households have a decrease quantity on their main dwelling finance mortgage, so executing a tough cash-out refi will generate a better month-to-month fee than sustaining the mortgage they at present have and together with a HELOC on main.

    For working example, if a property proprietor has a $400,000 home mortgage at 3.25% and needs to faucet an extra $100,000 of their fairness, they may have in mind accessing $100,000 of equity by the use of a HELOC vs . a tough cash-out refi:

    Income-out refi: Accessing $100,000 of equity would imply getting out a $500,000 home mortgage at at present’s fees, that are averaging in extra of 5%. This will cost $2,684 for each thirty day interval. HELOC: If, alternatively, a home-owner merely supplies a $100,000 HELOC at 5%, they’re looking out at month-to-month funds totaling $2,157. Even a 7% HELOC will solely worth $2,324 a thirty day interval. Also, the home proprietor is possible having to pay curiosity on lots lower than $100,000, contemplating that they solely pay desire on the sum of the HELOC that they’ve withdrawn. For event, if the property proprietor has solely withdrawn $50,000 of the HELOC for a renovation or downpayment on a brand new dwelling, the person or lady would solely be paying out fascination on the $50,000.

    HELOCs present flexibility 

    In the present-day business circumstances, under are a couple of of options of a HELOC dwelling house owners will receive most fascinating:

    Initially, HELOCs are arguably further adaptable than a typical income-out refi. At the time accepted for a HELOC, they will accessibility the road of credit score as wished, versus buying {dollars} sitting in a private financial savings financial institution from a refi. In cases the place the house proprietor finally ends up needing to get solely the minimal quantity important appeal to from a HELOC, they might solely conclusion up paying once more that ingredient of the mortgage. In distinction, once they do a income-out refi, they’re dedicated to paying out the brand new principal and curiosity steadiness for the interval of the mortgage — very seemingly 15 or 30 a few years. 

    Next, and actually a lot comparable, the common month-to-month payback quantities on HELOCs are extra adaptable. In the course of months the place you want added money to finance a property restore, or a transfer, they might nicely select to pay again the curiosity solely part of the non-public mortgage. 


    For the foreseeable long run, I foresee HELOCs remaining the fairness-access car of selection for plenty of U.S. property house owners. Much like 2021 was a doc calendar yr for refinancing, 2022 might be a file calendar yr for HELOCs.

    David Friedman is the CEO and co-founder of Knox Economical.

  • FHFA finalizes rule on honest lending, language desire

    The Federal Housing Finance Company on Monday formally moved forward with a plan to codify  calls for associated to good lending and most well-liked language use in regulation.

    The Honest Lending, Truthful Housing, and Equitable Housing Finance Strategies Last Rule initially proposed final yr goals to make it extra sturdy to roll once more actions supposed to steer rather more equitable get hold of to homeownership because of Freddie Mac and Fannie Mae, the influential quasi-community property finance mortgage patrons it oversees, and the Federal Household Bank mortgage Banks.

    Standard organizing geared toward closing the racial homeownership hole and language desire selection specs are notably necessary to keep up now given worth pressures within the market that would injury some communities disproportionately, FHFA Director Sandra Thompson acknowledged.

    “These initiatives are critically essential at a time when housing affordability stays a persistent impediment,” talked about Thompson in a press launch, citing an downside anticipated to be a vital determinant ultimately results of the federal election set for this fall.

    The Trump White Residence labored to roll once more quite a few good lending guidelines all by way of its tenure and the Biden administration subsequently produced an exertion to reinstate them, suggesting that the problem might re-emerge as a differentiator amongst the occasions within the hottest presidential race.

    Skilled groups within the dwelling mortgage subject have had blended reactions to the prerequisite for govt-similar entities the FHFA oversees to speak to about debtors’ favored methodology of communication and doc any counseling people obtain about their home purchases.

    The Community Dwelling Creditors of The usa has been supportive of the prerequisite prior to now. The Home finance mortgage Bankers Affiliation has been further calculated in its response, citing inquiries about whether or not there’s loads of neighborhood steering for compliance by the use of translation clearinghouses and different strategies.

    The Federal Housing Finance Agency additionally introduced the event of a brand new Division of Community Curiosity Assessment on Monday.

    The division can have “supervisory oversight of the company’s regulated entities within the locations of very reasonably priced housing, group improvement, vary and inclusion, purchaser safety, and truthful lending,” in keeping with the FHFA.

  • Mortgage desire picks up as seller concessions rise

    Bank mortgage officers observed an increase in property finance mortgage demand from prospects all through the to start out with 7 days of 2023 as mortgage charges ticked down. And to close bargains, sellers are an increasing number of coming to the desk with concessions and value buydowns. 

    “I’ve had 5 individuals at present pay money for me within the closing week or so to debate about shopping for a brand new property, which is a good deal higher than a thirty day interval or two in the past,” Rochelle Gano, a Vancouver, Washington-primarily primarily based private mortgage officer at Movement Home mortgage, instructed HousingWire. 

    “It looks as if, with each small fall in curiosity cost, the homebuyer’s fascination picks up a little or no bit. It seems to be just like the decline in premiums was about 5 basis elements from what I see on my price sheet.” 

    Gano’s ordeals replicate what occurred within the sector over-all.

    According to the Mortgage Bankers Association (MBA), mortgage functions rose 1.2% for the 7 days ending January 6, compared to the 7 days earlier than, when the 30-calendar yr prices for conforming loans ($647,200 or much less) went from 6.58% to six.42%. 

    Buy applications declined 1% week above week and 44% yr in extra of 12 months. In the meantime, refinancing elevated 5% from the previous 7 days and was 86% decreased than the exact same 7 days one yr again. Irrespective of the enhance, refis are about 30% of the complete purposes, correctly below the previous decade’s widespread of 58%, the details reveals.

    “Mortgage premiums declined previous 7 days as markets reacted to data displaying a weakening monetary state and slowing wage progress,” Joel Kan, MBA’s vp and deputy chief economist, defined in an announcement. 

    The Bureau of Labor Statistics reported on Friday that work and wage growth is slowing, although the labor market completed 2022 a lot better than anticipated. 

    Just after the labor market place particulars turned neighborhood, property finance mortgage charges fell aggressively to six.20%, inserting them at much more than 1% down under the highs of 2022, in response to Logan Mohtashami, the information analyst at HousingWire.

    “The bond business noticed that wage development was cooling down, leaving the Federal Reserve with variety of explanations to retain the quantity hike story doubtless significantly prolonged,” Mohtashami wrote.

    Concessions, home mortgage price buydowns protect offers 

    According to market watchers, sellers are attracting customers to their properties as a results of residence finance mortgage value buydowns. 

    According to a brand new Redfin report, a file 41.9% of home sellers gave concessions to homebuyers within the fourth quarter of 2022 by the use of {dollars} for repairs and mortgage-fee buydowns. 

    The proportion represents the utmost enhance contemplating the truth that July 2020, when Redfin began monitoring this particulars. In the third quarter of 2022 and the fourth quarter of 2021, sellers gave concessions in 30% of property income. 

    “In our current environment, the brief time period buydown is engaging given that we actually really feel that curiosity premiums will craze decreased over the approaching yr and the purchasers will need to refinance in 12 – 24 months,” Gano reported. 

    With a home mortgage degree buydown, the seller’s concessions are set in an escrow account, used each month to make up the excellence in fascination thanks involving the purchased-down curiosity quantity and the everlasting set curiosity value.

    Unused assets on the time the borrower refinances go in opposition to their monetary mortgage stability as a principal discount. “So, in essence, the seller aided spend for his or her refinance in 12 -24 months. It is a superior method for purchasers preferrred now,” Gano stated.


  • Really should I lock in my desire level

    The property finance mortgage cost pendulum swings however as soon as once more

    By Didier Malagies
    •
    18 Apr, 2024

    Hope 2024 to be mildly improved than 2023 with mortgage charges falling in the following 50 % of the yr, housing business consultants opined in their forecasts on the finish of the yr. Cuts to the Federal money value (and subsequently to accommodate mortgage costs) are imminent, merchants enthused instantly after December’s convention of the Federal Open up Current market Committee in which committee customers predicted a number of value cuts in 2024. Some authorities forecasted as a number of as six cost cuts in the yr depending on this information. Price cuts are even now coming, simply not in March , merchants and business authorities reasoned much more simply currently because the economic system continued to run very popular. And now on the heels of research of extra strong than anticipated employment development and stickier than predicted inflation , the market’s shift from optimism to pessimism round charge cuts is whole. Some even expect charge hikes previous to payment cuts. The pessimism is seen in property finance mortgage charges. Freddie Mac‘s weekly Primary House mortgage Industry Study is climbing again once more in the direction of 7%. HousingWire’s Mortgage Price Middle , which will depend on information from Polly, is already beforehand talked about 7.2%. Rates ended up as minimal as 6.91% for Polly and 6.64% for Freddie as currently as February. On Tuesday, they reached 7.50% on Home finance mortgage News Day by day, a excessive for this calendar yr. Home finance mortgage premiums maintain main electrical energy in the housing business most significantly, excessive costs exacerbate the current affordability disaster by walloping the acquiring electrical energy of would-be patrons and discouraging some would-be sellers – individuals with minimal, set-level mortgages – from itemizing their households, a drain on obtainable inventories. All this leaves housing gurus when another time combating for his or her share of shrinking pies – as we’ve seen with currently launched house finance mortgage information and RealTrends Verified’s brokerage particulars , as successfully as additional dives on the brokerage landscapes in Jacksonville and San Diego . It is unsurprising, then, that severe property shares have suffered because the FOMC’s March convention and the the most recent place and inflation research. That consists of the nation’s main homebuilders (DR Horton and Lennar), mortgage mortgage originators (United Wholesale House mortgage and Rocket Home finance mortgage), brokerages (Anyplace and Compass) and residential lookup portals (Zillow and CoStar, which owns Houses.com). There are different dynamics at interact in for a few of these suppliers, nonetheless. The brokerages are additionally contending with the rule modifications concerned in a proposed settlement by the Countrywide Affiliation of Realtors some patrons additionally really feel these rule changes profit CoStar on the value of Zillow . UWM, in the meantime, is contending with a scathing investigative report by a hedge-fund-affiliated information group whose hedge fund shorted UWM and went prolonged on Rocket it’s also coping with pending litigation . UWM denies the allegations manufactured in the report.  Higher house mortgage costs, a lot much less home mortgage packages and fewer dwelling product gross sales are regrettably not the one penalties housing specialists might see from a further prolonged high-level setting. There are additionally spillover outcomes from different industries, particularly administrative center actual property. Regional banking establishments – which historically have been large family house finance mortgage originators – went main on business actual property loans as higher monetary establishments scaled again in this place in new yrs. That enhanced their publicity to downtown administrative center towers, which have witnessed an exodus of tenants and a bottoming out of appraised values simply as a report $2.2 trillion in business genuine property monetary debt arrives due to in extra of the longer term variety of many years. That ties up cash that would if not transfer to family mortgages and in some cases stresses banking corporations like New York Local group Bank, dad or mum of Flagstar Lender — the Seventh-largest lender originator of family mortgages, Fifth-biggest sub-servicer of property finance mortgage monetary loans and the 2nd-greatest house finance mortgage warehouse monetary establishment in the nation. Homebuilders, too, actually really feel the results of extended increased costs. Whilst homebuilder self-assurance is nonetheless up drastically because of the reality final tumble, new housing begins off are slowing . The dim potential purchasers for homebuyers have turned some buyers to the nascent build-to-rent sector , successfully a wager that enormous charges are listed right here to proceed to be for very lengthy greater than sufficient that would-be clients are actually would-be renters.

  • House loan credit history scoring products see stakeholder desire mature

    Utilization of FICO’s 10T credit rating ranking product is getting extra momentum in 2024, with two distinct loan suppliers signing on to make use of it for a lot of functions prematurely of broader mandated adoption comes future calendar 12 months. 

    Ohio-dependent countrywide direct loan supplier Liberty House Home finance loan is probably the most up-to-date enterprise choosing the FICO 10T mannequin, asserting it might get began using it for nonconforming originations. Liberty joins fairly a number of different companies presently using 10T for nonconforming monetary loans, along with Movement House loan and Crosscountry. In the very first quarter of this calendar 12 months, Primis Financial establishment, Leading Lending and Cardinal Economical, equally, all agreed to start out out use of FICO 10T for specified sorts of originations.

    Introduced in 2020, the FICO mannequin was chosen alongside with Vantagescore 4. by the Federal Housing Finance Agency as simply one in every of two rating varieties loan corporations will ultimately require to consider when underwriting to make them eligible on the market to government-sponsored enterprises. The use of two new designs will change the FICO Typical rating, which has been a necessity for twenty years.

    Whole implementation of the FHFA plan is anticipated to occur by the shut of 2025, though some parts of the proposal are in all probability to seem faster. 

    Relatively than maintain out for mandated alterations to get there, a tiny variety of loan suppliers began functioning with the 10T mannequin as simply these days as remaining yr for nonconforming loans marketed to personal traders. In February, Cardinal Financial stated it might begin out looking at 10T scores particularly for Section of Veterans Affairs originations, that are additionally not marketed to Fannie Mae or Freddie Mac and won’t have a exact requirement for such a credit history metric like they do. Cardinal was the very first to announce it might use the mannequin for VA monetary loans.

    FICO guarantees the predictive investigation obtainable by 10T can enhance originations by as considerably as 5%, when minimizing default risk by as much as 17%.

    The addition of Liberty Residence House loan to the checklist of FICO 10T finish customers arrives per week simply after World Dwelling Lending additionally reported it might combine the mannequin in its recapture evaluation of its servicing portfolio, which has authorities-backed and normal house loans from its dispersed retail channel or correspondent division. 

    “We are eager to faucet the power of FICO Rating 10T to additional evaluation our book of enterprise and unlock new origination potentialities,” stated John Bosley, Planet Household Lending property finance loan president, in a push launch.  

    World Home’s use of 10T additionally particulars to the rising factor to think about of latest scores in broader contexts inside simply the house loan trade. In February, the Federal Dwelling Bank loan Financial establishment of San Francisco indicated it might get began accepting mortgage collateral from loan suppliers using Vantagescore 4..

    With probably the most newest additions, FICO 10-T is now in use in some options of the group at property finance loan companies with a put collectively cumulative origination quantity of much more than $100 billion, the information analytics utility supplier reported. These exact same companies firm just about $300 billion in mortgages.

  • Desire level movements – RateCity reveals the hottest

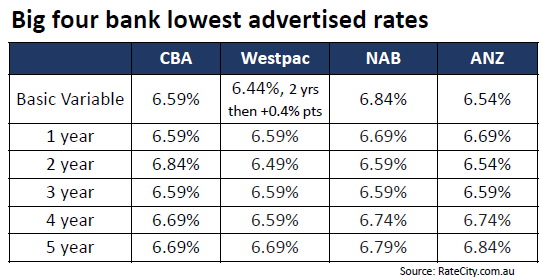
    “This alter was not so considerably a range by the monetary establishment to present big bargains to possible new clients taking out its bundle mortgage, however considerably a strategic choice to superior align its marketed costs with the expenses that patrons shut up getting,” Tindall reported.

    “For a very long time, monetary establishments – the important banking corporations, in sure – have utilized a strategy whereby they promote unrealistically substantial promoting costs on their bundle dwelling monetary loans which then will enable them to offer clients sizeable individualised ‘reductions’ from this worth. NAB’s shift follows a associated resolution by CBA to drop its bundle home mortgage cost costs in November 2022, leaving each of these Westpac and ANZ with inflated larger charges.”

    Other mortgage suppliers additionally modified their expenses, although Tindall well-known a significant slowdown in fee variations amongst the the extra than 115 collectors listed on the RateCity.com.au database.

    Auswide Financial establishment decreased its charges for operator-occupier, variable, and principal and curiosity monetary loans with LVRs involving 90% and 95% by .45 proportion particulars, bringing the worth down to six.89%. Equally, Queensland Country Bank decrease its a single-year mounted worth for owner-occupiers with an LVR beneath 80% by .30 proportion components to six.19%.

  • Weekly home loan demand drops as desire prices increase once again

    Weekly mortgage demand drops as interest rates rise again

    Home loan desire fees rose earlier week for the preliminary time in 3 weeks. As a consequence, total mortgage loan software quantity dropped 1.6% in distinction with the sooner 7 days, in line with the Mortgage loan Bankers Association’s seasonally adjusted index.

    The abnormal contract desire value for 30-12 months mounted-price home loans with conforming financial institution loan balances ($766,550 or much less) elevated to six.97% from 6.84%, with components lowering to .64 from .65 (which embody the origination price) for loans with a 20% down fee. That was the weekly frequent, however an extra index from Home finance loan Information Every day, which appears to be at day-to-day premiums, skilled the 30-yr fastened property finance loan transferring again about 7% earlier Thursday.

    “Home loan prices larger ultimate week as incoming details confirmed inflation was proceed to hotter than envisioned, which stoked points concerning the timing and extent to which the Fed could effectively be capable of reduce the fed money fees this yr,” talked about Joel Kan, MBA’s vice chairman and deputy chief economist.

    Much more CNBC info on housing

    Programs to refinance a dwelling financial institution loan, that are most delicate to weekly value adjustments, fell 3% as compared with the earlier 7 days and had been additionally 3% lowered than the similar week one explicit 12 months up to now.

    Purposes for a home loan to acquire a family fell 1% for the week and ended up 14% decreased than the precise 7 days only one calendar yr up to now. Invest in desire is just not as delicate to tiny strikes in fascination charges. Desire can also be arising in direction of substantial fees and fairly restricted present.

    “With housing provide lowered and prices superior, the everyday loan dimensions for purchase packages elevated to the best stage as a result of May 2022,” Kan additional.

    Costs are actually within the lowered 7% vary, simply shy of the 2024 ceiling hit three months again. That ceiling may both proceed being in location or be damaged Wednesday with the most recent Federal Reserve announcement on curiosity prices and the following push conference with Fed Chair Jerome Powell.

    “The market is presently anticipating a bit little bit of an unfriendly change this time throughout, however the actuality may conveniently differ from expectations. To no matter extent it does, home loan charges are more likely to make bigger strikes, for improved or worse,” wrote Matthew Graham, chief working officer of Home loan Information Everyday.

    Do not skip these exclusives from CNBC Pro