Tag: day

  • Mortgage Rates Shrug Off Seemingly Threatening Inflation Details to strike 5 Thirty day period Lows

    &#13

    Home mortgage Fees Shrug Off Seemingly Threatening Inflation Information to strike 5 Thirty day period Lows

    &#13

    (*5*) was all concerning the Shopper Price tag Index (CPI), which aided property finance mortgage expenses fall on the 2nd quickest pace of the 12 months.  Right now brough the PRODUCER Rate Index (PPI), and the message was a bit numerous.

    When PPI isn’t within the actual league as CPI in circumstances of its impression on charges, there have been a number of present examples which have left a mark available on the market, for much higher and even worse.  When this morning’s installment arrived out, it appeared like we would have an extra illustration to depend, and never the wonderful type.

    Involving the brand new headline and the revision to closing month’s portions, yearly PPI ended up a 50 p.c a per cent higher than the market predicted. If that type of factor transpired in CPI, premiums would positively skyrocket. Even whereas it was a PPI problem, it nevertheless wouldn’t have been a shock to see at minimal SOME upward pressure presently.

    But as an alternative, costs managed to switch Reduced, albeit not by considerably.  Nevertheless… any enchancment within the wake of those numbers requires an clarification.  In this situation, it got here down to the underlying components of the PPI particulars not translating to the consumer-experiencing inflation metrics that guideline fee protection.  

    In different textual content, typically larger PPI signifies upward pressure on the PCE inflation data (the broadest countrywide consider of purchaser inflation and essentially the most intently-viewed by the Fed), however trendy report didn’t.  Bonds to start with panicked for a break up subsequent, however then eased into modestly a lot better territory and stayed there all day with none drama.

    The regular lender was ready to drop charges by only a hair, however even when victory ended up constrained to preserving yesterday’s victory, that might be victory adequate. 

  • Real estate stocks soar to best day of the year on rate cut bets

    The inventory market’s worst group is having its best day of the year as a cooler-than-expected inflation report stokes bets that the Federal Reserve will begin chopping rates of interest in September.

    Shares of actual estate firms jumped as a lot as 3.1% Thursday for his or her largest intraday acquire of 2024, climbing to their highest stage since March as buyers snap up homebuilder, digital and business actual estate stocks alike. Real estate is also the best-performing group in the S&P 500 Index Thursday, with quantity that is round 65% greater than the 30-day common, in accordance to information compiled by Bloomberg. 

    Arguably the most important information to come from the newest shopper worth index studying was a pullback in housing-related inflation. Shelter prices rose simply 0.2% for the slowest month-to-month enhance in three years. Homebuilders, which have risen 6% this year, are up practically 7% for the session. Shares of D.R. Horton Inc., which is scheduled to report earnings subsequent Thursday, gained as a lot as 7.4%. 

    “Housing has actually been the final shoe to drop in phrases of profitable the battle towards excessive inflation,” Preston Caldwell, chief U.S. economist at Morningstar wrote in a observe to purchasers Thursday. “Leading-edge information has strongly indicated for a while now {that a} fall in housing inflation was in the works.”

    A rally in actual estate stocks is unhealthy information for brief sellers who’ve been piling into the group, which is the worst performer in the S&P 500 this year. To begin the week, quick curiosity as a proportion of float hovered close to 49% in the SPDR Homebuilders ETF, the highest stage since February for the exchange-traded fund, in accordance to information from S3 Partners.

    Property house owners are rallying as nicely. Real estate funding trusts, which have been brutally penalized throughout the two-year run up in borrowing prices, superior by as a lot as 3%. The outlook for the group seems to have turned a nook, in accordance Rich Hill, senior vice chairman and head of actual estate technique and analysis at Cohen & Steers Capital Management.

    “We assume this can be a compelling backdrop for listed REITs particularly as elementary development stays on stable footing,” he mentioned, referencing the newest inflation information and rate outlook. “The rally that began in October of 2023 pushing returns greater than 20% above their trough seems set to proceed if inflation cools and rates of interest proceed to decline.” 

    Shares of industrial REIT Prologis Inc., which experiences second-quarter outcomes on Tuesday, rose as a lot as 3.6% to hit their highest intraday stage since April. U.S. Treasury yields tumbled, with the 10-year bond falling beneath 4.2% and the policy-sensitive two-year observe slipping to 4.5%.

  • Decide delays helpful day of noncompete ban

    A federal determine delayed the efficient day of the Federal Trade Commission’s within the neighborhood of-full ban on noncompete agreements, the primary salvo within the superior-stakes authorized struggle greater than how loads freedom staff should have to alter jobs inside of an area.

    U.S. District Choose Ada Brown in Dallas sided with the U.S. Chamber of Commerce and a Texas-primarily primarily based tax agency that claimed in a lawsuit the corporate lacks authority to plan procedures defining unfair methods of competitiveness. The teams warned the unparalleled rule would invalidate 30 million employment contracts in a switch that “portions to an enormous overhaul of the countrywide monetary system.”

    The ban was set to decide on impact nationally Sept. 4. It will now be on maintain till August for the groups that discover to fully strike the rule from the textbooks, although the select considers the deserves of their match.

    Brown reported in her ruling Wednesday that the problem to the measure is “most likely to thrive on the deserves,” and that the neighborhood curiosity weighed in favor of briefly blocking the rule.

    The FTC accredited the brand new rule in April, arguing that noncompete agreements unfairly block personnel from switching work and undermine labor opposition. The ban is backed by labor organizations AFL-CIO and the Company Workers Worldwide Union, Democratic senators and legal professionals regular from California, Illinois and 17 different states.

    “The FTC stands by our obvious authority, supported by statute and precedent, to issue this rule,” Douglas Farrar, a spokesperson for the corporate, reported in an announcement. “We will keep combating to no value hardworking Us residents from illegal noncompetes, which reduce innovation, inhibit monetary growth, entice personnel, and undermine Americans’ financial liberty.”

    Read Much more: Rule for a day: FTC noncompete ban strike with rapid lawsuitWill New York’s possible non-compete ban press advisory firms out of the purpose out?The deets on noncompetes: Advisors conflict with company house owners and commerce groups on deal clausesCan advisors anticipate considerably from ban on non-competes? In all likelihood notWells Fargo hit with nonsolicit lawsuit about $5M in client accounts

    The rule would ban most noncompete agreements, corresponding to people of senior executives. Current agreements for executives who generate excess of $151,164 a yr in a “protection creating scenario” would proceed to be in place beneath the FTC’s ban, though people binding lower-amount personnel would grow to be unenforceable.

    Business groups argue the FTC’s rule is extraordinarily broad and limitations the means of suppliers to protect confidential info. The ban would have an effect on corporations and people throughout the workforce — anybody from medical medical doctors to tax specialists to hair stylists — and alter the stability of means amongst bosses and staff.

    “This ruling is a big acquire within the Chamber’s fight versus govt micromanagement of group conclusions,” the Chamber of Commerce’s primary counsel Daryl Joseffer claimed in an announcement. “The FTC’s blanket ban on noncompetes is an illegal energy seize that defies the company’s constitutional and statutory authority and units a unsafe precedent the place the governing administration is aware of significantly better than the marketplaces.”

    About an individual in 5 Individuals is bound by a noncompete association, a March 2022 Treasury Office report discovered. In some industries, together with applied sciences and well being remedy, it is even greater. Reports discovered as fairly just a few as 45% of main remedy medical professionals and 35% to 45% of tech employees are certain by noncompete clauses.

    As noncompete agreements have fallen out of favor in a quantity of states, loads of corporations hit by rivals with experience raids have fought again with lawsuits, alleging that former workforce took proprietary details after they defected. 

    President Joe Biden helps the FTC ban and his administration has constructed opposition troubles a essential half of his monetary plan.

    Brown’s remaining determination may very well be appealed to the conservative fifth Circuit Court of Appeals in New Orleans. The appeals courtroom has transform a most liked for conservative opponents of Biden’s insurance coverage insurance policies associated to federal regulatory energy, weapons, abortion and social media regulation.

  • Working day in the Lifestyle of… Kevin Davis, head of lending, Suffolk Developing Society – Home loan System

    Kevin DavisIllustration by Dan Murrell

    My alarm goes off at…

    …6am, regardless of the incontrovertible fact that my alarm clock is usually in the kind of 1 of my youthful babies, waking me up with some morning electrical energy ranges that mine actually do not match until I’ve had a espresso or two.

    At the time the younger ones are prepared for nursery, I prefer to get logged in an hour or so simply earlier than the crew. That approach, I can get forward with planning workloads for the workers and dealing with any queries which have arrive in in a single day.

    I required to work in the property finance loan enterprise as a result of…

    …I prefer to assist of us. Getting a house is a single of the largest commitments somebody will make in their on a regular basis dwelling, so to carry out slightly part in that severely intrigued me.

    Saying ‘Yes’ to a circumstance is probably going the best side of my profession

    Somewhat one thing that shocked me about my profession was…

    …how I see something various each day.

    I’m lucky in my perform that I’ve sight of heaps of functions and enquiries each day, and no prospects’ scenario are the exact same. Whether it’s a definite income set-up, a unusual belongings sort or the rest, it completely retains me on my toes.

    To coin a well-applied phrase, each single working day truly is a college day in this enterprise.

    A false impression about my half is…

    …that we prefer to say ‘No’. This couldn’t be even farther from the fact of the matter as I get considerably much more achievement from stating ‘Yes’ to a scenario. In reality, which is sort of definitely the greatest ingredient of my occupation.

    To see the contributions that I’ve constructed to lending standards enhancements, merchandise and procedures happen to way of life and hit the trade is a genuinely rewarding sensible expertise

    I like searching at a scenario that has some points and may not tick all the established containers however the place, in the finish, the chance is inside our urge for meals. Discovering a reply to assist that shopper attain their goal is extraordinarily worthwhile.

    That is why ‘Look to lend’ is a mantra we have now instilled in the course of our underwriting workforce.

    My common day entails…

    …I’m lucky that my working day may be very diverse.

    Usually, I begin by convention with senior customers of the lending workers to system the day’s do the job. We then transfer on to critique and concentrate on with our small enterprise improvement workers any new enquiries that want information underwriting. I additionally consider any case referrals from the underwriters and indication the delivers inside my lending mandate.

    ‘Look to lend’ is a mantra we’ve instilled throughout our underwriting group

    As correctly as sustaining day-to-working day enterprise shifting ahead, I agenda in time to create our extended-expression objectives. These contain course of changes to make us easier to do firm with, new lending protection concepts and constructing our applied sciences.

    A perk of the profession is…

    …being outfitted to make a genuine impression. To see the contributions that I’ve created to lending standards adjustments, merchandise and processes come to lifetime and hit the market is a truly rewarding experience.

    My favorite function reminiscence is…

    …the 1st time I skilled a situations modify plan that was taken forward and set live.

    I used to be a junior member of the crew at the time, so viewing the have an effect on I might have at the fashionable society truly impressed me.

    I like looking out at a case that has some issues and couldn’t tick all the set containers however the place by, finally, the risk is inside our urge for meals

    To unwind quickly after perform, I…

    …spend time with the relations, when additionally proudly owning only one eye on any soccer or cricket occurring at the time.

    I’m an enormous Ipswich Town soccer supporter, so I’m at current having fun with our second in the sunshine following many a number of years of darkness!

    This write-up featured in the June 2024 version of Home loan Tactic.

    If you want to subscribe to the each month print or digital journal, you need to click on right here.

  • Mortgage loan Fees In close proximity to Maximum Ranges in Much more Than a Thirty day period

    Home loan prices ongoing their annoying and significantly perplexing go higher right now, due to this fact bringing the frequent loan supplier close to to the best ranges as a result of the close of Might. 

    Soaring charges are normally discouraging for people the housing/residence finance loan markets and potential debtors, however an ebb and motion is a lifestyle.  In different phrases and phrases, it may be fantastically typical to see excellent and undesirable days for charges.

    Considerably much less strange is the occasional emergence of counterintuitive payment motion.  In different phrases, we’re ordinarily in a place to tie any given fall or surge in premiums to a particular person or a lot more root leads to which have skilled comparable impacts in the previous.  

    This time throughout, nonetheless, the financial knowledge has been suggesting DOWNWARD stress on prices above the earlier two instances.  Which is noteworthy for 2 causes: monetary info has been a trusted supply of steering and, a lot more importantly, expenses have expert something however downward stress concerning the previous two days!

    There are a couple strategies to account for the paradox, however at this place, most conversations incorporate some hypothesis concerning the political impact on expenses following previous week’s presidential debate.  Connecting the dots from all these conclusions to the sector movement is a pretty refined job and it depends on many assumptions that can not be predicted with a substantial diploma of certainty.  As such, we’ll dig deeper in the occasion the narrative proceeds inflicting challenges for costs.  For now, simply learn that it could probably be a supply of counterintuitive stress, however a single that ought to proceed to be trumped by the important thing future financial tales.

  • Consumers’ pessimism eases a bit this thirty day period – new report

    Consumers’ pessimism eases a bit this thirty day period – new report | Australian Broker Information

    SME

    Consumers’ pessimism eases a bit this thirty day period – new report

    Economist described some components affecting customers’ ideas concerning the general financial system

    Consumers' pessimism eases a bit this month – new report

    SME

    By
    Noel Gross gross sales Barcelona

    The new Westpac–Melbourne Institute Client Sentiment Index report reveals that there was minimal development in customers’ sentiments towards the financial system, because it rose to 1.8% this June, or 83.6 proportion particulars (ppts) when in comparison with final month’s 82.2 ppts.

    “Despite the enhancement, shopper sentiment stays down under its March stage and nonetheless firmly in deeply pessimistic territory,” claimed Westpac senior economist Matthew Hassan (pictured beforehand talked about). Client sentiment statistically steps the final effectively being of a nation’s financial system primarily based on customers’ viewpoints.

    Hassan defined that, at 83.6, the Index stays successfully under” the “impartial” stage of 100, that means pessimists outnumber optimists by roughly 20ppts.

    “The research component implies positives from fiscal steering measures are remaining negated by elevated worries about inflation and the outlook for curiosity costs,” Hassan claimed.

    The economist additionally mentioned that the new buyer sentiment index exhibits that data tales concerning the financial system have a deep results on customers’ perceptions referring to current Australia’s financial circumstance.

    “Two topic areas stood out in June: ‘funds and tax’ and ‘inflation’, with practically 50 % of [the] customers recalling data on every particular person of those,” Hassan mentioned. “On the previous, the knowledge was seen as considerably much less unfavourable than in March, reflecting the very well-received Commonwealth funds, the value-of-dwelling actions despatched by each of these Federal and state governments, and the section 3 tax cuts set to start on July 1. Even so, the knowledge on inflation was seen as a lot much less beneficial than in March, with assessments retracing a lot of the method once more to the quantities observed in December, when the RBA skilled simply raised the {dollars} cost in response to persistently increased inflation.”

    Hassan talked about the headline Client Sentiment Index is a composite and a mixture of 5 sub-indexes which might be based totally on responses to 5 exact issues. He defined these sub-indexes stage to a mix of pressures impacting consumers, improved assessments of relations funds, and purchaser sentiment offset by renewed issues concerning the financial outlook.

    “The ‘household funds vs a calendar yr in the past’ sub-index recorded a particularly highly effective 9.7% carry in June. Nevertheless, at 69.3 it stays at a extremely weak, deeply damaging stage. This sub-index would might want to rise by one more 20% simply to reach at its extended-run frequent stage, and by above 40% to get again to the ‘impartial’ diploma of 100,” Hassan acknowledged.

    “Similarly, the ‘time to acquire a key merchandise’ sub-index additionally recorded a steady 4.2% rise however remained at a very weak quantity of 79.7, effectively beneath its long-run frequent of 124.”

    Hassan reported that when pressures on partner and youngsters funds and shopping for potential are setting as much as simplicity, there’s a require for larger, double-digit positive aspects within the mentioned sub-indexes previous to we may begin off to say that these issues have convincingly subsided.

    Relevant Stories

    Hold up with probably the most up-to-date data and conditions

    Join our mailing guidelines, it’s completely free!

  • Home loan Rates Continue to be Exceptionally Flat for 4th Straight Working day

    Most mortgage loan lenders supply home loan prices in increments of .125% (i.e. 6.875, 7., 7.125, 7.25, etcetera.).  As these sorts of, a particularly noteworthy day of mortgage loan value movement is 1 wherein we see close to to a .125% rework.  Just in spite of everything, that’s what it will get for the conventional borrower to see a significant rework within the prevailing quantity quote.

    This is not going to imply lesser strikes by no means injury, solely that they’re seemingly to impact implications for upfront bills alternatively than the quoted value by itself.  Particularly, previous Monday, when charges jumped from 6.99% to 7.04%, the unusual borrower would be quoted a quantity of seven.00% in each of these instances, however on the 7.04% day, closing expenditures would have been larger, all different objects staying equal. 

    With all the earlier talked about in thoughts, at any time contemplating the truth that final Monday, the common high tier typical 30yr set value has not moved mover than .02% on any solitary working day and for the earlier 3 occasions, no more than .01%.  That is a staggering diploma of “sideways-ness.” 

    It hasn’t been for an absence of alternative motivations each.  During that point, many financial tales have been launched which have managed to induce considerably extra substantial reactions within the earlier.  If they did not this time, it’s actually for the rationale that the sector is eagerly ready round for affirmation (or lack thereof) that essentially the most new spherical of inflation information is signaling a shift that enables costs to proceed transferring reduce.  

    That data solely will come out each single so usually, and solely when a month within the circumstance of essentially the most essential inflation report: the consumer price index (CPI).  We’re proceed to fairly just a few weeks absent from that only one, however among the different information is up to the job of main to some volatility between every now and then.  The solely seize is that virtually all of it arrives up coming 7 days.

  • Existing-residence income slide a 3rd thirty day period as prices established a file

    Revenue of current homes within the U.S. fell for a third straight thirty day period in May maybe although prices established a totally different historical past, underscoring persistent affordability worries that hobbled the very important spring advertising season.

    Agreement closings lessened .7% from a thirty day period earlier to a 4.11 million annualized charge, pushed totally by a drop within the South, in accordance to Countrywide Association of Realtors info launched Friday. The decide was in step with the median estimate in a Bloomberg examine of economists. 

    Meantime, the inventory of current households on the market has crept up a brief whereas in the past, partly as a result of women and men who’ve been ready for fees to drop earlier than itemizing their homes have decided they can’t wait round any for a longer time.

    The present of properties on the sector enhanced 18.5% from the very same month final 12 months to 1.28 million, however it may be nonetheless completely beneath the stage considered forward of the pandemic when dwelling finance mortgage prices had been a nice deal decrease.

    That explains why fees keep elevated — the median income promoting value higher 5.8% from a calendar 12 months previously to a historical past $419,300, reflecting additional product gross sales of large-priced properties as completely as many options, NAR’s info show.

    “Residence charges reaching new highs are producing a wider divide regarding all these proudly proudly owning attributes and people individuals who want to be initial-time clients,” NAR Chief Economist Lawrence Yun said in a assertion. “Finally, extra inventory will assist enhance dwelling income and tame dwelling price ticket good points sooner or later months.”

    Home finance mortgage prices have come down considerably not way back, however the Federal Reserve very probably won’t ever decrease fascination prices till later this 12 months. Yun claimed that could be delaying the restoration in residence gross sales, which have been trapped about a 4 million annualized charge for the previous 12 months.

    At the present tempo, selling all households on the sector would simply take 3.7 months, the most effective in 4 years. Even so, brokers see almost something under 5 months as indicative of a restricted present market.

    About 67% of the households offered ended up on the trade for a lot lower than a thirty day period in Might, roughly flat from the prior thirty day period, whereas 30% offered earlier talked about the guidelines charge. Properties remained on {the marketplace} for twenty-four occasions on typical in May properly, in distinction with 26 days in April, NAR’s report talked about.

    Current-dwelling earnings account for the higher a part of the U.S. full and are calculated when a contract closes. The federal authorities releases May presumably new-dwelling income figures on June 26.

  • Senate Banking Committee sets day for FDIC nomination listening to

    Sherrod Brown Jon Tester Senator Jon Tester, D-Mont., talks to Senate Banking Committee chair Sherrod Brown, D-Ohio, in 2022. The Senate Banking Committee has scheduled a affirmation listening to for Christy Goldsmith Romero — now serving as a member of the Commodity Futures Buying and promoting Commission — to chair the Federal Deposit Insurance Corp., however her best affirmation will rely on unified assist from common Democrats like Tester and progressive varieties like Brown.
    Bloomberg News


    WASHINGTON — The Senate Banking Committee will take into account the nomination of Christy Goldsmith Romero to chair the Federal Deposit Insurance protection Corp. on July 11, the panel declared. 

    Goldsmith Romero, who in the mean time sits on the board of the Commodity Futures Trading Commission, was simply currently launched because the Biden administration’s resolve on to direct the FDIC within the wake of a workplace misbehavior scandal on the company. 

    The committee, within the actual listening to, can even take into consideration the nominations of Caroline Crenshaw to be a member of the Securities and Trade Fee, Kristin Johnson to be assistant secretary of financial establishments on the Treasury Division and Gordon Ito to be a member of the Money Steadiness Oversight Council with skills in protection. 

    The Senate Banking Committee listening to marks the primary formal transfer within the course of to confirming Goldsmith Romero’s nomination — a race in opposition to the clock at this level with a restricted variety of legislative days left in Congress. Goldsmith Romero would swap present-day FDIC Chairman Martin Gruenberg, who launched he would resign on the affirmation of a successor. 

    Should the nominations cross the Senate Banking Committee, they are going to go to the whole Senate.


    Though Goldsmith Romero hasn’t activated any pushback a lot from Republicans, the affirmation of her nomination is proceed to significantly from confirmed. 

    Democrats have sufficient votes to usher her and the opposite nominations on account of the Senate, however provided that they proceed being united of their assist — together with amid these trying for reelection in prone seats within the 2024 elections. Republicans have been unusually efficient in sinking the nominations of the Biden administration’s cash regulatory nominees within the earlier, pulling Democratic assist, for illustration, from picks like Sarah Bloom Raskin and Saule Omarova. 

    Really ought to she make it by the use of the affirmation process, Goldsmith Romero would inherit an FDIC that not solely is nonetheless reeling from the neighborhood revelation concerning the company’s tradition, however that has a busy regulatory schedule. 

    On Thursday — in what might very very properly be Gruenberg’s ultimate board assembly as chairman —  the corporate finalized a rule bolstering decision choices for huge regional banking firms. Other crucial rulemakings, just like the Basel III endgame proposal, are nonetheless pending. 

    Goldsmith Romero maybe would have solely a restricted vary of months with a Democratic board. Need to Donald Trump purchase the presidential election, Goldsmith Romero wouldn’t essentially have to motion down as chairman, however could be up versus a 3-2 partisan break up that might make governing the company sophisticated.

  • Housing Marketplace in Present day Economic system

    &#13
    &#13

    Issues a few attainable recession have been a sizzling topic these days. Lots of hysteria {that a} recession may result in higher unemployment and, subsequently, a surge in foreclosures paying homage to the circumstance 15 a number of years in the past. Having mentioned that, insights from Evergreen Dwelling Financial loans, backed by details from famend assets just like the Wall Avenue Journal’s Economic Forecasting Survey, paint a singular {photograph}.

    The newest survey conclusions current a shift in economists’ views. Much lower than fifty p.c (48%) now predict a recession in the forthcoming 12 months, marking a noteworthy reduce from previous forecasts. This enhance in sentiment suggests a creating optimism in regards to the U.S. economic system’s resilience.

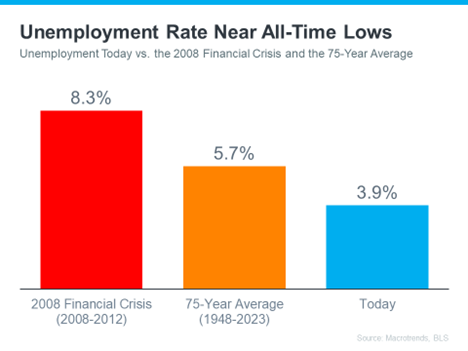
    Whilst the danger of activity losses can’t be totally dismissed, and any discount is important for individuals , the broader monetary context suggests a safe housing present market. Historic details from Macrotrends and the Bureau of Labor Statistics (BLS) expose that the present-day unemployment stage continues to be near all-time lows, properly below the common contemplating that 1948 (5.7%) and appreciably lowered than the height all by way of the 2008 financial disaster (8.3%).

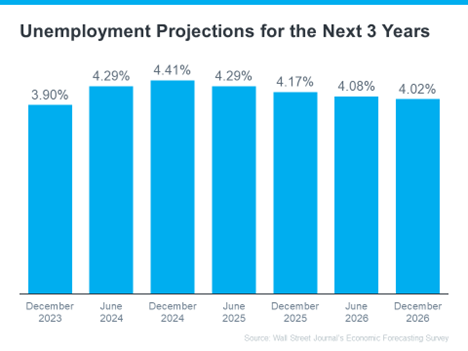
    Looking in advance, projections recommend that the unemployment value will possible keep below the 75-calendar yr common. This circumstance lowers the possibility of a foreclosures wave that would destabilize the housing market place.

    The Evergreen Viewpoint

    At Evergreen Property Financial loans, we intently monitor these monetary indicators to give you with essentially the most correct and helpful insights. Most economists are shifting away from predicting an fast recession and don’t foresee a dramatic improve in unemployment resulting in a housing trade crash.

    Our dedication is to retain you educated and warranted in your housing alternatives. If you could be involved about how unemployment may affect the housing trade and your family mortgage options, Evergreen Home Loans is true right here to help. Hook up along with your neighborhood Evergreen mortgage firm to get your homebuying journey began out.

    &#13