Tag: cuts

  • Fee cuts seem more not likely after latest Fed conference

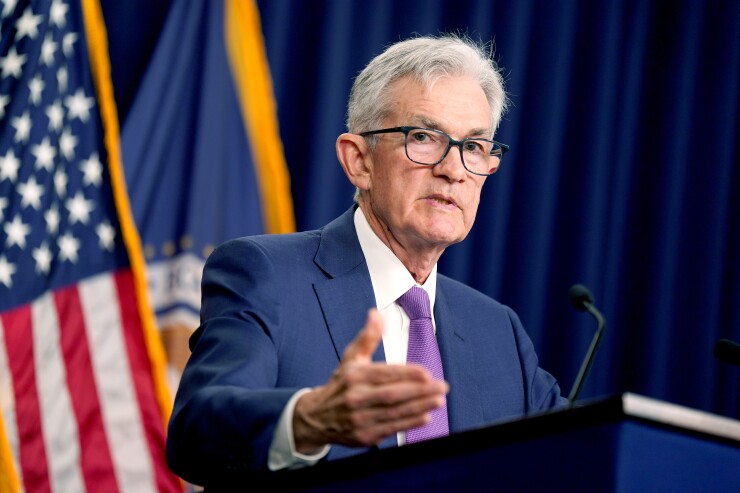
    JeromePowell2024.jpeg Jerome Powell, chairman of the US Federal Reserve, via a info conference following a Federal Open up Industry Committee (FOMC) conference in Washington, DC, US, on Wednesday, May presumably 1, 2024. The Federal Reserve signaled clear worries about inflation because it reaffirmed it needs more proof that promoting value positive factors are cooling previous to reducing curiosity charges from a two-ten years massive. Photographer: Al Drago/Bloomberg

    Al Drago/Bloomberg

    The Federal Open up Current market Committee nonetheless left need charges unchanged subsequent its latest assembly, high to queries about when a hoped-for decrease might arrive. 

    After 11 straight conferences in 2022 and 2023 the place central lender governors raised the federal money fee amongst 25 and 75 basis particulars, the FOMC has held benchmark ranges at 5.25% to five.50% since previous July. 

    While the FOMC’s assertion largely recurring verbatim a lot of what was revealed previously, the central lender included the road, “In the latest months, there was an absence of additional progress in the direction of the committee’s 2% inflation goal.”

    Federal Reserve Chair Jerome Powell echoed the remark in his article-meeting push conference, expressing “Further improvement in bringing it down is not sure, and the trail ahead is unsure.” 

    The Fed has constantly targeted an inflation stage of two% as the suitable mark to start cuts, however costs failed to reply in type across the remaining a couple of months, diminishing the prospect of any enhance to the draw back this calendar yr. March knowledge confirmed charges rising 3.5% 12 months about calendar yr. Some analysts and scientists are actually suggesting the initially charge lower could properly not be within the offing proper till 2025. 

    “Immediately after the inflation figures we skilled, it’s actually likely to be difficult for them to alleviate proper now, in June or July,” reported Arthur Bass, managing director at Wedbush. “They’re likely to might want to see some much better inflation numbers.”

    Concurring was Marie Applegate, vice chairman of money markets at Mortgage mortgage Center, who sees inflation removed from approaching the two% mark this yr primarily based totally on current business fundamentals. 

    “Just barring any surprising geopolitical gatherings, that are an actual probability, or somewhat one thing that might ship us right into a recession, I simply would not foresee the charges likely down now,” she said.

    The latest developments sprint hopes that traders held late final yr for as numerous as six value cuts this 12 months instantly after late 2023 portions confirmed indicators of a slowing financial system. But all these forecasts could properly have been a case of marketplaces leaping the gun, analysts mentioned. 

    “You would take note of the Fed talk about, and they might say we’re not budging until inflation goes down.” Applegate talked about. “Alright, properly, when is inflation likely to go down?”

    Though some business indicators, which embrace the Chicago Mercantile Exchange’s Fedwatch instrument, are nonetheless pointing to the doable for an individual fee decrease late within the yr, additionally they diminished earlier anticipations. 

    Fed governor remarks in present months additionally suggest some are utterly able to maintain the present money value as prolonged as required. “I really feel you actually should take heed to what the governors are stating, what the chairman is saying, and it looks as if they’re not going anyplace,” Applegate reported.

    Even with inflation even now jogging hotter than a number of predicted, Powell expressed self worth that latest plan could be “sufficiently restrictive” to inevitably strike 2%, pointing to the labor market place tendencies. 

    “Need is even now potent, the necessity side of the labor market in sure, however it may be cooled from its very important diploma of some a very long time in the past, and also you see that in place openings,” Powell talked about. 

    His remarks signify minor risk for a remodel to the two% aim, including physique weight behind his former statements. “There is been a complete lot of converse in posts and responses and ideas: Will they transfer their 2%? Powell pooh-poohed the vibes. I really feel that could be a nonevent,” Bass mentioned. 

    Even although additionally viewing it as not likely, Applegate talked about the doable for a revised think about could presumably not be out of the query lastly, equipped how some value modifications floor to have taken preserve. 

    “I would not be shocked if we felt significantly better at 2.5%, and so they improved that, as a result of I simply by no means know the way you are likely to undo a few of the will improve which are baked into this system, irrespective of whether it is actually gasoline, housing, well being care,” she talked about. 

    The wait-and-see tactic already has a number of housing economists, like researchers at Fannie Mae, anticipating home mortgage costs to remain increased for longer. In its most present financial forecast, the govt-sponsored group claimed it anticipates costs to widespread 6.6% this yr however slipping again to six.1% in 2025.

    The Mortgage mortgage Bankers Association created very comparable strikes. “With our April forecast, we decreased our figures for originations and marked up our expectations for residence finance mortgage charges, and trendy FOMC remaining determination confirms these individuals revised anticipations,” mentioned MBA Main Economist Mike Fratantoni in a push launch. 

    As predicted, the FOMC defined it ready to take care of the runoff fee on mortgage‑backed securities in its portfolio at $35 billion, reinvesting further principal funds into Treasurys. 

    Also as deliberate, rolloff of Treasury-backed securities will lower to $25 billion for each thirty day interval from $60 billion starting in June. “More than time, this adjustment must have some optimistic impression on curiosity premiums with out the Fed needing to change the Fed funds fee,” Marty Eco-friendly, lover at regulation agency Polunsky Beitel Green, mentioned in a assertion.

  • Melton BS cuts 95% LTV by up to 46bps, launches shared possession loan   – House loan Tactic

    Melton Constructing Culture has slice charges on its 95% monetary loan-to-value merchandise by up to 46 basis factors, whereas introducing a mannequin new 95% LTV shared possession supply, equally of that are geared toward 1st-time potential patrons.  

    The mutual has repriced family five-year 95% LTV fixes to 5.29% from 5.75, with no utility charges.  

    It additionally launches a 95% LTV shared possession present at 6.00%, additionally with no utility fees.  

    Melton Setting up Modern society head of merchandise and advertising and marketing and promoting Jamie Hyland states: “The Creating Societies Association have simply these days launched a overview into the actions of FTBs concluding that it’s essentially the most exhausting it has been for a while for these searching for to escape the rental sector and enterprise into home possession.   

    “At Melton Building Society we recognise the troubles that FTBs face and as a mutual setting up tradition, we’re devoted to supporting these folks with aspirations of dwelling possession by furnishing a broader array of decisions for FTBs.   

    “The addition of our 95% LTV shared possession answer and the discount on our standard residential options re-affirms our motivation to supporting a array of FTBs obtain their ambitions of home possession.” 

  • Virgin Dollars cuts BTL, resi minimum conditions to 5 years   – Home loan Technique

    Virgin Money has decrease its landlord and residential residence loan minimal time period to 5 years from 7.  

    The loan supplier tells brokers that their shopper’s “chosen time period has to lengthen past the preliminary product’s shut day.   

    “So, for example, if a shopper is wanting for a 5-calendar 12 months phrase, they might require to get a two, or 3-calendar 12 months services or products.”  

    In a restricted take notice to intermediaries, the financial institution provides that the shift “will provide prospects with far more mortgage selection”.

  • LendInvest cuts resi costs by up to 25bps    – Home finance loan Technique

    LendInvest Mortgages has slash costs all through its residential dwelling loans by up to 25bps.  

    The largest charge cuts are on its tracker items, which have been decreased by up to 25bps, with its fixed-price merchandise lowered by up to 15bps.  

    The financial institution has additionally launched new no-rate merchandise, designed to assist purchasers with the upfront charges of their dwelling finance loan.  

    As a consequence of those variations, its tracker selection now begins at a cost of 5.75%. This is available on its five-year deal up to 75% LTV, and arrives with a £995 charge.  

    LendInvest’s family selection entails professional items for debtors with quite a few sources of income, the self-used, important staff and other people with far more elaborate credit score rating histories. 

    LendInvest head of product gross sales Paula Mercer suggests these changes arrived because of feed-back from its dealer companions.  

    She gives: “In the calendar yr as a result of we launched family dwelling loan options, we’ve seen plenty of urge for food and have realized from our dealer feedback so we will keep setting up a merchandise vary that meets the wants of debtors who’re underserved by the mainstream home loan lenders.” 

  • Bluestone cuts clawbacks on in the vicinity of primary and expert dwelling financial loans

    Bluestone cuts clawbacks on in the vicinity of prime and expert home financial loans | Australian Broker News

    Professional Lending

    Bluestone cuts clawbacks on close to key and expert home financial loans

    Clawback interval of time minimize from 18 months to six months

    Bluestone cuts clawbacks on near prime and specialist home loans

    Specialist Lending

    By
    Ryan Johnson

    House mortgage mortgage supplier Bluestone Household Loans has launched a substantial alter to its near prime and skilled family mortgage items, reducing down the clawback time interval from 18 months to 6 months.

    This adjustment will take affect for throughout primary and specialist financial loans settled from April 1, giving brokers with further safe earnings when publishing these sorts of financial institution mortgage promotions.

    Bluestone’s essential industrial officer, Tony MacRae (pictured earlier talked about), stated that the transfer aimed to steerage brokers in serving patrons with non-common lending requires.

    “We have an understanding of that some clients will graduate to different mainstream varieties of lending and actually do not consider {that a} dealer’s earnings have to be at chance when this happens,” Macrae claimed.

    Why lessening clawbacks is excellent enterprise

    These collectors at the moment are taking methods to cut back clawback durations, indicating a broader movement to make their merchandise way more fascinating to brokers.

    For MacRae, it was a straightforward choice.

    “There has been significantly debate in the sector about the equity of clawbacks and we really feel in this merchandise set it could make sense to minimize the at-hazard interval and we persuade brokers to find non-conventional lending as a signifies to develop their companies,” MacRae stated.

    “In talking with many brokers in extra of the earlier 6 months, a prevalent theme has been that they incessantly allow customers stroll out the doorway as they actually do not assume they’ll support them.”

    Bluestone: The non-standard purchaser skilled

    Bluestone presents a assortment of merchandise and options supposed for patrons who won’t often meet the calls for of conventional banking establishments.

    This includes options for self-utilized folks with completely different earnings verification methods, as completely as merchandise for all these in search of to consolidate private debt or deal with tax liabilities. Also, these items cater to patrons with troubles in their credit standing file.

     “The discount in clawback interval of time gives greater certainty for brokers and because of this there has rarely been a significantly better time to speak to a Bluestone BDM,” MacRae stated.

    Profitable combo: Clawbacks and diminished servicing buffer

    Benefiting brokers instantly, this alter is one of quite a few current optimisations executed by the company, which embody rising its BDM workforce about the final 6 months to lift dealer support and implementing greater than 20 plan optimisations in September final 12 months.

    Not too way back, for instance, Bluestone had reaffirmed its motivation to accessible lending with the ongoing presenting of a decrease serviceability buffer.

    This buffer has been lessened from 2% to 1.5% for financial loans with as much as 70% LVR on close to key and primary objects, a transfer that considerably optimistic points brokers and their purchasers.

    Brokers usually expertise difficulties in furnishing a broad vary of mortgage choices to their self-utilized clientele since of demanding serviceability requirements.

    To deal with this, MacRae stated that Bluestone sights these purchasers not as dangers, however as people with distinctive wants that require personalized options. 

    “Big banks have prolonged considered as these buyer’s additionally troublesome, and each equally brokers and their purchasers have endured because of this” said MacRae.

    “Our said goal is to be the go-to financial establishment for brokers with non-typical customers, and this change in our serviceability buffer is simply the most up-to-date in our protection alterations that operate towards that end.

    “Brokers function with non-regular purchasers. We need to be the ‘go-to’ non-conventional lender who recognises that.”

    What do you think about about Bluestone’s hottest announcement? Comment beneath.

    Associated Stories

    Continue to maintain up with the latest information and conditions

    Join our mailing file, it’s cost-free!

  • Dudley BS cuts expat, self-make financial loans by up to 35bps   – Property finance loan System

    Dudley Making Culture will slash costs all through its expat and self-establish residence financial loans by up to 35 foundation elements tomorrow (23 April).  

    The mutual states two-12 months mounted expat family prices will now get began at 6.45% for financial loans up to 60% private loan to profit and from 6.55% for financial loans up to 85% LTV.   

    Two-calendar yr acquire-to-permit expat fixes will begin at 6.55% for up to 70% LTV and 6.65% for up to 80% LTV.  

    Expat trip enable two-12 months fixes will start at 6.55% up to 70% LTV and 6.65% up to 80% LTV.  

    The loan supplier will contemplate functions from an enormous number of nations and in above 160 currencies and may accept income from one abroad foreign money, furthermore earnings derived in sterling.  

    In the agency’s self-create array, its 2.40% self-build low value for phrase (advance) cost might be decreased to 6.84% up to 80% LTV, though the two.50% self-build discounted for expression (arrears) cost has been decreased to 6.74% up to 80% LTV.  

    The 2.60% eco self-establish worth reduce for expression (progress) payment might be decrease to 6.64% for loans up to 80% LTV, although the two.70% eco self-develop low value for expression (arrears) price might be decreased to 6.54% for financial loans up to 80% LTV.  

    The mutual will lend up to £1.5m throughout its expat family vary and up to £1m throughout its expat BTL and trip allow differ, in addition to its self-establish merchandise.  

    Dudley Making Modern society distribution director Robert Oliver states: “Brokers will be assured that they may obtain a flexible and personalised methodology to underwriting when publishing dwelling finance loan functions to us.”  

  • Atlantic Bay exec predicts house loan marketplace cuts

    Scott Reise, senior vice chairman at Atlantic Bay Mortgage Group, has been within the lending marketplace for virtually 3 a few years, with stints at banking firms, neutral dwelling finance loan firms and dealer retailers.

    Though he is in the intervening time at an IMB, Reise thinks no channel is much better than the opposite. The solely matter that differentiates a agency is administration.

    “It actually is the management, or the C-degree folks functioning the company that severely dictates, not simply in our marketplace, however in any marketplace, how achievement is heading to occur,” he mentioned. 

    Scott Reise, Sr. VP Atlantic Bay Mortgage

    With the property finance loan business at present weathering an extended spell of tumult, Reise suggests he’s observed a improvement of leaders not stepping as much as the plate to be clear.

    “I do actually really feel like you can see an unbelievable quantity of egocentric folks at this time on this sector which can be solely searching out for themselves and don’t give a rattling about any individual else,” he claimed. “I’m not declaring which is the the overwhelming majority, I believe that is within the minority.”

    The lack of leaders stepping up at companies is specifically highlighted when firms make troublesome choices to rightsize their retailers, he talked about. Executives actually needs to be “present, on the entrance strains and talking with their folks, [thereby] organising loyalty in simply the group,” Reise extra.

    Countrywide Mortgage Information interviewed Reise concerning the state of the property finance loan enterprise at this time, how leaders should handle rightsizing and why originators might be on the chopping block this calendar yr. This interview has been condensed and edited for readability.

  • Alongside one another cuts rates throughout array by up to 205 bps – Home loan Finance Gazette

    Collectively has lowered premiums throughout its initially value, second demand and consumer make investments in-to-enable choice by up to 205 foundation particulars.

    Tanya-Elmaz-620x330.jpg

    The lender has minimized its 1st value charges by up to 130 bps in order that these now begin from 7.99% for a 5-calendar 12 months mounted value and eight.2% for a two-year preset.

    To begin with cost variable premiums get began from 10.05%.

    It has scale back charges on its 2nd value range by up to 170 bps in order that five-year fixes now begin off from 8.3%, two-calendar 12 months fixes from 8.5% and variable premiums from 10.45%.

    Customer purchase-to-let promotions have decreased by up to 205 bps and now get began at 6.95% for a five-calendar 12 months fastened, 7.10% for a two-calendar 12 months fastened.

    Second demand purchaser purchase-to-enable reductions start from 7.5% for a 5-yr resolve and seven.65% for a two-calendar 12 months repair.

    In addition to fee reductions, 2nd demand loans from £30,000 to £50,000 will now be certified for Together’s least expensive rates and can be open up to debtors who’ve skilled credit score blips within the earlier.

    For extra compact loans of £20,000 to £30,000, prices begin off from 9.35% for a five-year mounted and 10.15% for a two-yr mounted.

    The highest LTV for these extra compact monetary loans has larger to 75%.

    Collectively director of middleman product gross sales Tanya Elmaz says: “We are eager to clearly present that we handle a healthful starvation for lending regardless of the financial turbulence the market place has educated over the sooner few of many years.”

    She offers: “We’ve listened to opinions from our middleman companions and constructed enhancements according to what they want.”

  • The Scenario of The Disappearing Rate Cuts

    The Fed anticipated to have the ability to cut back prices 3 instances in 2024 as a short time in the past as March. Money marketplaces agreed. But the information which is come out contemplating the truth that then has everybody singing a particular tune.  This week’s information was much more of an afterthought in distinction to final week’s.

    20240419 nl6.png

    The chart larger than pertains to Fed quantity anticipations, and that is not exactly the exact same as longer time interval prices like dwelling loans and 10yr Treasury yields.  The latter seen a bit extra volatility this 7 days.

    Monday’s Retail Income particulars was a lot a lot better than anticipated and marketplaces reacted promptly.  Tuesday’s data was consequential, nevertheless it was adopted by a speech by which Fed Chair Powell had an probability to produce some present views on the speed outlook.  Immediately in spite of everything, the Fed hadn’t seen probably the most present CPI information (and a quantity of different highly effective experiences) on the time the final spherical of charge projections arrived out in March.

    As the market anticipated, the tone is evolving.  Though Powell and the Fed repeat that the speed route relies on financial information, it is no shock to see newest opinions acknowledging a astonishing sum of energy within the present information.  Much higher data suggests a lot much less quantity cuts.  Powell went so far as saying there was new uncertainty as to regardless of whether or not the Fed will even be able to slash in 2024.

    Two instances in a while, NY Fed President John Williams struck equal tone.  Just previous week, he had pushed again on the CPI data, expressing the Fed wasn’t amazed by setbacks within the inflation information.  This week’s opinions did extra to acknowledge the opposite side of data dependency.  Particularly, Williams acknowledged the Fed may hike but once more if the information named for it.  

    To be completely certain, these should not earth-shattering “ifs” and “thens.”  But the present market hones in on the refined discrepancies with which the data dependency is communicated.  It did not assist that Thursday morning’s Philly Fed Manufacturing Index moved as much as one of the best ranges in 2 a number of years or that the “value ranges compensated” ingredient of the similar report moved up considerably excess of economists envisioned.

    20240419 nl4.png

    20240419 nl5.png

    This is how the entire 7 days appeared in phrases of 10yr Treasury yields.

    20240419 nl2.png

    Friday’s response to the assaults in Iran is significant given that it reveals us that some geopolitical information is definitely worth a response.  That was fewer crystal clear beforehand within the week as varied batches of pretty comparable headlines unsuccessful to trigger as an ideal deal movement.  The distinction on Friday was the uncertainty above the standing of Iran’s nuclear web sites in addition to situation that it will be the catalyst for the outbreak of considerably further sizeable preventing.  The market calmed down fairly speedily after it was very clear the nuclear web sites had been not weakened and that Iran was not retaliating.  The correlation in between stock costs and bond yields additional confirms the “flight to security” investing sample usually discovered instantly after this type of information.

    20240419 nl1.png

    In the even larger picture, the sooner 2 months have lengthy gone a really good distance in direction of making the conclusion of 2023 search like however a unique “pretend begin off” in direction of cut back prices.  Up until then, we skilled type of a sideways combating probability.  When we now have labeled late 2023 because the third false begin off of this cycle, it will not meet up with the purest definition proper till costs enhance again once more over final October’s highs.  We are completely not there nonetheless and we won’t possible know if we’re going to get there proper up till we see the upcoming spherical of large ticket financial particulars in Could.

    20240419 nl7.png

    In the meantime, residence revenue carry on being constrained.

    20240419 nl3.png

    Upcoming week’s financial data is fairly muted other than Friday’s PCE worth index.  This simply is not as an ideal deal of a market mover because the Purchaser Price tag Index (CPI), nevertheless it may undoubtedly result in some volatility if it transpires to ship a definite idea.

  • Atom provides around primary offers and cuts costs by up to 30 bps – Mortgage loan Finance Gazette

    Atom has launched numerous within the neighborhood of-primary merchandise and options and decrease charges on some others by up to 30 basis particulars.

    mortgage-searches-magnifying-glass-house-620x330.jpg

    The monetary establishment has now slash shut to-prime two-yr mounted charges by between 10 and 30 foundation particulars and 5-calendar 12 months fixes by involving 15 and 30 bps.

    As a consequence, two-calendar 12 months mounted costs begin at 6.14% and five-yr fixed costs at 5.64%.

    Its new three-year fixed charges begin out at 5.99% and go up to a biggest of 85% financial institution loan-to-worth.

    Head of mortgages Richard Harrison claims: “We know that brokers will welcome a broader vary of competitively-priced options as they cater for people clientele who might effectively have the odd black mark of their credit score historical past information.

    “The troubles of recent many years have put family budgets lower than stress, and will inevitably remaining lead to way more debtors with credit score blips slipping into the close to prime classification.

    “That’s why Atom lender is devoted to providing not solely aggressive merchandise for these debtors, however the best possible information a lot too.

    “We have opened up the larger use of technological innovation on within the neighborhood of key cases, these sorts of as automated valuations, to make sure that these debtors reward from the market place-top response moments that our key buyers now take pleasure in.”