Tag: costs

  • Homeconstructing supply costs surge at fastest pace in over a year

    Homebuilder supply costs in June, in comparison with the identical time in 2023, rose by the best quantity since early 2023, whilst costs for lumber and metal merchandise pulled again, in line with new evaluation.  

    Prices for residential building items completed 2.65% greater in June in comparison with ranges from the identical month a year earlier. The charge headed upward from a revised 2.36% surge seen in May. The June improve is the biggest since February 2023, in line with evaluation of U.S. authorities information from the National Association of Home Builders. 

    June costs additionally elevated 0.19% month to month in comparison with a fall of 0.26% in May. Year so far, costs for residential building items have taken a totally different course from different financial traits, NAHB stated. 

    “Despite total inflation declining, costs for inputs to residential building have accelerated for the reason that begin of the year, leaving homebuilders to proceed to cope with greater constructing materials costs,” wrote Jesse Wade, NAHB economist and director of tax and commerce coverage evaluation, in a analysis publish. 

    In distinction to the month-to-month improve in constructing materials costs, the newest Consumer Price Index confirmed inflation declining 0.1% between May and June. Rising costs contributed to falling homebuilder sentiment in June as effectively, with the month-to-month NAHB/Wells Fargo measure dropping to its lowest mark this year.  

    Homebuilder supply costs had been greater total regardless of falling in some important classes. The seasonally adjusted quantity for softwood lumber got here in 7.41% decrease year over year. But it additionally got here in greater by 3.41% from the earlier month, reversing course from the 5% decline in May. Lumber costs stay decrease than their ranges in the course of the pandemic however presently stand above the place they had been in 2019.

    Non-seasonally adjusted costs of steel-mill merchandise had been down 15.01% from June 2023 and 1.18% from the prior month. In May, costs took a 13.81% fall however rose 0.54% on a month-to-month foundation. The year-over-year tumble in June was the largest since final August. 

    Lower metal and lumber costs had been offset by worth development in different supplies, with non-seasonally adjusted gypsum merchandise coming in 2.32% greater yearly however unchanged between May and June. 

    Meanwhile copper merchandise posted worth positive aspects of 12.64% year over year however dropped from the earlier month’s mark by 2.67%. 

    The value of ready-mix concrete additionally elevated 6.51% from June 2023 and 0.45% between May and June. Prices had been seasonally adjusted.

    “Compared to different constructing supplies, ready-mix concrete continues to characteristic year-over-year development above 5%. This has been the development since late 2021,” in line with Wade.

  • JPMorgan sees financial investment banking costs up, loans flat in 2nd quarter

    JPMorgan Chase launched their 2nd-quarter earnings remaining outcomes Friday.

    Jeenah Moon/Bloomberg

    This is a buying story. Make certain you take a look at again once more beneath for updates.

    JPMorganChase noticed a 25% soar in features in the second quarter, pushed by an $8 billion windfall from cashing in on Visa shares this spring.

    The $4.1 trillion-asset financial institution’s earnings uncovered how financial uncertainty continued to put stress on sure traces of group this quarter. Excluding the Visa transaction, JPMorgan seen features of $13.1 billion, marking a slight drop from the previous quarter. Profits beat analyst estimates, boosted by a 50% soar in financial investment banking costs, however loans and deposits remained flat.

    JPMorgan famous earnings per share of $4.40, beating analyst forecasts of $4.20.

    Chairman and CEO Jamie Dimon defined in a prepared assertion that inflation and curiosity charges would possibly “maintain bigger than {the marketplace} expects,” however reiterated self-confidence in the financial institution’s signature fortress stability sheet.

    “Even although trade valuations and credit standing spreads seem to replicate a moderately benign financial outlook, we stock on to be vigilant about probably tail challenges,” Dimon said.

    CFO Jeremy Barnum further on a join with with reporters Friday early morning that the elevated tail hazards impacting the financial institution’s outlook, these sorts of as geopolitical difficulties and financial uncertainty, have not shifted.

    Higher-for-for an extended interval fascination premiums proceed on to tamp down on financial institution mortgage progress and deposit expenditures, however JPMorgan has been able to make up income by prices from expense banking merchandise and options and set money circulation and equity marketplaces revenue.

    The financial institution’s shares opened further than 2% down from the prior working day.

    Nonetheless, JPMorgan’s Friday report was primarily unsurprising.

    Expenditures had been being in line with estimates at $23.7 billion, up 14% from the earlier 12 months, which embody a $1 billion contribution to the corporate’s foundation for charitable wants.

    JPMorgan amplified provisions for credit standing losses to $3.1 billion, up from $1.9 billion the prior quarter, as credit standing card losses mounted for every former predictions. Barnum defined the rise in card demand-offs represented a “normalization comparatively than deterioration.” He further that the lender is constructive on the state of the patron.

    Edward Jones analyst James Shanahan wrote in a notice Friday early morning that JPMorgan’s numerous strains of enterprise enterprise placement the lender very nicely to “contend all around the financial cycle.”

  • Mortgage costs increase on financial uncertainty

    Home finance mortgage premiums elevated this previous week, as Treasury yields elevated many of the 7 days on financial uncertainty, while Wednesday early morning info drove people lower but once more.

    In the six days in between June 28 and July 2, the 10-yr Treasury rose 15 foundation elements to 4.44%. But by 11 a.m. these dropped by 10 foundation particulars on weaker-than-forecast financial data, specifically all-around non-public sector work.

    The 30-12 months mounted payment home mortgage averaged 6.95% on July 3, up from 6.86% 6 instances prior and 6.81% for the precise 7 days in 2023, the Freddie Mac Key Property finance mortgage Sector Study claimed.

    The examine was launched a working day early and modified for the July 4 Independence Day vacation break.

    “Each new residence and pending residence earnings are down, creating full of life listings to rise,” Sam Khater, Freddie Mac foremost economist, claimed in a press launch. “We are nonetheless anticipating fees to reasonably reduce within the 2nd 50 % of the yr and offered supplemental stock, value progress should mood, boding very properly for intrigued homebuyers.”

    The 15-year FRM additionally enhanced by 9 foundation particulars to six.25%, from final week’s 6.16%. It can also be 1 foundation difficulty bigger than wherever it was for this time period last yr, when it was 6.24%.

    Zillow’s quantity tracker skilled the 30-yr FRM at 6.78% on Wednesday morning, down 1 basis place on the working day, however up 14 foundation elements from the previous week’s typical.

    Loan supplier Price tag knowledge posted on the National Home finance mortgage Information web site was once more round 7% at that very same time, to 7.023%, as opposed with 6.995% six days beforehand.

    The increase within the 10-year Treasury earlier than within the week mustn’t at all times translate to elevated residence finance mortgage costs, mentioned Eric Hagen, analyst at BTIG, in a July 2 residence mortgage finance roundup report.

    “With gain-on-sale margins for originators now within the neighborhood of the tights, home mortgage premiums ought to actually have respectable help to maintain beneath 7% if the 10-12 months is capped throughout its [year-to-date] increased of 4.75%,” Hagen defined.

    Likely ahead, Hagen mentioned forecasting non-bank originations was “delicate” due to banking firms ceding market place share, irrespective of the place fees are, as a consequence of “the way more punitive proposals for Basel III.”

    That would result in these banking firms buying to take care of extra funds from unused warehouse strains of credit score, “which might produce a disproportionate results to extra compact depositories and different collectors,” he ongoing.

  • Coventry BS cuts resi, landlord costs by up to 21bps – House loan Method

    Coventry for intermediaries has slice chosen family and landlord preset-amount monetary loans for brand spanking new and present customers by up to 21 basis components.

    The mutual suggests two-, a few- and five-yr fixes can be found for family functions, with choices that selection from 65% monetary loan to worth to 95% LTV.

    Acquire-to-let charges have been lowered by up to 15bps.

    Highlights incorporate:

    Two-yr fixes to 31 January 2027, at 85% LTV at 5.34%, with £500 cashback – solely obtainable for initial-time clients
    5-12 months fixes to 31 January 2030 at 65% LTV at 4.59% – obtainable for family remortgages with the potential of £350 cashback or use of the lender’s remortgage switch service

    Coventry Building Society head of intermediary associations Jonathan Stinton says: “We’ve lessened the the higher a part of our mounted expenses, extra strengthening the alternatives we offer.

    “It presents brokers a unbelievable alternative to work together with their customers and suggest them of the best choices accessible.”

  • Insurance costs drive inflation | Australian Broker News

    Insurance protection costs push inflation | Australian Broker News

    Information

    Insurance insurance policies costs drive inflation

    Could RBA elevate charges?

    Insurance costs drive inflation

    The newest inflation particulars has disclosed skyrocketing protection premiums may journey the RBA towards a {dollars} worth hike in August, in response to an protection specialist.

    “This relentless enhance in insurance coverage insurance policies premiums, successfully over and above will increase in different worth classes, is an inflation villain that would see us all expertise from better curiosity costs this calendar 12 months,” mentioned Marty Sadlier (pictured increased than), director at MCG Quantity Surveyors.

    A deep dive into the data reveals insurance coverage premiums rose a staggering 14% in the midst of that point – the perfect proportion obtain throughout each single expenditure class within the analysis.

    “Premiums are, pretty frankly, out of command,” Sadlier acknowledged. “People might want to discover the fallout from growing charges isn’t remoted to policyholders. The affect flows through to us all in myriad methods.”

    Broader monetary results

    Sadlier spelled out the broader implications of climbing insurance coverage protection charges.

    “High insurance coverage coverage expenditures are observing enterprises throughout the state acquiring to reduce investing and staffing ranges and, in some circumstances, shut their doorways altogether,” he mentioned.

    This consists of area people amenities and tiny enterprises this type of as eating locations, cafes, and health facilities.

    “Higher charges additionally counsel significantly much less disposable income for houses, which solely provides to the struggling for regional companies,” Sadlier reported.

    Regulatory merely name to movement

    Sadlier known as for fast regulation of the insurance coverage protection sector.

    “It’s essential authorities part in and forestall insurers from quoting outrageous premiums which are decimating enterprises, driving inflation and leaving Australians at hazard of heading broke,” he claimed.

    He additionally pressured the price of exact residence insurance coverage insurance policies and the job of insurance coverage coverage brokers.

    “Insurance brokers can retailer about to safe you probably the most aggressive high quality within the present market and guarantee there aren’t any loopholes for non-payment by insurers within the celebration a declare is lodged,” Sadlier talked about.

    Get the most popular and freshest mortgage information shipped appropriate into your inbox. Subscribe now to our FREE every day publication.

    Similar Tales

    Continue to maintain up with probably the most up-to-date data and conditions

    Be part of our mailing guidelines, it’s completely free!

  • Mounting design costs threaten viability of Australian initiatives

    Mounting design charges threaten viability of Australian jobs | Australian Broker News

    News

    Mounting design charges threaten viability of Australian jobs

    Field report highlights financial strains on growth

    Rising construction costs threaten viability of Australian projects

    Climbing wages and stagnant productiveness are considerably driving up development bills in Australia, impacting the 2 infrastructure assignments and industrial developments, in accordance to probably the most up-to-date market sentiment report from Arcadis and the Australian Constructors Affiliation (ACA).

    ACA CEO Jon Davies (pictured earlier talked about) identified that the wage disparity amongst governing administration and private sector initiatives is a key scenario.

    “Higher labour expenditures and stagnating productiveness progress are additionally diminishing the economical viability of industrial developments,” Davies claimed, noting that 81% of respondents described stagnation or decline within the family growth sector.

    The report identifies the most popular sectors in growth as electrical energy and vitality, ingesting water, and protection. Expenditures for certified trades, typical labour, and consultants have risen steadily, averaging a couple of 5% enhance from remaining yr.

    Even so, it additionally highlights a decline in sector sentiment owing to authorities cutbacks, enterprise sector uncertainty, and delays in new electrical energy initiatives.

    “Amidst the publish-pandemic restoration, Australia’s design sector proceeds to grapple with political turbulence and industrial strife, escalating costs and stifling productiveness, which is threatening the very viability of jobs and firms,” said Matthew Mackey, government director of cost and industrial administration at Arcadis.

    A special sizeable scenario is the allocation of pitfalls inside of contracts. Practically three-quarters of respondents imagine that present-day contracts don’t fairly distribute risk between get-togethers.

    “Risk allocations, like individuals related to the altering IR environment, are vital impediments to enterprise viability,” Mackey mentioned.

    Davies additionally harassed the necessity for enhanced process organizing and decreased growth bills to make sure Australia pays for the infrastructure it necessities: “We must should double down on collaboration to repair enterprise worries alongside each other and we wish to enhance area productiveness as a topic of urgency.”

    Relevant Tales

    Keep up with the most recent info and gatherings

    Sign up for our mailing file, it’s free!

  • Lessen costs will not travel increased origination amount, Fannie states

    Fannie Mae economists have diminished their projections for the place fees for the 30-12 months home mortgage will shut this 12 months, bringing their outlook once more beneath the 7% mark.

    Nevertheless, that will not translate to amplified originations, as additionally they slice their amount forecast for equally 2024 and 2025 from what they predicted earlier thirty day interval.

    Fannie’s June forecast can also be predicated on weaker gross home merchandise improvement than beforehand anticipated, as very properly as solely a solitary December shorter-term fee reduce from the Federal Open Sector Committee previous expectations have been for 2 reductions.

    “The financial system seems to be slowing, and present readings current hope that inflation is cooling quickly after progress on that entrance stalled within the 1st quarter — a pattern that will possible require to be sustained for the Fed to really feel cozy chopping premiums,” defined Doug Duncan, Fannie Mae’s fundamental economist, in a press launch.

    “Sad to say, we’re nonetheless not forecasting a ramp-up in housing exercise, which will demand some mixture of continued residence earnings development, a extra slowing of family price ticket appreciation, or a drop in residence finance mortgage fees to supply affordability inside fluctuate of plenty of ready round initially-time and shift-up homebuyers.”

    For the entire yr, Fannie Mae expects the 30-yr FRM to typical 6.8%, which embrace falling to six.8% for the third quarter and 6.7% within the fourth quarter. In May’s forecast, Duncan forecast costs averaging 7% every for all of 2024 and only for the fourth quarter, following reaching 7.1% in equally the 2nd and third quarters.

    June’s outlook has the 30-year dropping to six.3% by the fourth quarter of subsequent yr, with an typical of 6.5% for all of 2025. This compares with the May outlook’s prediction of 6.6% within the fourth quarter and 6.7% for the whole 12 months.

    “Fascination premiums proceed to be risky, considerably provided adjustments to Fed protection expectations, which offers hazard to our outlook,” the web site article accompanying the forecast claimed. “Next the completion of our begin out-of-the-thirty day interval curiosity cost forecast and as of this writing, 10-calendar yr Treasury costs have lessened near 25 basis elements adhering to the May properly [Consumer Price Index] launch, major to some draw again risk to our present baseline property finance mortgage price forecast.”

    While the reduce price outlook led Fannie Mae to raise its forecast from remaining thirty day interval for refinance originations for the following two years, that was outweighed by its slice in spend money on motion.

    It dropped its general home earnings forecast to 4.82 million from 4.89 million.

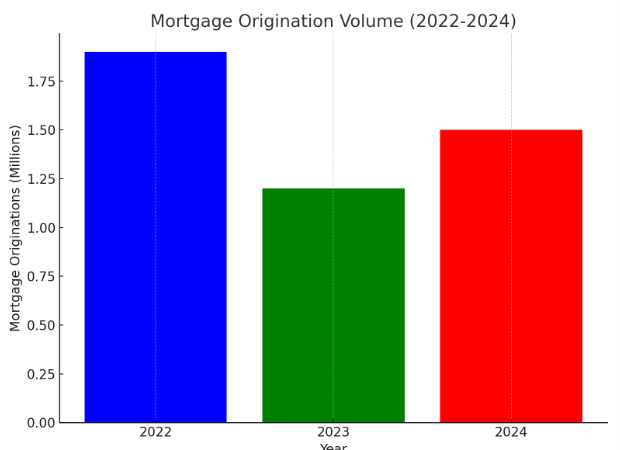
    The June outlook predicts the house mortgage discipline will generate $1.714 trillion in mortgages this yr, up from an estimate of $1.47 trillion for 2023. This in contrast with May’s forecast of $1.73 trillion.

    It telephone requires $372 billion of refinance exercise, up from the prediction in May probably of $368 billion. On the order facet, the June forecast of $1.342 trillion, compared with May’s $1.363 trillion. In 2023, the sector did $1.222 trillion of order originations.

    Through 2025, Fannie Mae seems to be like for the mortgage mortgage sector to make $2.068 trillion, with $1.525 trillion in spend money on and refinancings producing up $544 billion.

    That compares with the May probably forecast for $2.076 trillion, constructed up of $1.537 trillion in acquire amount and $539 billion of refis.

    Freddie Mac additionally issued its most up-to-date monetary forecast in distinction to different prognosticators, it does not disclose specific quantity figures. Its May maybe forecast termed for premiums to maintain on being elevated by way of the comfort of the yr.

    “As we anticipate a moderation in family earnings, substantial value ranges, and a flat {dollars} share of buys, we hope buy origination to be slightly bit increased in 2024 than in 2023,” the June 20 web page write-up from the Freddie Mac economics group, headed by Chief Economist Sam Khater talked about. “With residence mortgage costs above 7%, refinance motion is predicted to be nominal.”

    On that very same day, it launched the weekly Key House mortgage Marketplace Study which identified the 30-yr FRM averaged 6.87%, the third consecutive week it was beneath 7% and essentially the most inexpensive degree as a result of April 11.

    “Even so, if curiosity charges drop down under 6.5%, refinance train might see some uptick, as hundreds and hundreds of debtors nonetheless have costs beforehand talked about 6.5%,” Freddie Mac reported. “Yet, given persistent inflation, reaching fees down under 6.5% is hard.”

  • Home finance loan costs slide to most affordable issue in above a month

    House loan charges sank to their least expensive stage in over a thirty day interval as the most popular financial particulars is reinvigorating buyers’ notion that a reduce in small-term charges by the Federal Open Market Committee is possible.

    The 30-yr mounted fee mortgage fell by 8 foundation elements to 6.87% on June 20, in comparability with 6.95% 1 7 days beforehand and 6.67% for the exact same time interval in 2023, the Freddie Mac Main House loan Market Survey claimed.

    At the very same time, the 15-yr FRM declined 4 basis particulars to 6.13%, down from 6.17% on June 13 however up 10 foundation factors from 6.03% one 12 months earlier. This is the most cost effective home loan costs are at contemplating the truth that the April 11 research.

    “House loan costs fell for the third straight week subsequent indicators of cooling inflation and market anticipations of a upcoming Fed fee slice,” defined Sam Khater, Freddie Mac’s important economist, in a push launch. “These reduce property finance loan costs coupled with the step by step strengthening housing present bodes successfully for the housing market place.”

    Zillow’s quantity tracker place the 30-calendar 12 months FRM at 6.56% as of 11:45 on Thursday early morning, up 2 basis particulars on the day however down 3 foundation particulars from the prior week’s common.

    Meanwhile, particulars from Lender Price posted on the National House loan News web website set the 30-year FRM 2 basis elements bigger than wherever it was final week, at 6.86% in contrast to 6.84%.

    At the similar time, the 10-year Treasury produce was up 5 basis particulars on the working day, to 4.27%. On June 13, it closed at 4.23%, however bounced up and down regarding a minimal of 4.19% and a massive of 4.30% over the upcoming 7 days.

    Though the FOMC handed on a payment cut back at its previous meeting and designed statements on the potential of future steps, the business consensus is that it’s going to act at Sept. 18 assembly, Louis Navellier, an expense banker stated, incorporating “however I additionally imagine that that the Fed ought to decrease very important want costs on July 31.”

    But if bond vigilantes drive Treasury yields cut back, then the Fed might presumably be compelled to lower important fascination costs quicker than later,” Navellier stated.

    The marketplaces are again once more to information watching, claimed Melissa Cohn, regional vp of William Raveis Mortgage.

    “There ended up no large surprises in the Fed’s responses or dot plot,” Cohn said in a assertion. “Expecting only one value slash should be impartial for the marketplaces, and the Fed’s foreseeable future steps will depend upon the markets.”

    Up coming month’s Consumer Cost Index report retains the essential for what the FOMC will do. If it reveals further progress in phrases of lowering inflation, “then we may have a wonderful summertime for house finance loan costs and the actual property sector,” Cohn talked about.

  • Federal Reserve Indicators Steadiness in Costs

    &#13
    &#13

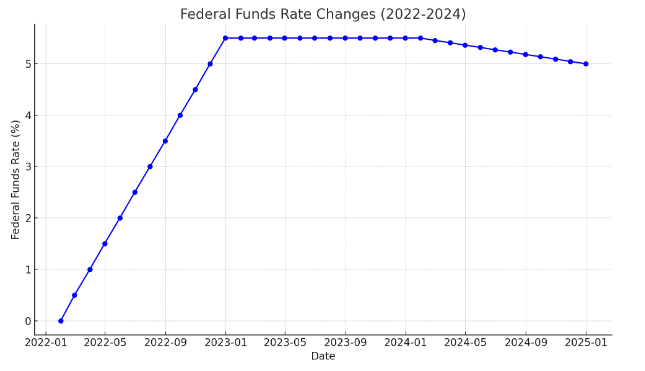
    In a big transfer that impacts the 2 the housing trade and home mortgage establishments like Evergreen Household Loans, the Federal Open Marketplaces Committee (FOMC) has declared the servicing of its short-phrase protection fascination quantity amongst 5.25% and 5.5%. This resolution, launched on Wednesday, marks the fourth time in 2023 that the FOMC has paused price hikes, subsequent 11 improves since March 2022.

    Federal Reserve Chairman Jerome Powell, addressing the most recent financial native climate, indicated an expectation of some 25 basis stage reductions in costs all by way of 2024. This strategic change indicators the tip of value hikes and a brand new interval in financial coverage, doubtlessly bolstering expenditure confidence.

    Responding to this development, the bond trade noticed a fall in the 10-yr Treasury yield to 4.%, a decreased provided that late July. Authorities, corresponding to Mike Fratantoni from the Property finance mortgage Bankers Affiliation, interpret this as an cease to conversations about extra charge hikes, concentrating in its place on the quantity discount tempo. This is predicted to positively have an have an effect on on housing and residential mortgage marketplaces, probably major to reduce mortgage mortgage expenses and spurring modest development in residence gross sales for 2024.

    Evergreen Property Loans, a significant participant in the property finance mortgage sector, has been rigorously checking these developments. “The Fed’s willpower aligns with our expectations and bodes correctly for homebuyers and the over-all housing market,” states a spokesperson from Evergreen Household Financial loans. “We foresee an uptick in mortgage mortgage pursuits, which embody refinancing, as charges turn into way more favorable.”

    Through 2023, the Fed’s charge hikes impacted many sectors, with the home mortgage enterprise being notably influenced. TransUnion critiques a 37% year-about-12 months reduce in mortgage originations. Evergreen House Loans, alternatively, has navigated these troubles by concentrating on client-centric options and anticipates a much more favorable pure setting in 2024.

    Selma Hepp, major economist at CoreLogic, notes that in spite of a potent November jobs report, indicators of monetary cooling are obvious. This consists of slower activity improvement and modest rises in unemployment costs, hinting at a much more restrained monetary outlook for the long run yr.

    Looking in advance, the anticipation of cost cuts in 2024 gives a constructive outlook. The Most vital Home finance mortgage Sector Survey index by Freddie Mac, which stood simply above 7% not way back, is predicted to drop much more, delivering reduction to level-delicate homebuyers.

    Evergreen Property Financial loans echoes the sentiment of Realtor.com Chief Economist Danielle Hale, anticipating residence finance mortgage charges to drop to round 6.5% by calendar year-conclusion 2024. This reduce would enormously acquire all these with current high-fee mortgages, opening up alternate options for refinancing and elevated affordability.

    Michele Raneri, VP of U.S. analysis and consulting at TransUnion, highlights the potential private financial savings for owners with a quantity fall to five.5%. This might imply vital month to month value financial savings, releasing up means in a big value tag-of-living environment.

    In conclusion, the Fed’s steady tactic and future price cuts are observed as a optimistic development by Evergreen Household Loans and different sector gamers, paving the way in which for a much more vibrant housing sector in 2024.

    Resource: HousingWire

    &#13

  • The concealed costs of acquiring a residence

    There are a quantity of concealed charges that you need to must element in when it arrives to buying a dwelling, this sort of as property finance mortgage and valuation charges.

    If you might be a to start out with-time purchaser taking a look at homes costing fewer than £425,000, understand that you aren’t presently liable to spend stamp obligation.

    In this text we define what they’re and clarify:

    You might presumably need to undergo our guideline to buying your initially dwelling within the to start out with event.

    Female first-time buyer at home in kitchenPurchasing a home will include concealed additional costs

    1. Broker charges

    As a 1st-time purchaser you may gain advantage from using an unbiased dwelling finance mortgage dealer who can support you wade by means of quite a few of the distinctive items accessible.

    Broker fees can selection from £300 to £1,000. Having stated that, some current a no price help as they make their {dollars} from the fee they obtain from the home mortgage mortgage supplier.

    Come throughout out additional: Need to I exploit a dwelling finance mortgage adviser?

    If you compensated on the prime finish of £1,000 for a mortgage dealer, you now have £9,000 nonetheless left above.

    2. Home mortgage fees

    When you arrange the mortgage, you might be almost certainly to must fork out an association cost. This might be as much as £2,000 however usually hovers near £1,000.

    You can incorporate this to the mortgage alone, however should you choose to fork out upfront, you’d will want £1,000. So factoring this in, you now have £8,000.

    3. Homebuyer examine

    A homebuyer examine will established you once more regarding £400 and £1,500. The extra you spend, the a lot extra depth you get.

    A mate of mine scrimped beneath and completed up with significantly excessive priced roof troubles.

    Let us value vary for a complete valuation that may set you again once more one other £1,000, leaving you with £7,000. 

    4. Valuation price

    The mortgage monetary establishment could maybe additionally cost a impartial valuation value to test the home is worthy of what you might be getting ready to pay out for it.

    A valuation price will established you again once more amongst £150 and £1,500.

    Let’s err on the facet of warning and value vary for a £1,000 cost. That gives you all the way down to £6,000. Are you sensation queasy nevertheless? Deep breath.

    Solicitors bills for getting a family are hefty and usually assortment involving £1,000 and £2,000. But you’ll will want a solicitor or conveyancer to assist you get hold of a home.

    Make assured you inquire about every particular person price that’s set in entrance of you so that you just acknowledge what you might be paying out for. A solicitor actually ought to offer you a break up down of the costs.

    Bear in mind that a exact-day financial institution switch value is charged when the home deposit is moved out of your solicitor to the vendor’s solicitor (£30).

    Set aside £1,000, leaving you with £5,000. But there are different charges chances are you’ll need to think about.

    6. Indemnity protection

    This presents you safety if there may be a problem with the property that would end result in council or authorized motion within the foreseeable future.

    For living proof, say you uncovered your aspiration dwelling and it had a loft conversion however the vendor didn’t have the fitting creating regulation certificates.

    Your solicitor can arrange indemnity insurance coverage insurance policies for this, which is a one particular-off cost for a plan that lasts eternally. 

    7. Transferring bills

    After you lastly have the brand new keys to your new family, you have to to contemplate concerning the bills of going.

    If you hire a van, this might established you again once more regarding £25 and £75 an hour.

    Of class should you don’t have considerably in the way in which of possessions, you could possibly discuss to partner and youngsters and good associates that will help you out to slash fees.

    8. Residence insurance coverage coverage

    This contains buildings insurance coverage coverage and contents insurance coverage.

    Properties insurance coverage insurance policies is one of probably the most essential issues to recollect. It is a necessity of most mortgage mortgage lenders and is more likely to price ticket you about £110 a 12 months. But once more that is depending on the worth of your property and the place it’s situated.

    Contents insurance coverage plan helps make notion to take into accounts as nicely. Just think about how out of pocket you’d be in case your carpets had been being ruined by a washer flood.

    Locate out concerning the residence protection suppliers.

    9. Servicing bills

    Keep away from wiping out your price financial savings wholly. Ideally you ought to take care of one factor once more and have a cushion in case some factor happens.

    If the boiler breaks, you can be grateful for that emergency fund.

    Purpose to have at minimal 3 months’ residing bills in an easy-entry financial savings account to tumble once more on.

    10. Home developments

    You could presumably need exhausting money to spruce up your new dwelling or buy family furnishings and important ticket merchandise these as ovens, hobs and fridges.

    Do not overlook to established some revenue apart for components like curtains, lamp shades and vegetation. 

    Locate out one of the best methods to incorporate value to your family

    Finally, deal with by yourself to a bottle of champagne to rejoice discovering the keys and turning out to be a property proprietor.

    Obtained a dilemma for our mentors? Drop us an e mail and we’ll get it answered.

    Crucial knowledge

    Some of the merchandise and options promoted are from our affiliate associates from whom we obtain cost. While we goal to attribute some of the best items on the market, we won’t assessment every merchandise on {the marketplace}.

    Study far more