Tag: college

  • New Jersey college asks bondholders to permit borrowing in opposition to home loan

    Rider University, a modest personal college outdoors of Trenton, New Jersey, is striving to elevate further money to help an ongoing liquidity crunch. 

    School officers requested bondholders for permission to borrow in opposition to the mortgage on the college’s key campus in Lawrenceville, New Jersey, in accordance to a disclosure see dated June 28 posted on the Municipal Securities Rulemaking Board’s EMMA web website. If accredited, the transfer would cost-free up substantially-essential funds for Rider in the brief-term. 

    “In the spirit of implausible partnership with our latest bondholders, we’ve got been in dialogue with them relating to this, and we perceive {that a} majority of them are prepared to consent to the modification,” defined Kristine Brown, a spokesperson for the school. 
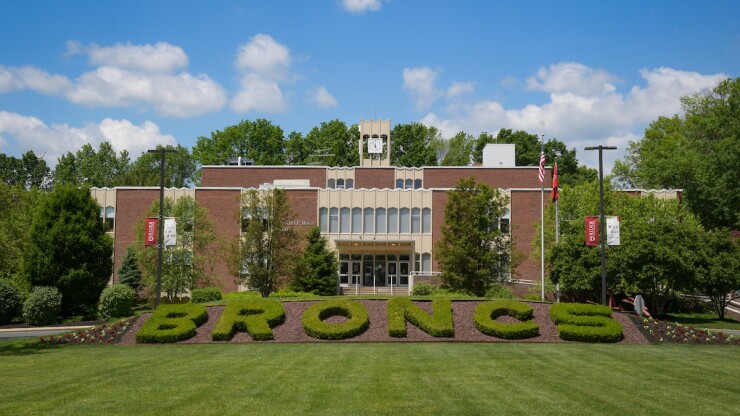
    Rider University building Rider College in New Jersey requested bondholders to approve supplemental borrowing to fund a cash turnaround plan.

    Rider College

    The proposal underscores the mounting worries smaller universities encounter to make ends meet up with as they deal with declining enrollments and mounting prices. People pressures have pushed faculties throughout the U.S. to shut or merge, whereas pushing different people into new strains of enterprise like on-line instruction, grownup finding out and monetizing real property. 

    Authentic property is mostly the most important asset a college owns. Rider’s principal campus, for example, was appraised at greater than $230 million, in accordance to Moody’s Scores. The college is proposing an modification to a latest financial institution loan and home loan association that might permit it to borrow an added $15 million of private debt on parity with liens on the home finance loan. 

    That amount would rise to $20 million if the college is prepared to present its Princeton campus, which on the time housed its famend choir software program. Initiatives to offload that genuine property have been mired in litigation, nevertheless the college is working in direction of a settlement, Brown acknowledged.

    Marketing campuses may be tough as a faculty’s closure can devalue actual property, and it could take time to receive a buyer. After Cazenovia College or college shut its doorways in upstate New York in mid-2023, its campus was leased to the state, which employed the companies to coach police cadets though it looked for a shopper. The campus was even now up on the market as of early July.

    Also, the modification would enable Rider to borrow $25 million of bank card debt subordinate to the mortgage loan liens. Employing the brand new borrowing functionality might vastly improve the college’s private debt. Rider for the time being has about $109 million of municipal bonds excellent, in accordance to information compiled by Bloomberg.

    Moody’s charges its current bonds Caa1, 7 methods beneath monetary funding grade. The scores company cited ongoing functioning deficits, that are anticipated to carry on by way of a minimum of 2025, and “severely” restricted liquidity in their rationale, in accordance to a January report. S&P World-wide Ratings prices the college’s bonds, issued by the Wisconsin-primarily primarily based Community Finance Authority and New Jersey Instructional Amenities Authority, BB with a harmful outlook. 

    Rider’s method to return to funds surpluses lays out some actions the college is getting to rightsize its funds. This ranges from makes an attempt to improve pupil recruitment, retention and vocation readiness to new parking service charges. In an April merely name with bondholders, college administration acknowledged the technique is on observe, and that applications and admissions improved 12 months round 12 months. 

    The college had a whole-time equal enrollment of three,731 in 2024, in accordance to S&P.

  • Constructing your kid’s credit history right after high college and building to get a property

    The residence mortgage worth pendulum swings nonetheless as soon as extra

    By Didier Malagies
    •
    18 Apr, 2024

    Be anticipating 2024 to be mildly higher than 2023 with mortgage mortgage charges slipping within the second fifty p.c of the 12 months, housing specialists opined in their forecasts on the conclusion of the 12 months. Cuts to the Federal funds worth (and subsequently to mortgage charges) are imminent, merchants enthused following December’s convention of the Federal Open Marketplace Committee by which committee associates predicted 3 degree cuts in 2024. Some specialists forecasted as a lot of as six cost cuts within the 12 months based mostly on this info. Level cuts are nonetheless coming, simply not in March , merchants and market gurus reasoned rather more not too long ago as the general economic system continued to function extremely sizzling. And now on the heels of research of extra sturdy than predicted positions progress and stickier than predicted inflation , the market’s shift from optimism to pessimism round degree cuts is full. Some even assume degree hikes simply earlier than degree cuts. The pessimism is apparent in mortgage mortgage charges. Freddie Mac‘s weekly Primary Home finance mortgage Market Survey is climbing once more to 7%. HousingWire’s House mortgage Level Heart , which depends on info from Polly, is presently above 7.2%. Charges had been being as lowered as 6.91% for Polly and 6.64% for Freddie as not way back as February. On Tuesday, they achieved 7.50% on Property finance mortgage News Each day, a superior for this 12 months. Property finance mortgage premiums maintain vital electrical energy within the housing market most significantly, superior charges exacerbate the present affordability catastrophe by walloping the acquiring electrical energy of would-be customers and discouraging some would-be sellers – folks with low, set-fee mortgages – from itemizing their properties, a drain on obtainable inventories. All this leaves housing execs after as soon as extra combating for his or her share of shrinking pies – as we’ve got seen with simply these days launched mortgage data and RealTrends Verified’s brokerage info , as successfully as additional dives on the brokerage landscapes in Jacksonville and San Diego . It is unsurprising, then, that actual property shares have skilled provided that the FOMC’s March meeting and the the most recent job and inflation tales. That options the nation’s main homebuilders (DR Horton and Lennar), mortgage mortgage originators (United Wholesale Home finance mortgage and Rocket Mortgage), brokerages (Anywhere and Compass) and family search portals (Zillow and CoStar, which owns Residences.com). There are different dynamics at carry out for a few of these organizations, even so. The brokerages are additionally contending with the rule modifications included in a proposed settlement by the Countrywide Affiliation of Realtors some buyers additionally think about folks rule alterations profit CoStar at the price of Zillow . UWM, within the meantime, is contending with a scathing investigative report by a hedge-fund-affiliated information company whose hedge fund shorted UWM and went lengthy on Rocket additionally it is working with pending litigation . UWM denies the allegations produced within the report.  Large mortgage mortgage charges, a lot much less property finance mortgage apps and a lot much less residence income are nonetheless not the one penalties housing professionals might see from a additional prolonged high-price ambiance. There are additionally spillover results from different industries, significantly enterprise severe property. Regional banking establishments – which traditionally have been large family property finance mortgage originators – went giant on business real property loans as higher monetary establishments scaled once more on this spot in current a number of years. That elevated their publicity to downtown workplace towers, which have discovered an exodus of tenants and a bottoming out of appraised values simply as a doc $2.2 trillion in industrial genuine property credit card debt arrives owing greater than the upcoming a number of a few years. That ties up money that would in any other case circulate to residential mortgages and in some circumstances stresses banks like New York Community Lender, guardian of Flagstar Lender — the Seventh-major lender originator of family residence loans, Fifth-largest sub-servicer of mortgage loans and the 2nd-biggest home mortgage warehouse mortgage firm within the area. Homebuilders, additionally, actually really feel the outcomes of prolonged superior charges. Even although homebuilder confidence is nonetheless up considerably provided that earlier slide, new housing begins are slowing . The dim potential clients for homebuyers have turned some consumers to the nascent create-to-lease sector , essentially a guess that vital expenses are beneath to proceed to be for prolonged sufficient that would-be purchasers are actually would-be renters.

  • Era X retirement potential customers challenged by college student loan financial debt

    The oldest associates of Technology X — the cohort
    most business specialists define as having been born amongst 1965 and 1980 — will shortly be confronted with financial troubles that might have notable impact on their potential to protect for retirement: the resumption of student loan funds. As pandemic-period fascination and fee discount is ready to run out this coming slide, which tends to make long term making ready further troublesome,
    in accordance to a report from the New York Situations.

    “As of the first quarter of this yr, members of Era X held a couple of quarter of the nation’s excellent $1.6 trillion in pupil financial loan financial debt — to the tune of nearly $49,000 for every borrower, in response to TransUnion, the credit score reporting bureau,” the Moments famous.

    The issues are removed from remoted to individual customers of Gen X, in response to specialists interviewed by the Moments.

    “In primary, now we have noticed customers concentrating much more on private financial savings and never concentrating on these college student loans, ”stated Trent Graham, a financial counselor at GreenPath Economic Wellness to the Instances. “They genuinely didn’t have a put together to take care of these college student financial loans.”

    Graham described that loads of Gen X college student private loan debtors had been being “stunned” by how rather a lot the private debt may develop, as these loans have usually continued to accrue curiosity even when positioned in forbearance or deferment, though deferment of sponsored loans don’t accrue added need as famous by the Situations. Nevertheless, pandemic-period pauses additionally paused need accruals — an unusually excessive stage of discount for these sorts of loans — along with suspending anticipated month-to-month funds.

    A large affect of scholar loan debt is that debtors of those financial loans are considerably much less possible to save lots of absolutely anything for retirement, in accordance to Matt Rutledge, an affiliate professor of the observe of economics at Boston College or college.

    “It’s the existence of any financial loan in any respect when you’ve got a financial loan, you nearly definitely really feel of your self as not proudly owning the bandwidth to think about about retirement nonetheless,” he stated, noting that 65 million customers of Technology X will see an outsized impression at the same time as they get to the height of their earnings potential.

    “For women and men who’ve been carrying these financial loans for quite a lot of a very long time, they possibly didn’t preserve considerably to get began with, so that you truly are utilizing absent a few of their best saving a number of years,” Rutledge further.

    Technology X is already fairly bank card debt-burdened. According to info from LendingTree cited by the Periods, the Generation X cohort has probably the most debt in situations of the 2 home loan and non-house loan obligations, averaging to a stage of roughly $167,000 for each borrower.


    The oldest associates of Era X will all remodel 58 by the conclude of 2023. This implies that the cohort is 5 yrs away from
    qualifying for a Residence Equity Conversion Mortgage (HECM), however chosen older customers of the expertise by now qualify for certain proprietary reverse mortgage loan loans with a naked minimal qualifying age of 55.