Tag: business

  • Money laundering is high business priority – Mortgage Finance Gazette

    The impression of cash laundering is vital because it underpins and permits most types of organised crime, permitting crime teams to additional their operations and conceal their belongings. The National Crime Agency (NCA) estimates that there could possibly be a whole lot of billions of kilos laundered within the UK yearly.

    Stephen-Ward.jpg

    As such cash laundering continues to be a high business priority throughout all sectors, much more so for these concerned within the shopping for and promoting of property, with the property sector remaining notably weak as a result of giant quantities of cash which might be laundered in a single transaction.

    So, what’s being achieved to fight cash laundering? The Legal Services Affinity Group (LSAG) is made up of each regulatory and consultant our bodies for authorized companies within the UK. It has produced steering on the anti-money laundering (AML) rules, which has been accredited by HM Treasury and is the supply of official steering for these within the authorized sector.

    In December, LSAG revealed an vital replace to its anti-money laundering (AML) steering. Unusually, they took the step this time of publishing meant modifications to the identification and verification facet of consumer due diligence because of simply how basic this facet of AML management is.

    These modifications will solely come into impact if HM Treasury approval is granted. The proposed modifications will be sure that not only a consumer’s identification is verified however that authorities paperwork verifying the identify, tackle and date of delivery of the useful proprietor are additionally provided. These heightened checks goal to clamp down on properties being bought by an ‘agent’ who merely fronts the transaction however isn’t the beneficiary of it.

    In January, schedule 3ZA, which was the previous statutory listing of High Risk Third Countries (HRTC) was repealed. HRTCs will now be outlined as those that are topic to elevated monitoring (‘gray listing’) or to a name for motion (‘blacklist’) by the worldwide Financial Action Task Force (FATF).

    The FATF is the worldwide cash laundering and terrorist financing watchdog. It units worldwide requirements that goal to forestall unlawful actions and the hurt they trigger to society. It’s extremely vital that each one actors concerned in property transactions be they lenders, conveyancers or property brokers maintain themselves abreast of those modifications.

    Sector threat evaluation

    As a regulator, it is our obligation to evaluate the cash laundering threat within the sector we regulate – the authorized sector. Annually, we run this train to assist us and the practices we regulate establish and tackle altering threat successfully. This 12 months noticed us introducing 4 additions to the dangers for the authorized sector:

    Proliferation financing – this shaped a part of our threat evaluation this 12 months, and we deemed there to be an publicity threat and have included it within the sectoral threat evaluation.
    Emerging dangers – we now have launched info on Electronic Money Institutions (EMIs) which we take into account to be an rising threat in AML.
    Client threat issue – we now have launched a brand new part referred to as “period and nature of consumer relationships” to cowl not solely data of the consumer but additionally conditions of high consumer turnover, which is a recognised consumer threat issue.
    Changes flowing from the 2023 thematic assessment of Trust and Company Service Provision – the evaluation now displays our conclusions on threat arising from TCSP within the CLC-regulated sector.

    AML toolkit

    Our AML toolkit is out there to anybody by means of our web site and supplies steering and recommendation to CLC regulated corporations on the way to stay compliant with up-to-date AML rules. There are a variety of sources resembling an AML threat evaluation template, which might be designed to assist practices meet AML necessities.

    While cash laundering does stay a menace to companies, it’s vital to watch out for the vary of indicators that may assist establish potential cash laundering, and the necessities on companies to make sure they adhere to probably the most present AML steering.

    Remember, when you change into suspicious of cash laundering exercise you might have an obligation to lift it along with your nominated cash laundering officer (MLO) who can advise on submitting a suspicious exercise report (SAR) by means of the National Crime Agency’s new SAR portal.

    Stephen Ward is director of technique and exterior relations on the Council for Licensed Conveyancers

  • Construction firms top business failures   – Mortgage Strategy

    Construction failures in England and Wales jumped 17% within the 12 months to March from 12 months in the past, the best of any business, in keeping with official knowledge.  

    This sector noticed 4,274 firms exit of business, in keeping with the Insolvency Service, adopted by the wholesale and retail commerce and motor repairs sector, which noticed failures rise 16% and lodging and meals providers companies, up 15%.  

    Overall, a price of 57 per 10,000 corporations entered insolvency within the 12 months to the top of April, in comparison with 52.6 per 10,000 corporations that failed over the earlier 12 months.  

    The service stated that the “variety of firm insolvencies remained a lot greater than these seen each in the course of the Covid-19 pandemic and between 2014 and 2019”.  

    RSM nationwide head of building Kelly Boorman factors out that the constructing business is saddled with legacy contracts and excessive prices, with extra ache to come back.  

    She says: “Many building companies are nonetheless recovering from legacy contracts, procured as fastened value contracts pre-Covid and topic to litigation.   

    “The business has been critically impacted by inflationary charges and labour prices, particularly within the final 12 months. This, coupled with an accelerating pipeline, is inflicting extra challenges as there isn’t the supply of working capital for companies to hold out work, which is a key contributor to rising building insolvencies.   

    “The business is caught between a rock and a tough place, and companies want assist creating smart development to forestall overtrading, whereas navigating ongoing points with legacy contracts.   

    “With the danger of overtrading rising, plus squeezed provide chains and labour shortages because the market picks up, there are additional challenges on the horizon as labour prices will go up, including extra stress on companies and their margins.   

    “As the housing market additionally picks up all year long, it will pull on materials prices and labour.”  

    Boorman provides: “Looking forward to the third quarter, we’re prone to see building insolvencies speed up, as a result of added pressure out there as companies wrestle with a scarcity of working capital, accrued debt and falling cashflows caused by legacy contracts.   

    “In addition, there’s rising uncertainty round future spending because of the political surroundings and looming common election, which is inflicting considerations across the provide chain, the federal government contracts that might be accessible, in addition to the time to award and mobilise these initiatives.” 

  • Construction firms lead business insolvencies   – Mortgage Finance Gazette

    Construction failures in England and Wales jumped 17% within the yr to March from 12 months in the past, the best of any trade, based on official knowledge.  

    self-build-bricks-house-wall-620x330.jpg

    This sector noticed 4,274 firms exit of business, based on the Insolvency Service, adopted by the wholesale and retail commerce and motor repairs sector, which noticed failures rise 16% and lodging and meals companies companies, up 15%.  

    Overall, a charge of 57 per 10,000 corporations entered insolvency within the yr to the tip of April, in comparison with 52.6 per 10,000 corporations that failed over the earlier 12 months.  

    The service stated that the “variety of firm insolvencies remained a lot greater than these seen each through the Covid-19 pandemic and between 2014 and 2019”.  

    RSM nationwide head of development Kelly Boorman factors out that the constructing trade is saddled with legacy contracts and excessive prices, with extra ache to come back.  

    She says: “Many development companies are nonetheless recovering from legacy contracts, procured as fastened price contracts pre-Covid and topic to litigation.   

    “The trade has been severely impacted by inflationary charges and labour prices, particularly within the final yr. This, coupled with an accelerating pipeline, is inflicting extra challenges as there isn’t the provision of working capital for companies to hold out work, which is a key contributor to rising development insolvencies.   

    “The trade is caught between a rock and a tough place, and companies want assist creating smart progress to stop overtrading, whereas navigating ongoing points with legacy contracts.   

    “With the chance of overtrading rising, plus squeezed provide chains and labour shortages because the market picks up, there are additional challenges on the horizon as labour prices will go up, including extra strain on companies and their margins.   

    “As the housing market additionally picks up all year long, it will pull on materials prices and labour.”  

    Boorman provides: “Looking forward to the third quarter, we’re more likely to see development insolvencies speed up, as a consequence of added pressure out there as companies wrestle with a scarcity of working capital, amassed debt and falling cashflows caused by legacy contracts.   

    “In addition, there’s rising uncertainty round future spending because of the political surroundings and looming normal election, which is inflicting considerations across the provide chain, the federal government contracts that will probably be obtainable, in addition to the time to award and mobilise these tasks.” 

  • Surge in business transacted through OMS platform – Mortgage Finance Gazette

    Loan origination platform OMS has seen a 30% enhance in mortgage completions throughout the first quarter of this 12 months, when in comparison with the identical interval final 12 months.

    technology3-620x330.jpg

    This end-to-end platform is utilized by banks, constructing societies and specialist lenders throughout a variety of product areas, together with residential loans, buy-to-let, second cost mortgages, fairness launch, bridging, business plus basic insurance coverage, and safety.

    OMS Originations has  built-in with various suppliers, together with Ignite, Submissions Brain, The Source, Twenty7Tec, iPipeline, Hometrack, Experian, Equifax, Uinsure, Air Sourcing and Knowledge Bank – to offer customers with product sourcing, safety sourcing and standards looking providers.

    It mentioned this sturdy enhance in transactional volumes mirrored its position on the core of dealer processes. OMS has now attained ISO 27001 certification for its CRM platforms. Last month it launched ‘OMS Originations’ which streamlines the entire end-to-end mortgage origination journey supporting prompt decisioning, product engine, bespoke underwriting processing plus second and third line audit performance.

    A customisable dashboard permits lenders to create environment friendly workflows to fulfill quite a lot of borrowing necessities with out having to endure prolonged improvement instances or extra prices.

    One Mortgage System managing director Neal Jannels says: “2024 has proved to be an extremely busy interval, demonstrated by this substantial uplift in transactional business throughout the platform, a raft of latest integrations and in the onboarding of an ever-growing variety of customers.

    “In addition, the introduction of our Originations platform has been an extended and detailed course of in phrases of testing, creating and implementation.”

    He provides that this development show the size of the urge for food from the lending neighborhood for such a proposition and added that the corporate will proceed to strengthen its providing in key areas.

  • How To Estimate A Business Home loan Fee?

    Fed retains premiums fixed for the sixth straight time

    By Didier Malagies
    •
    02 Might, 2024

    The Federal Reserve ’s Federal Open up Marketplaces Committee (FOMC) taken care of its limited-expression plan curiosity cost steady at a spread of 5.25% to five.5% for a sixth consecutive convention on Wednesday. “The Committee doesn’t hope it will likely be appropriate to decrease the think about array till ultimately it has attained increased self esteem that inflation goes sustainably towards 2%,“ the FOMC stated in a press release. “In addition, the Committee will proceed minimizing its holdings of Treasury securities and firm debt and firm mortgage‑backed securities.“ Throughout their previous assembly in March , policymakers indicated that they nonetheless envisioned three fascination quantity cuts in 2024. But with inflation remaining sticky and unemployment staying beneath 4%, these expectations are getting much less very probably. Recent financial particulars has not specified the Fed self esteem that inflation will proceed to drop. Strong inflation particulars within the to begin with quarter, coupled with a powerful labor market place , have postponed anticipations for the initially Fed cost slice. In April, Fed Chairman Jerome Powell, talking on the Washington Forum , manufactured it obvious that price cuts weren’t imminent due to to the ability of the monetary state. The financial local weather has preserved surprising momentum regardless of the latest quantity of quick-term prices. With the unemployment stage beneath 4%, companies are steadily incorporating staff and genuine wage progress is observable as inflation eases. Even although upward actions in inflation are noteworthy, appreciable growth towards the Fed’s 2% give attention to has been created. “It’s unlikely that the longer term protection stage shift will likely be a hike,” Powell instructed journalists on Wednesday all through the FOMC’s press assembly. “In get to hike the costs, we might need to see persuasive proof that our coverage stance is just not adequately restrictive to supply inflation sustainably all the way down to 2% above time. That is just not what we’re viewing on the minute.” Though Powell emphasised the unlikelihood of future payment hikes, he additionally remained obscure concerning the Fed’s potential rate of interest trajectory. “We didn’t see progress within the to begin with quarter. It appears that it’ll simply take for an extended interval for us to achieve that stage of self-assurance,” Powell reported. “I don’t understand how intensive it’ll purchase. … My personal forecast is that we’ll start to see progress on inflation this 12 months. I actually have no idea that it will likely be ample to slash premiums we should allow the information lead us on that.” In a brand new enhancement, the Fed launched an easing of its quantitative tightening coverage. Setting up in June, the amount-placing physique will lowered the roll-off cost of its Treasury securities from $60 billion to $25 billion for each month. This signifies that although the Fed is not going to get began selling Treasurys in June, it’ll allow a lot much less of them to mature. It is not going to alter its roll-off stage for property finance loan-backed securities (MBS), which is able to stay at $35 billion for every month, in accordance to Xander Snyder, senior skilled genuine property economist at Initially American. “The FOMC didn’t rework the continued passive roll-off of its MBS holdings however did discover that any prepayments exterior of the persevering with $35 billion cap could be reinvested in Treasuries,” Mike Fratantoni, senior vice chairman and chief economist for the Mortgage Bankers Affiliation, talked about in a press release. “We expect house loan costs to drop afterwards this 12 months, however not as a lot or as quick as we beforehand skilled predicted.” In addition, Powell reiterated the Fed’s dedication to carrying forward the Basel III endgame legal guidelines in a means which is devoted to Basel and in addition much like what the jurisdictions in different nations are executing. Because the March FOMC assembly, Freddie Mac’s bizarre 30-yr set mortgage loan value has better from 6.74% to 7.17%. Before the upcoming FOMC assembly on June 12, two supplemental inflation readings are anticipated. “While it’s a chance, I actually don’t think about that we’ll see a terrific deal modify in mortgage loan prices adhering to this Fed meeting, given that the Fed has been able to let the information lead at this stage within the cycle,” Real property agent.com predominant economist Danielle Hale talked about in a assertion. “In purchase to see mortgage premiums drop much more significantly, the Fed might want to see extra proof that inflation is slowing.”  For homebuyers and sellers, this implies that housing affordability will carry on being a major thought, maybe driving family buys in economical marketplaces, predominantly within the Midwest and South, in line with Hale.

  • What Business Real Estate Loans Are For Modest Group?

    Fed retains charges continuous for the sixth straight time

    By Didier Malagies
    •
    02 May, 2024

    The Federal Reserve ’s Federal Open up Markets Committee (FOMC) taken care of its shorter-time interval protection curiosity payment regular at a spread of 5.25% to five.5% for a sixth consecutive meeting on Wednesday. “The Committee doesn’t hope it will likely be very best to minimize the deal with vary proper till it has acquired bigger self-assurance that inflation is shifting sustainably towards 2%,“ the FOMC claimed in a press release. “In addition, the Committee will go on lessening its holdings of Treasury securities and company monetary debt and firm mortgage‑backed securities.“ Throughout their earlier meeting in March , policymakers indicated that they nonetheless envisioned three curiosity payment cuts in 2024. But with inflation remaining sticky and unemployment remaining beneath 4%, these anticipations have gotten a lot much less possible. Modern financial particulars has not supplied the Fed self esteem that inflation will go on to drop. Sturdy inflation information within the preliminary quarter, coupled with a strong labor market , have postponed anticipations for the primary Fed worth scale back. In April, Fed Chairman Jerome Powell, talking on the Washington Discussion board , designed it obvious that payment cuts had been not imminent as a result of energy of the financial local weather. The monetary state has preserved astonishing momentum even with the current diploma of small-term prices. With the unemployment quantity down under 4%, corporations are steadily incorporating employees and actual wage progress is observable as inflation eases. While upward actions in inflation are noteworthy, appreciable progress towards the Fed’s 2% goal has been made. “It’s unlikely that the longer term plan cost transfer will probably be a hike,” Powell suggested journalists on Wednesday all through the FOMC’s push conference. “In get to hike the costs, we must must see persuasive proof that our protection stance isn’t sufficiently restrictive to deliver inflation sustainably all the way down to 2% round time. Which isn’t what we’re viewing on the on the spot.” When Powell emphasised the unlikelihood of upcoming charge hikes, he additionally remained obscure concerning the Fed’s future fascination stage trajectory. “We didn’t see growth within the to begin with quarter. It appears that it’ll take lengthier for us to entry that difficulty of confidence,” Powell stated. “I have no idea how in depth it is going to select. … My customized forecast is that we are going to begin to see progress on inflation this calendar yr. I actually have no idea that it will likely be ample to slash costs we must allow the information information us on that.” In a brand new growth, the Fed declared an easing of its quantitative tightening coverage. Starting in June, the fee-setting system will decrease the roll-off cost of its Treasury securities from $60 billion to $25 billion for every month. This implies that although the Fed won’t begin selling Treasurys in June, it is going to allow much less of them to skilled. It won’t alter its roll-off stage for property finance loan-backed securities (MBS), which is able to keep at $35 billion for every month, based on Xander Snyder, senior enterprise true property economist at To begin with American. “The FOMC didn’t alter the continued passive roll-off of its MBS holdings however did bear in mind that any prepayments previous the persevering with $35 billion cap could be reinvested in Treasuries,” Mike Fratantoni, senior vice chairman and chief economist for the Home finance mortgage Bankers Affiliation, claimed in a press release. “We count on residence finance mortgage prices to drop later this yr, however not as a lot or as quickly as we beforehand had predicted.” In addition, Powell reiterated the Fed’s dedication to carrying forward the Basel III endgame polices in a method which is trustworthy to Basel and likewise much like what the jurisdictions in different nations are finishing up. Due to the actual fact the March FOMC meeting, Freddie Mac’s regular 30-year set home mortgage quantity has better from 6.74% to 7.17%. In advance of the next FOMC assembly on June 12, two additional inflation readings are anticipated. “While it’s a chance, I actually do not imagine that we’ll see considerably remodel in home mortgage premiums subsequent this Fed assembly, as a result of reality the Fed has been eager to allow the small print direct at this stage within the cycle,” Real property agent.com chief economist Danielle Hale said in a assertion. “In order to see residence finance mortgage prices drop additional appreciably, the Fed would require to see much more proof that inflation is slowing.”  For homebuyers and sellers, this means that housing affordability will carry on being a finest consideration, most likely driving home purchases in moderately priced marketplaces, predominantly within the Midwest and South, based on Hale.

  • Need to grow your business enterprise with cash, inventory, new making

    Fed holds premiums fixed for the sixth straight time

    By Didier Malagies
    •
    02 May maybe, 2024

    The Federal Reserve ’s Federal Open up Marketplaces Committee (FOMC) managed its small-phrase plan fascination cost steady at a array of 5.25% to 5.5% for a sixth consecutive assembly on Wednesday. “The Committee doesn’t anticipate will probably be preferrred to lower the focus on selection till lastly it has acquired elevated self-confidence that inflation is relocating sustainably towards 2%,“ the FOMC mentioned in a assertion. “In addition, the Committee will go on chopping down its holdings of Treasury securities and company private debt and company mortgage‑backed securities.“ Through their earlier meeting in March , policymakers indicated that they however envisioned just a few rate of interest cuts in 2024. But with inflation remaining sticky and unemployment retaining beneath 4%, these anticipations have gotten a lot much less almost certainly. Modern monetary data hasn’t provided the Fed confidence that inflation will go on to drop. Robust inflation data within the initially quarter, coupled with a strong labor business , have postponed anticipations for the first Fed value slice. In April, Fed Chairman Jerome Powell, talking on the Washington Discussion board , made it clear that cost cuts weren’t imminent due to the power of the monetary system. The financial system has preserved shocking momentum regardless of the present stage of brief-phrase prices. With the unemployment payment beneath 4%, suppliers are steadily incorporating staff and precise wage growth is observable as inflation eases. Whilst upward actions in inflation are noteworthy, sizeable progress in the direction of the Fed’s 2% goal has been designed. “It’s unlikely that the next plan cost switch might be a hike,” Powell instructed journalists on Wednesday throughout the FOMC’s press assembly. “In get to hike the premiums, we would wish to see persuasive proof that our protection stance isn’t sufficiently restrictive to carry inflation sustainably down to 2% over time. That’s not what we’re seeing on the minute.” Though Powell emphasised the unlikelihood of upcoming cost hikes, he additionally remained imprecise in regards to the Fed’s potential curiosity stage trajectory. “We didn’t see improvement within the initially quarter. It seems that it’ll simply take longer for us to attain that time of confidence,” Powell mentioned. “I actually have no idea how lengthy it should contemplate. … My explicit forecast is that we are going to start to see improvement on inflation this 12 months. I don’t know that will probably be adequate to scale back prices we may have to allow the data lead us on that.” In a new enchancment, the Fed launched an easing of its quantitative tightening coverage. Commencing in June, the charge-location human physique will decreased the roll-off cost of its Treasury securities from $60 billion to $25 billion per thirty day interval. This implies that while the Fed is not going to begin off selling Treasurys in June, it should allow fewer of them to skilled. It is not going to alter its roll-off quantity for home loan-backed securities (MBS), which can proceed to be at $35 billion for every thirty day interval, in accordance to Xander Snyder, senior skilled true property economist at First American. “The FOMC didn’t modify the continuing passive roll-off of its MBS holdings however did notice that any prepayments over and above the persevering with $35 billion cap could be reinvested in Treasuries,” Mike Fratantoni, senior vp and major economist for the Mortgage mortgage Bankers Association, defined in a assertion. “We anticipate home mortgage charges to fall in a while this yr, however not as a lot or as fast as we previously skilled predicted.” In addition, Powell reiterated the Fed’s motivation to carrying ahead the Basel III endgame polices in a approach that’s devoted to Basel and in addition equal to what the jurisdictions in different nations are performing. Due to the very fact the March FOMC meeting, Freddie Mac’s common 30-year fixed house mortgage quantity has larger from 6.74% to 7.17%. Ahead of the long run FOMC convention on June 12, two additional inflation readings are envisioned. “While it’s a danger, I actually don’t contemplate that we’ll see a lot modify in house finance mortgage costs adhering to this Fed meeting, given that the Fed has been inclined to enable the knowledge direct at this section within the cycle,” Realtor.com major economist Danielle Hale defined in a press release. “In purchase to see mortgage mortgage prices drop far more noticeably, the Fed will need to see additional proof that inflation is slowing.”  For homebuyers and sellers, this means that housing affordability will proceed being a significant consideration, doubtlessly driving house purchases in economical marketplaces, predominantly within the Midwest and South, in accordance to Hale.

  • Business enterprise turnover retains steady | Australian Broker Information

    Company turnover retains steady | Australian Broker News

    News

    Business enterprise turnover holds steady

    Modest development in March

    Business turnover holds steady

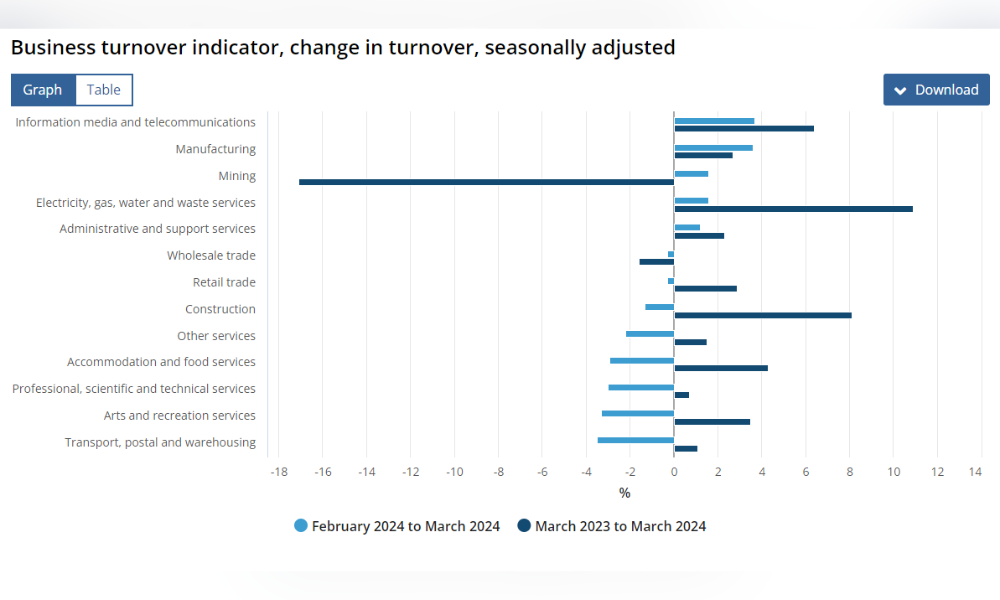
    Fresh new Ab muscle groups information indicated a slight decline of .1% in firm turnover in sample phrases for March.

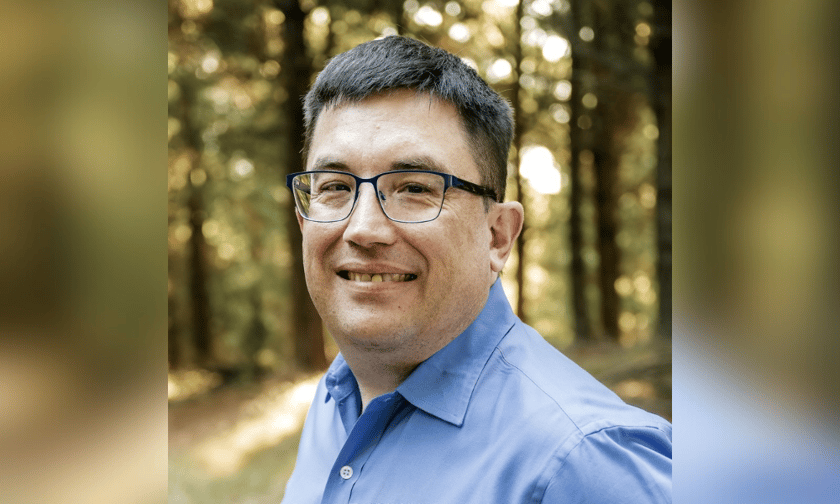
    “In sample phrases, the 13-sector mixture measure of firm turnover has been flat since Oct 2023,” Robert Ewing (pictured above), Abdominal muscle groups head of enterprise research.

    Company sectors current divergent tendencies

    While the usually group turnover confirmed minimal modify, chosen industries expert sizeable development.

    “The strongest rises had been from the knowledge and information media and telecommunications market, up 3.7%, manufacturing with an increase of three.6%, and mining, which grew 1.6%,” Ewing talked about in a media launch.

    The increase within the particulars media and telecommunications sector was principally pushed by larger membership revenues within the publishing subdivision.

    Conversely, the transport, postal, and warehousing enterprise seen essentially the most important lower, partly reversing a major enhance from February.

    Once-a-year enterprise turnover variations

    When evaluating calendar year-over-calendar yr particulars, group turnover in March was greater for 11 of the 13 industries tracked by the indicator.

    Notably, {the electrical} vitality, gasoline, h2o, and waste services market noticed essentially the most important yearly enhance at 10.9%, adopted by growth at 8.1%, and knowledge and information media and telecommunications at 6.4%.

    In the meantime, mining recorded a vital yearly lower of 17.1%, which dampened the general beneficial common efficiency.

    Get the most well-liked and freshest mortgage mortgage information shipped appropriate into your inbox. Subscribe now to our FREE day-after-day publication.

    Keep up with the latest information and conditions

    Sign up for our mailing record, it’s freed from cost!

  • FAQ – Little Enterprise Exit Strategies: how to structure a business enterprise acquisition.

    The Tiny Small business Administration (SBA) 504 monetary mortgage is a prolonged-time period funding device for rising modest enterprises.

    In this monetary state, a great amount of firm proprietors are contemplating about retirement. You might probably be a individual of them. Possibly you occur to be pondering if it’s time to promote your company, or in all probability you’ve got been approached by a shopper who would really like to acquire it. In probably situation, it really is important to know that when it arrives time to execute the deal, the perfect manner to go is via a industrial financial institution mortgage.

    I do know what you occur to be contemplating: why would I need a financial institution related in my sale? It is actually not like they’ve any pores and pores and skin within the sport—they’re simply heading to take their lower and depart me with no matter they actually really feel like giving me on the finish of the day. But that is actually a misunderstanding about how skilled loans function: as prolonged as your small business is essential and you have got acquired an educated financial advisor in your side, banks will do something attainable to help make the provide transpire for each individual concerned—together with you.

    That is since industrial loans normally are usually not only for buying and providing companies—they will also be utilised for many different wants, like retirement arranging and property organizing. If you select to promote your business to an worker or member of the family, as an illustration, a skilled mortgage may be utilized by your purchaser (and even your self) as a part of an property put together so you’re secured.

    A monetary establishment will lend your shopper the {dollars} centered on their means to pay out it once more pretty than on irrespective of if they’ve enough funds within the financial institution proper now. The various is you having on the chance and hope that you’re compensated once more.

    This answer is barely obtainable if there’s a mortgage supplier keen to finance the transaction though, so make optimistic that there are mortgage corporations who will carry out with potential patrons in your drawback proper earlier than you begin out down this route.

    The ultimate place to start is by giving a single of our advisors a name,

    (727) 784-5555

    . We will wander you as a results of all of your options and help you match technique your exit method. Or use the kind underneath to examine with us a concern. 

    Have A Dilemma?

    Use the variability beneath and we’ll give your our professional options! Or scroll down for a lot extra FAQs and Responses.

  • Favourable progress for Rightmove’s home finance loan small business – Mortgage Technique

    Rightmove has reported a constructive start to the yr for its home finance loan business enterprise in its latest investing replace. 

    In its very first quarter replace Righmove claimed that AI-led optimisation was encouraging to extend the mortgage loan journey for consumers, foremost to significantly better outcomes for its companion companies within the home loan business. 

    Rightmove launched its very first dealer home finance loan merchandise previous 12 months, by making it attainable for consumers to accessibility home finance loan ideas on account of its portal. It suggests this has served drive  a 130% enhance in its mortgage business enterprise.

    Its mortgage enterprise continues to be one in all Rightmove’s strategic progress places. It said this, together with its industrial and rental professional companies firms are “performing consistent with expectations”. 

    Its replace said that it has additionally been a key investor in Coadjute — a platform that goals to digitise the residence-moving system and to make it extra environment friendly for patrons, brokers and the broader discipline. Rightmove is a co-trader alongside Lloyds Banking Group, Nationwide and NatWest.

    Regardless of the challenges within the housing market place, Rightmove talked about it retains its main placement within the housing getting sector. It said that 80% of all shopper time invested on United kingdom property portals is on Rightmove, including that customers carry on being very engaged: with 8m opting into its advertising and promoting. Its replace claimed it additionally despatched 19m potential prospects to agent associates. 

    In simply its property company enterprise, Rightmove mentioned web membership enhanced by 250 contemplating that the 2023 calendar yr end. It reported this maximize is useful for earnings and income, and presents better shopper different on its website. 

    Rightmove defined it was optimistic a couple of housing sector restoration, with its most newest residence promoting value index displaying the standard asking charges for property continued to edge upwards, with once-a-year home promoting value development of 1.7%,  the most effective for a calendar yr. 

    Rightmove CEO Johan Svanstrom claims: “Overall, we proceed to depend on a better yr for the British isles home sector in 2024 than in 2023.  Inside that, we see various dynamics all through the various segments that we serve, with distinctive energy in resales.”