Tag: business news

  • Weekly home loan demand drops as desire prices increase once again

    Weekly mortgage demand drops as interest rates rise again

    Home loan desire fees rose earlier week for the preliminary time in 3 weeks. As a consequence, total mortgage loan software quantity dropped 1.6% in distinction with the sooner 7 days, in line with the Mortgage loan Bankers Association’s seasonally adjusted index.

    The abnormal contract desire value for 30-12 months mounted-price home loans with conforming financial institution loan balances ($766,550 or much less) elevated to six.97% from 6.84%, with components lowering to .64 from .65 (which embody the origination price) for loans with a 20% down fee. That was the weekly frequent, however an extra index from Home finance loan Information Every day, which appears to be at day-to-day premiums, skilled the 30-yr fastened property finance loan transferring again about 7% earlier Thursday.

    “Home loan prices larger ultimate week as incoming details confirmed inflation was proceed to hotter than envisioned, which stoked points concerning the timing and extent to which the Fed could effectively be capable of reduce the fed money fees this yr,” talked about Joel Kan, MBA’s vice chairman and deputy chief economist.

    Much more CNBC info on housing

    Programs to refinance a dwelling financial institution loan, that are most delicate to weekly value adjustments, fell 3% as compared with the earlier 7 days and had been additionally 3% lowered than the similar week one explicit 12 months up to now.

    Purposes for a home loan to acquire a family fell 1% for the week and ended up 14% decreased than the precise 7 days only one calendar yr up to now. Invest in desire is just not as delicate to tiny strikes in fascination charges. Desire can also be arising in direction of substantial fees and fairly restricted present.

    “With housing provide lowered and prices superior, the everyday loan dimensions for purchase packages elevated to the best stage as a result of May 2022,” Kan additional.

    Costs are actually within the lowered 7% vary, simply shy of the 2024 ceiling hit three months again. That ceiling may both proceed being in location or be damaged Wednesday with the most recent Federal Reserve announcement on curiosity prices and the following push conference with Fed Chair Jerome Powell.

    “The market is presently anticipating a bit little bit of an unfriendly change this time throughout, however the actuality may conveniently differ from expectations. To no matter extent it does, home loan charges are more likely to make bigger strikes, for improved or worse,” wrote Matthew Graham, chief working officer of Home loan Information Everyday.

    Do not skip these exclusives from CNBC Pro

  • The Fed holds fascination charges regular. What that suggests for your cash

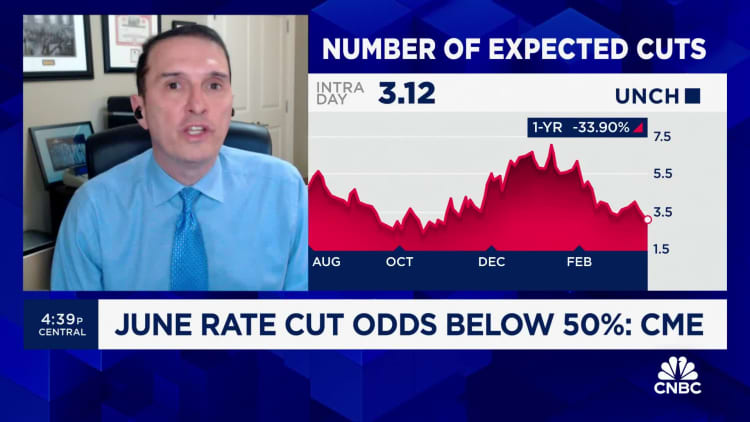
    Fed may not cut rates at all this year, according to market forecaster Jim Bianco

    The Federal Reserve declared Wednesday it can depart need charges unchanged, delaying the chance of price cuts as very effectively as any aid from sky-high borrowing expenditures.

    Over-all, expectations that the Fed is pulling off a easy touchdown have elevated, however that options little comfort for People with higher-fascination private debt.

    And now there is perhaps much less fascination quantity cuts on the horizon after hotter-than-envisioned inflation tales despatched the data that “we’re relocating in the appropriate route, however we’re not there however,” said Greg McBride, major fiscal analyst at Bankrate.com.

    For people, that signifies “a extremely sluggish downward drift in reductions prices however no content material alter in borrowing prices for credit score rating playing cards, auto loans or property fairness strains of credit standing,” McBride talked about.

    More from Private Finance:
    Here’s when the Fed might be to start out out chopping curiosity prices
    Nearly fifty p.c of youthful grownups have ‘cash dysmorphia’
    Deflation: Here is wherever prices fell

    Inflation has been a persistent issue contemplating the actual fact that the Covid-19 pandemic, when worth raises soared to their greatest quantities contemplating the actual fact that the early Eighties. The Fed responded with a sequence of fascination cost hikes that took its benchmark price to its highest diploma in much more than 22 yrs.

    The federal cash price, which is ready by the U.S. central monetary establishment, is the fascination degree at which banks borrow and lend to an individual a further instantly. Whilst that’s not the speed customers spend, the Fed’s strikes nevertheless affect the borrowing and private financial savings prices they see every particular person working day.

    The spike in fascination premiums triggered most client borrowing charges to skyrocket, inserting a number of houses lower than stress.

    Even with some cost cuts on the horizon later this 12 months, buyers won’t doubtless see their borrowing expenditures arrive down noticeably, in accordance to Columbia Company College economics professor Brett Home.

    “The charges of borrowing will keep considerably tight in true situations as inflation pressures proceed to simplicity steadily,” he talked about.

    From bank cards and residential finance mortgage charges to automobile loans and reductions accounts, here is a look at the place folks charges might go in 2024.

    Credit score taking part in playing cards

    Because most bank cards have a variable quantity, you could find a direct hyperlink to the Fed’s benchmark. In the wake of the worth hike cycle, the conventional credit score historical past card cost rose from 16.34% in March 2022 to virtually 21% now — an all-time superior.

    With most individuals expertise strained by larger costs, balances are larger and further cardholders are carrying monetary debt from month to month in contrast with final 12 months.

    Once-a-year share costs will start to reach down when the Fed cuts prices, however even then they’ll solely relieve off notably giant ranges. With solely a few doubtless quarter-point cuts on deck, APRs would nonetheless be shut to twenty% by the conclude of 2024, in response to Ted Rossman, Bankrate’s senior area analyst.

    “If the odd credit score historical past card price falls a share situation from its present report excessive of 20.75%, most cardholders would barely observe,” he said.

    Mortgage costs

    Even although 15- and 30-calendar 12 months house mortgage charges are mounted, and tied to Treasury yields and the general financial system, any individual shopping for for a brand new property has dropped important buying energy, partly due to inflation and the Fed’s protection strikes.

    But premiums are presently cut back as a result of hitting 8% in October. Now, the common degree for a 30-year, fastened-rate mortgage is in shut proximity to 7%. That is up from 4.4% when the Fed began off rising prices in March 2022 and three.27% on the shut of 2021, in accordance to Bankrate.

    Doug Duncan, chief economist at Fannie Mae, expects home mortgage premiums will conclusion the 12 months at 6.4%, however that will not current significantly of a improve for would-be homebuyers.

    “The housing market may be very more likely to carry on to expertise the dual affordability constraints of superior dwelling costs and elevated rates of interest in 2024,” Duncan reported. “The dilemma is nonetheless provide. If costs seem down and it ramps up want and there’s no provide, the one situation that occurs is that residence promoting costs go up.”

    Car loans

    Even although auto loans are mounted, funds are having better as a result of automotive costs have been climbing alongside with the need charges on new monetary loans, leading to much less reasonably priced month-to-month funds. 

    The frequent quantity on a five-12 months new automotive mortgage is now additional than 7%, up from 4% when the Fed commenced boosting charges, in accordance to Edmunds. Even so, competitiveness between lenders and further incentives out there have started to decide on among the edge off the cost of buying for a auto presently, claimed Ivan Drury, Edmunds’ director of insights.

    The second the Fed cuts charges, “that presents individuals a minimal much more respiration room,” Drury defined. “Final calendar 12 months was ugly all near. At the very least you will discover an upside this 12 months.”

    College scholar loans

    Federal pupil private mortgage charges are additionally set, so most debtors should not instantly affected. But undergraduate college students who take out new instant federal scholar monetary loans are actually paying out 5.50% — up from 4.99% within the 2022-23 tutorial 12 months and three.73% in 2021-22.

    Non-public college scholar loans are inclined to have a variable quantity tied to the first, Treasury month-to-month invoice or a unique price index, which suggests all these debtors are presently paying out additional in need. How considerably additional, nonetheless, might differ with the benchmark.

    For these struggling with current private debt, there are means federal debtors can reduce their load, together with income-based plans with $ common month-to-month funds and financial hardship and unemployment deferments. 

    Personal financial institution mortgage debtors have much less picks for assist — regardless of the actual fact that some might take into consideration refinancing after prices get began to happen down, and people with improved credit score might effectively already qualify for a cut back price.

    Discounts costs

    When the central lender has no direct affect on deposit charges, the yields are more likely to be correlated to alterations within the aim federal sources worth.

    As a finish outcome, major-yielding on the web reductions account charges have designed necessary strikes and are actually shelling out way more than 5% — earlier talked about the speed of inflation, which is a scarce purchase for anybody increase an disaster worth financial savings account, McBride defined.

    Because these premiums have very doubtless maxed out, that is the time to lock in certificates of deposit, particularly maturities for an extended time than one calendar 12 months, he reported. “There’s no incentive to maintain out for some factor significantly better as a result of that shouldn’t be the best way the wind is blowing.”

    Currently, 1-year CDs are averaging 1.73
    %, however major-yielding CD charges pay greater than 5%, as superior as or higher than a higher-generate value financial savings account.

    Really do not cross up these exclusives from CNBC Professional

  • What the settlement on household-sale commissions means to you

    Redfin CEO reacts to NAR's $418 million commission lawsuits settlement

    A landmark course-motion lawsuit may rework the manner Us residents acquire and promote residences.

    The Nationwide Affiliation of Realtors agreed to a $418 million settlement remaining 7 days in an antitrust lawsuit the place a federal jury recognized the group and a lot of important real-estate brokerages had conspired to artificially inflate agent commissions on the sale and buy of actual property. 

    The NAR’s a lot of itemizing assist, or MLS, used at a space quantity throughout places in the U.S., facilitated the compensation premiums for the two a purchaser’s and vendor’s brokers.

    At the time of itemizing a belongings, the residence vendor negotiated with the itemizing agent what the compensation can be for a purchaser’s agent, which appeared on the MLS. Nonetheless, if a vendor was unaware they might negotiate, they ended up ordinarily locked into shelling out the listed brokerage cost.

    Much more from Personalized Finance:
    When (and if) you can get scholar financial institution mortgage forgiveness
    The least sophisticated manner for newcomers to begin off investing
    FAFSA ‘fiasco’ could effectively consequence in much less school college students doubtless to college

    The proposed settlement would have the fee provide completely eradicated from the NAR’s system and dwelling sellers will not be liable for shelling out or providing fee for each the shopper and vendor brokers, mentioned actual property lawyer Claudia Cobreiro, the founding father of Cobreiro Law in Coral Gables, Florida.

    “The rule that has been the challenge of litigation necessitates solely that itemizing brokers join an give of compensation,” the NAR wrote in a press launch.

    “Commissions keep negotiable, as they’ve been,” the agency wrote.

    On the different hand, a few of these enhancements may select time to materialize, authorities say.

    Settlement process ‘can get a while’

    If a settlement association is acknowledged inside a lawsuit involving two people, the court docket docket regularly wouldn’t glimpse at the settlement. Nonetheless, in a federal class-action lawsuit, one which has an impact on a wide variety of women and men, there will probably be a time period for the court docket and fascinated events to overview the settlement and provides commentary and feed-back on the settlement, Cobreiro reported.

    “That’s the method that we’re about to enter, and that plan of action can take a while,” she mentioned.

    As proposed, the settlement would have the NAR utterly eradicate commissions from its MLS process by July. That could maybe be optimistic, Cobriero mentioned.

    “It can be rather more sensible to see this getting applied afterwards this yr,” she said.
    Redfin CEO on NAR settlement: People should have a voice in how much a real estate agent gets paid

    In the meantime, it may be “firm as common” for purchasers and sellers, Cobreiro defined. “There is nothing that brokers ought to actually be engaging in in any other case at present of their ongoing transactions.”

    A buyer or vendor already in the market is sort of definitely not going to be affected by the settlement until in fact their belongings occurs to be on the market a tiny longer than what’s customary, she defined.

    “The large grey spot right here is how will buyer [agent] commissions be managed relocating forward,” said Cobreiro, as there isn’t a finalized settlement but that plainly signifies how that will probably be managed.

    What the settlement may essentially imply for homebuyers

    The settlement settlement doesn’t say that the purchaser’s agent is not going to be compensated nor that the purchaser’s agent cannot demand bills.

    “The giant dilemma on this article is who’s going to spend for folks services relocating ahead. Will it in the long term be a shopper that may have to get the purchaser’s agent’s fee collectively, on high rated of closing prices and on main of down cost?” Cobreiro reported.

    Although price service charges are negotiable between involved occasions, determining what playing cards you have on the desk as a homebuyer will probably be much more vital now than upfront of. Making use of an agent will proceed to be a intelligent manner to attain that, consultants say.

    “A implausible neighborhood agent may give you a aggressive edge,” defined Amanda Pendleton, a family developments professional at Zillow Team. That’s particularly reliable as small-priced starter properties are predicted to proceed being in demand from prospects, she defined.

    In this text are two components to find out about how the settlement may rework the course of of buying a house:

    1. Buyers could possibly be accountable for his or her agent prices: Historically, severe property commissions usually arrive out of the vendor’s pocket, and are break up amongst the purchaser’s and vendor’s brokers.

    As a consequence of the settlement, the vendor will no prolonged be accountable for price prices for a purchaser’s agent. So it is a new potential price prospects have to have to ponder of their funds. Historically, if a purchaser’s agent obtained 50 % of a 5% or 6% fee, that equaled 1000’s of {dollars}.

    For living proof: The median property sale price by the shut of 2023 was $417,700, in accordance to the Federal Reserve. That would point out commissions at a 5.37% fee — the 2023 typical fee, in accordance to Lending Tree — quantity to round $22,430, about $11,215 of which could go to the purchaser’s agent.

    But bypassing an agent’s suppliers could effectively not lead to quick financial savings, particularly for initially-time purchasers, gurus say. You may place your self at risk by leaving the homebuying methodology utterly to the vendor and their agent, mentioned Cobreiro.

    Often components reveal up in your residence inspection report that advantage a credit score rating from the vendor, but when you haven’t got an agent, the vendor’s agent could not volunteer that, mentioned Cobreiro.

    Undertaking so can be a breach of their fiduciary obligation to the vendor, and it influences their price if the value of the residence declines, she mentioned.

    “Signing the deal is the least of it you will discover so plenty of issues that occur throughout the transaction that significantly require the abilities and the navigation by one other one who understands the system,” she claimed.

    2. Buyers could maybe be wanted to indication a contract early on: If potential patrons prove to be accountable for his or her agent’s fee, you’re potential to see extra brokers inquiring potential patrons to signal a customer-broker settlement upfront, forward of the agent begins off helping them uncover a residence.

    Most brokerages have a buyer company settlement, however it’s frequent for severe property brokers to wait round to present the deal.

    “They need to get the particular person’s enterprise enterprise, they you mustn’t need to scare them with getting to sign any contracts,” mentioned Steven Nicastro, a former actual property agent who writes for Intelligent Serious Estate.

    Moving the deal talks to beforehand in the method is a precaution to safe purchaser’s brokers in the present market.

    “That could lead on to negotiations actually having location at the first convention in between a purchaser and the purchaser’s agent,” Nicastro reported.

    Know you can negotiate the fee stage as completely as the size of the contract, which may span from 3 months to a 12 months, Cobreiro said
    .
    Never cross up these exclusives from CNBC Professional

  • What it means for customers and sellers


    Andrew Caballero-Reynolds | AFP | Getty Pictures

    The price at which residence worth ranges develop is slowing down.

    U.S. family prices amplified .6% from a month proper earlier than in February, in keeping with the .6% regular common month-to-month obtain within the round 8 a few years main as much as the Covid-19 pandemic, in accordance to a brand new Redfin investigation.

    Just earlier than the pandemic, it was extraordinary for charges to extend about fifty p.c a p.c every and each month, or to maximise all-around 5% or 6% per yr, mentioned Daryl Fairweather, the principle economist at Redfin.

    “We’re once more to that sample, even with these larger dwelling finance mortgage prices,” she talked about.

    More from Personalized Finance:
    What a $418 million settlement on residence-sale commissions might maybe indicate for you
    In 2023, listings on this time physique offered for $7,700 extra, evaluation finds
    What to learn about a couple of condominium and a co-op condominium

    A comparable growth appeared in Moody’s Analytics Household Price tag Index, defined Matthew Walsh, assistant director and economist at Moody’s Analytics.

    “Dwelling prices are appreciating on the similar tempo as upfront of,” he acknowledged. “It’s returned to the development that we noticed pre-pandemic.”

    Having mentioned that, the market at the moment is vastly distinctive from the sector two to eight many years again, authorities say. The widespread home is nonetheless unaffordable for most possible customers when stock has marginally enhanced however not ample to satisfy up with demand from customers.

    “The sentiment we’re acquiring from our brokers is that neither sellers nor potential consumers are happy with this present market,” Fairweather defined. “Sellers are dissatisfied … with provides that they are receiving. And customers are dissatisfied in hovering costs and climbing mortgage costs.”

    Stages of transactions are at ‘recessionary lows’ 

    Even although the housing present market has stabilized by way of promoting worth growth, a major variance regarding the sector these days and the pre-pandemic time frame is the comparatively very low variety of transactions, which is generally because of vital mortgage prices, defined Fairweather. Property finance mortgage prices peaked at virtually 8% previous 12 months, however are nonetheless in extra of 6%, in line with Freddie Mac info.

    In easy truth, the stage of transactions are at “recessionary lows” regardless of “a pop within the particulars in February,” Walsh mentioned.

    An extra issue impacting product gross sales is the very confined present of homes, he further.

    New listings climbed 5% for the period of the ultimate 4 months ended March 17, the foremost year-over-yr soar on condition that May probably 2023, Redfin uncovered. But “it is sort of a tiny restoration from a all-time low,” talked about Fairweather.

    “We’re not again to the place we ended up pre-pandemic,” she claimed.

    Supply growth is basically tied to a seasonal growth, economists say. Homeowners usually listing their households for sale in February primarily as a result of they favor to shift within the spring and summertime, Walsh claimed.

    And sometimes, lifetime happens. “Another issue is simply males and ladies needing to switch for probably a brand new profession or they’re having married, or there may be actually another vital lifetime get together,” Fairweather talked about.

    The payment lock-in impact is loosening its grip

    The home mortgage degree lock-in affect, additionally acknowledged because the golden handcuff affect, saved homeowners with extremely decreased dwelling finance mortgage charges from itemizing their households final yr: They didn’t need to finance a brand new dwelling at a significantly larger curiosity worth. Now, that’s loosening its grip available on the market place and barely boosting on the market supply, economists say.

    “It was certainly preserving people in location, however the extra time that passes, the less strong that affect will get,” Fairweather mentioned.

    Some potential consumers who skilled postpone itemizing their households “are coming to phrases with larger property finance mortgage charges,” since they arrive to really feel they’ll no prolonged postpone the go, Walsh outlined.

    Even although the quantity lock-in impact remains to be having fun with a operate in immediately’s minimal stock, it will fade extra round time, significantly because the Federal Reserve decides to attenuate charges in a while this calendar yr, Fairweather mentioned.

    House mortgage costs are additionally forecast to modestly decline this yr because the Fed trims fascination premiums, though home prices are possible to maintain on being flat or unchanged nationally, Walsh talked about.

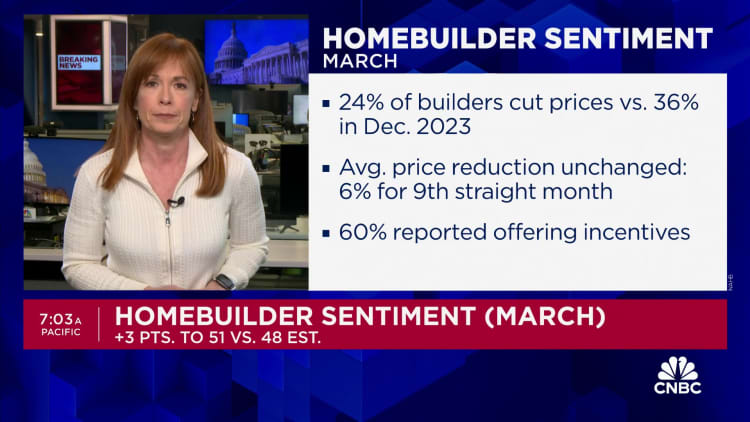
    Homebuilder sentiment turns positive for the first time since July

    New builds are barely strengthening

    New-dwelling income are managing on the massive conclusion of the assortment observed pre-pandemic, averaging about 600,000 for every month, Walsh talked about. There had been 661,000 new households marketed in January, 1.5% further than in December, in accordance to the U.S. Census Bureau.

    Potential consumers irritated with the restricted present of current properties, are giving a elevate to the new-house present market. “Builders are actually benefiting from that,” he mentioned.

    Homebuilders may provide customers incentives that property homeowners may not, this sort of as mortgage price buydowns or price ticket cuts, Walsh extra.

    However, the rise is just not ample to bolster the acute housing present all through the nation. “It actually is heading to take us a while to make up for that hole, even though they’re creating greater than earlier than,” he mentioned.

    Don’t cross up these exclusives from CNBC Professional

  • Trip dwelling co-possession web site Pacaso adds decrease-priced listings

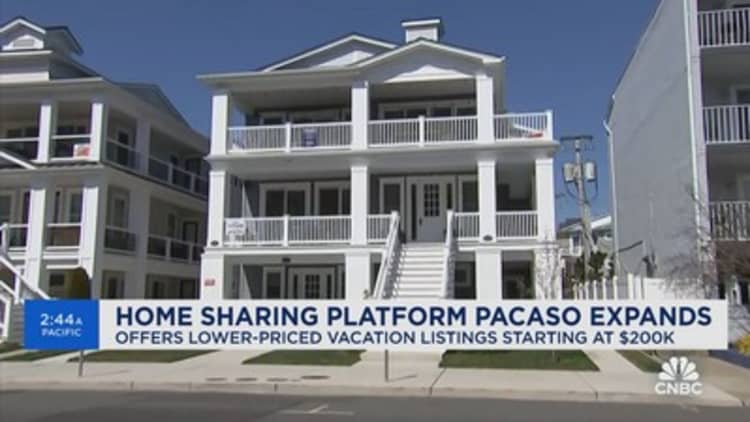
    Pacaso adds lower-priced vacation home listings for co-ownership

    Luxury getaway home co-possession system Pacaso is making an attempt to attraction to the lots, because it grows its enterprise all via a costly and aggressive section of the housing market place.

    The group, which launched in 2020 with multimillion-greenback residences detailed for co-ownership, is now introducing lots of further listings with share prices beginning off as very low as $200,000. Beforehand, shares had been nearer to fifty p.c 1,000,000 kilos, or higher.

    Pacaso lists shares of getaway homes, ceaselessly an eighth however generally extra substantial shares, after which facilitates the purchase, which embody financing if important. It additionally furnishes and manages the family, divvying up the homeowners’ time within the residence by an utility. It can take charges for equally the purchase and the administration.

    “You can handle a big quantity extra home once you spend money on a single eighth or a single quarter of it when in distinction to buying the entire matter, and we’re dwelling in an atmosphere correct now the place by housing affordability is an issue,” claimed Austin Allison, co-founder and CEO of Pacaso. “Property promoting costs are increased, curiosity charges are vital, so it’s actually positively robust for folks in the present day to afford the family of their goals.”

    Not like timeshares in resorts, precisely the place buyers receive the time, not the property, Pacaso householders can benefit from the house’s profit, which generally goes up above time.

    An illustration of Pacaso’s new decreased-priced household trip residence listings.

    CNBC

    “Our homeowners who’ve resold have benefited from about 10% appreciation above and out of doors of what they paid out for the underlying residence earlier. So the Pacaso shares generally hold monitor of with the underlying true property,” reported Allison.

    Wealthier potential patrons have been scooping up ski residences in Colorado and seaside homes in Hawaii, paying lots of of lots of of dollars for his or her shares. Pacaso usually takes a hefty charge — amongst 10% and 15% of the advantage of the property on the entrance cease — associated with aggregating the group of proprietors, facilitating the transaction, and atmosphere up the co-possession framework.

    Pacaso arrived at way over $1 billion in income previous yr, the enterprise defined.

    The company has, nonetheless, considered some backlash from communities that liken it to an Airbnb on steroids. There is even a site dedicated to battling the enterprise, recognized as “Prevent Pacaso Now.”

    Residents of Sonoma, California, handed an ordinance prohibiting Pacaso from functioning in that metropolis. In St. Helena, California, which prohibits timeshares, Pacaso achieved a settlement that guards its 4 properties by now there, however the agency shouldn’t be allowed to broaden to different properties.

    “We function in way over 40 markets nationwide and in solely a handful are we misunderstood,” argued Allison. “Our resolution is to work with policymakers and educate them on the specifics and features. Our perception is that in extra of time this can prevail. It hasn’t labored in Sonoma nonetheless and a smaller handful of communities who’ve handed ordinances to withstand the mannequin.”

    Pacaso can also be together with a brand new suite of providers to assist main homebuyers receive the dwelling-sharing design. About simply one-fifth of most essential homebuyers ultimate yr purchased with both buddy or relative, in accordance to critical property site Zillow.

    “Men and ladies at the moment are working with co-possession as a solution to be outfitted to afford properties that they often wouldn’t be able to afford to pay for. So, it is not simply happening within the trip residence space,” claimed Allison.

    Don’t overlook these exclusives from CNBC Pro

  • High price tag of upgrading to a nicer dwelling is locking up the market

    Home prices rose 5.5% in February compared with same month a year earlier: CoreLogic

    The spring housing business is defying anticipations that price ranges would superior and competitors would simplicity.

    Better property finance mortgage charges ordinarily cool each price ranges and wish, as they did ultimate yr, however that is not the scenario now. There are nonetheless far too couple of homes on the market as a result of current owners can’t discover the cash for to go, and it actually is retaining costs substantial.

    Residence price ranges in February had been 5.5% greater than they’ve been in February of final 12 months, in accordance to CoreLogic. That once-a-year comparability is shrinking a little bit, however the price obtain from January to February was nearly two instances what it usually is for that point of 12 months, suggesting this spring’s market place began out potent regardless of greater curiosity costs.

    The common price on the 30-calendar yr set residence mortgage strike its most present important in October, briefly crossing above 8%. It then dropped again once more into the 6% differ for a lot of December and all of January. It rose again greater than 7% in February, which actually ought to have cooled the sector.

    But income of newly crafted properties, that are counted by contracts signed all through the month, ended up virtually 6% larger in February calendar yr over 12 months. Pending product sales of current residences, additionally depending on signed contracts, have been being down 7% that thirty day interval from the yr forward of, however not for absence of want.

    Lock-in impression

    The genuine points in trendy present residence present market is lack of present. There are extra new listings this spring than final, however supply is nonetheless 40% beneath wherever it was pre-pandemic.

    That is partly since present-day house owners are affected by a lock-in impact: They is not going to itemizing their residences on the market for the cause that the price of transferring up is so excessive.

    In the 22 yrs prematurely of the Federal Reserve commenced rising premiums in 2022, upgrading to a 25% way more expensive residence would have elevated the common house owner’s month-to-month cost of principal and want by 40%, or about $400 on frequent, in accordance to information from ICE Mortgage Technologies. Relocating to a equal family throughout the avenue wouldn’t enhance their cost in any respect.

    In stark distinction at the moment, the regular house owner with a in shut proximity to report-small mortgage price would see their month-to-month cost shoot up 132%, or about $1,800, in buy to transfer up to a 25% way more expensive family. Buying the exact same dwelling they’re in now would increase their month-to-month cost by 60%, in accordance to ICE.

    Those individuals improves signify countrywide averages and might fluctuate market to business. For living proof, transferring up would come with $604 to a house owner’s month to month cost in Buffalo, New York, an improve of 108% and $4,517 in San Jose, California, an elevate of 161%, in accordance to the ICE information.

    “Lessen prices would ease the calculation for fairly a few and make strikes extra honest. But the internet consequence carries on to be far too quantity of properties for too tons of clients,” reported Andy Walden, ICE’s vice chairman of group evaluation. “Until that important mismatch is handled, quite simple supply and want will proceed to push on each inventory and affordability.”

    What cost would unlock the market place?

    If costs fell to 6%, the month to month cost increase to commerce up to a 25% additional expensive residence would relieve from a 103% frequent bounce to 88% – a modest however welcome enchancment, in accordance to Walden.

    If premiums fell to 5%, going up would require a 68% bigger sized cost, however a nice deal greater than the extended-run typical of 39%, however maybe ample to encourage one other individual with a persuasive will want or want to improve.

    While not all debtors have report-very low prices, additional do in expensive marketplaces as a result of the breakeven stage on the price tag of a refinance is typically diminished for higher-equilibrium debtors, in order that they have a lot extra incentive to do it. They additionally attainable have better-stability monetary loans, so relocating up to a larger price can be even costlier. That’s why the lock-in consequence is a lot better in considerably of California, the place houses are most costly.

    The big overwhelming majority of debtors these days, 88.5%, have residence loans with prices beneath 6%, in accordance to Redfin. Around 59% have premiums beneath 4%, and close to to 23% of property homeowners have prices beneath 3%.

    Those individuals shares are considerably decreased than they’ve been ultimate yr, just because some individuals did select to switch in the final 12 months, but it surely reveals what the sector is up in opposition to, significantly given important and still-growing home price ranges.

    A brand new report from Zillow reveals the U.S. now has a history-high 550 “million-dollar” cities, or metropolitan areas the place the customary home is worth $1 million or further. That is 59 additional million-greenback cities than there have been in 2023, when dwelling values have been weakening thanks to rising home mortgage costs.  

    Really don’t go up these exclusives from CNBC Professional

  • Housing ‘affordability has just absolutely collapsed,’ economist suggests

    10’000 Several hours | Digitalvision | Getty Images

    Housing bills are outpacing median household incomes within the U.S., additional extra straining affordability.

    Would-be homebuyers require to receives a commission $113,520 a yr to afford the conventional home within the U.S. That is 35% way over what the everyday residence earns yearly, which is $84,072, in line with a brand new analysis by Redfin, a national true property brokerage web-site.

    “Considering that the pandemic, affordability has just totally collapsed,” claimed Chen Zhao, a senior economist at Redfin. 

    February 2021 was the final month when the same old home attained further money than it wished to afford the median property. There is actually been a deficit ever contemplating that, Zhao mentioned.

    Much more from Personalized Finance:
    Leading faculties develop financial assist awards to get rid of pupil loans
    What you should should find out about Social Security’s new overpayment insurance coverage insurance policies
    What motorcar purchasers should should know

    “That deficit strike a peak in October of 2023,” she included. “The cause why it hit a peak then is given that which is when residence finance mortgage prices peaked as completely.”

    In the meantime, residence prices additionally remained giant since of a list crunch: the median sale worth for a house was $412,778 in February 2024, in accordance to Redfin.

    Affordability deficit narrowed in February

    The regular home fell restricted $29,448 to pay for a property in February, in accordance to Redfin. In Oct 2023, households have been restricted by $40,810. At that point, clients important an widespread earnings of $120,500 to afford a house.

    The affordability deficit narrowed primarily as a result of property finance mortgage costs have been on a dependable drop contemplating that the final peak in October, in line with Zhao. At that peak, the conventional 30-calendar yr preset residence finance mortgage quantity strike 8% for the initially time contemplating that 2000.

    “It’s been a fairly giant modify contemplating the truth that ultimate Oct,” Zhao claimed. 

    Other causes this type of as seasonal pricing could probably be mirrored, as dwelling worth ranges are more likely to lower within the winter months, defined Jeff Ostrowski, a housing analyst at Bankrate.

    On the opposite hand, attainable customers are however on the sidelines, reported Veronica Fuentes, a accredited financial planner at Northwestern Mutual.

    “They’re probably holding off or they’re having their time,” she said.

    The newest layoffs within the engineering sector have impacted a few of her purchasers’ attitudes, Fuentes said. Whilst her clients could maybe not be on the chopping block, their co-employees get laid off has constructed quite a lot of of them much more cautious.

    “If you ended up laid off, may you nevertheless pay for this mortgage mortgage? Do you might have 6 months [of] disaster monetary financial savings or perhaps a yr [of] emergency reductions? … Can you nevertheless have enough money the house mortgage for six months when you’ve got no job?” Fuentes reported.

    Brown Harris Stevens CEO: The housing market has done 'incredibly well' considering all headwinds

    Navigating superior costs within the housing sector

    In a time when a probable purchaser desires to generate about $114,000 a yr to afford to pay for a median-priced family within the U.S., a starter home would take advantage of feeling for price-delicate potential patrons, trade consultants say.

    A probable buyer must make about $76,000 a yr to have enough money a starter property, which Redfin defines as a home in roughly the bottom 1/3 of the housing distribution in phrases of price.

    Starter residences are laborious to come back by. Household builders above the sooner 15 yrs or so have moved absent from constructing entry-level homes, defined Ostrowski.

    For nearly the whole 2nd fifty % of the twentieth century, an individual may put money into a home for $120,000 in quite a lot of elements of the U.S., he defined.

    “That just is not going to exist any longer,” Ostrowski mentioned.

    Potential patrons may search reduce bills in particular markets within the U.S. There are 13 metropolitan areas the place by patrons could probably have enough money the common residence with out the necessity of incomes 6 figures, Redfin uncovered. 

    In Detroit, the everyday family wanted to earn $46,168 to handle the median-priced residence in February, constructing it essentially the most very reasonably priced sector within the area. It was adopted by Cleveland ($58,186), Pittsburgh ($61,603), St. Louis ($66,755) and Philadelphia ($73,182). The different metros through which homebuyers constructing fewer than $100,000 can handle the everyday residence are Indianapolis, Cincinnati, Milwaukee, Warren, Michigan Kansas Metropolis, Missouri Virginia Beach, Virginia San Antonio, Texas, and Columbus, Ohio.

    What is to come back for the housing present market

    Specialists say borrowing prices ought to seem down because the Fed solidifies its designs to slash once more want prices. Household price ticket enlargement can be anticipated to melt as inventory improves.

    New listings climbed 5% all by means of the previous 4 months ended March 17, the key yr-in extra of-yr bounce provided that Could 2023, Redfin discovered.

    “Men and girls are discovering type of exhausted of ready, so we’re commencing to see an entire lot far more inventory seem on,” Zhao talked about.

    Even so, purchase this with a grain of salt, Ostrowski said, because the outlook 6 months prior to now was actually numerous from how objects performed out.

    “If you occur to be prepared and you’ll pay for it, purchase now,” he mentioned. “Ailments almost certainly are usually not going to get noticeably improved.”

    In truth, whereas the combo of lowered prices and boosted supply should assist with affordability, “it’s really not more likely to fully alter the {photograph},” reported Zhao.

    Really do not miss out on these exclusives from CNBC Pro

  • Why new build homes can lead to a property tax surprise

    Comstock Images | Stockbyte | Getty Images

    It’s common for new householders to face monetary surprises, however individuals shopping for a newly constructed residence could also be extra probably to encounter sticker shock on a key expense.

    Almost 75% of latest homebuyers had regrets about their buy, in accordance to a 2023 survey from Real Estate Witch. Property taxes had been the most typical gripe, shocking 33% of new homeowners.

    With new builds, property taxes can change dramatically after buy as a result of preliminary charges are sometimes primarily based on estimates. That can be jarring for householders who already stretched their budgets to afford a residence within the present market.

    As a part of its National Financial Literacy Month efforts, CNBC shall be that includes tales all through the month devoted to serving to individuals handle, develop and shield their cash so that they can actually dwell ambitiously.

    Newly constructed homes comprise 30% of the present market, up from the standard 10% to 20%, in accordance to a latest report by the National Association of Realtors. As extra consumers flip to builders, potential homeowners want to pay attention to how prices would possibly improve after even simply a 12 months, consultants say.

    “Buyers want to perceive that actual property taxes … aren’t static. They can change on an annual foundation,” stated Melissa Cohn, regional vp at William Raveis Mortgage. “People do not actually have any management.”

    Why property taxes can bounce for new builds

    When lenders qualify somebody for a residence buy, they issue within the principal, the curiosity fee on the mortgage, home-owner’s insurance coverage and property taxes.

    But in contrast to beforehand owned homes, new builds lack a tax invoice as a result of there is no home to assess but, consultants say. Instead, mortgage lenders will usually use an older tax fee from the world or an estimated tax fee to calculate the proprietor’s month-to-month fee.

    The calculation goes to range by lender, stated Brian Nevins, a gross sales supervisor at Bay Equity, a Redfin-owned mortgage lender. Some take 1% to 2% of the gross sales value of the house for the property taxes, whereas others multiply one-third of the gross sales value by the native tax fee to decide estimated taxes.

    The hidden reason some U.S. homes are losing value

    Initially, the home-owner will usually pay the estimated property tax fee into escrow. Depending on the native tax evaluation cycle, the county workplace will finally assess the worth of the new home to decide the precise property tax fee.

    “All counties reassess a property’s taxes — it will depend on when,” Cohn stated.

    While some locations could differ on frequency, “if it is new building, they all the time reassess,” she defined.

    And at that time, if the home-owner has an escrow account, they could study they’ve a scarcity, which means they owe extra property taxes than anticipated.

    If the home-owner can not pay the owed taxes in a lump sum, the lender often pays what’s owed. In that case, the proprietor pays again the lender via an elevated mortgage fee to make up the distinction. 

    Tricks to gauge how property tax could change

    “People who purchase at this time with the idea that they qualify primarily based on the present actual property taxes or present insurance coverage want to actually do extra homework to perceive the place they may actually be in a 12 months,” Cohn stated.

    If you are trying to purchase in an space you are unfamiliar with, learn how usually the county reassesses property taxes and what the reassessment components relies on, Cohn stated.

    Additionally, you might have considered trying to seek the advice of with a native mortgage officer who understands the panorama of the world you are shopping for into, Nevins stated.

    If some newly constructed homes in your neighborhood with related sq. footage have been round for a 12 months, you may examine the property handle on a actual property web site and get a ballpark estimate of what your taxes could be, stated Veronica Fuentes, a licensed monetary planner at Northwestern Mutual.

    However, tread with warning: When you have a look at actual property taxes listed on-line, these are the taxes the present proprietor pays, not what you’ll pay, Cohn stated.

    Correction: This story has been up to date to replicate that some lenders estimate preliminary property tax charges for new builds primarily based on one-third of the gross sales value multiplied by the native tax fee. An earlier model of this story misstated that components.