Tag: broker

  • Is this Australia’s youngest home finance loan dealer?

    Is this Australia’s youngest home loan dealer? | Australian Broker News

    Information

    Is this Australia’s youngest home loan dealer?

    What it actually is wish to be the youngest man or girl within the place
    Is this Australia’s youngest mortgage broker?

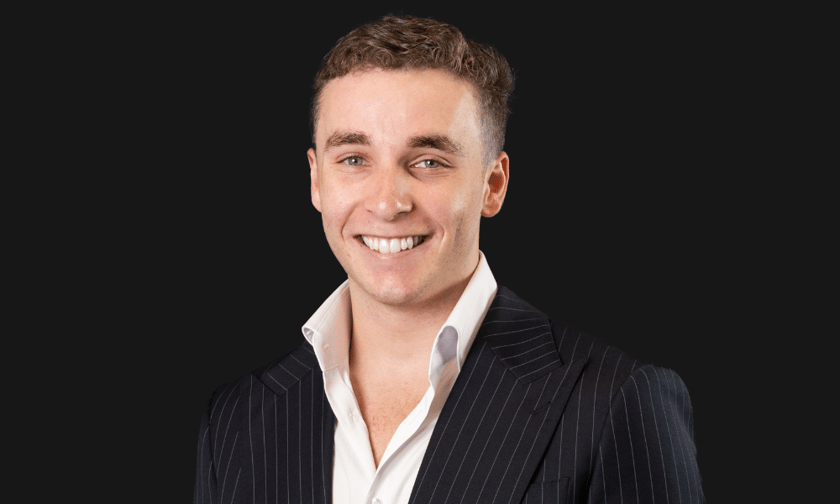
    While he is perhaps a seasoned 20-12 months-outdated now, Will Frazer (pictured greater than) was solely 17 and discovering out at an individual of Sydney’s main private schools when he questioned the validity (and value) of prepping for a very long time of college for a nondescript system he skilled no enthusiasm for.

    Three calendar yr afterwards, he retains a Diploma of House loan Broking and was lately appointed director and shareholder of OURLOAN FINANCE BROKERS, which additionally holds its possess ACL.

    Maybe most gratifying, this yr Frazer turned a initially residence purchaser, transferring into his new space in extra of the Easter cut up – all earlier than he turns 21.

    For Frazer, presently being the youngest individual within the place has simply grow to be part of the everyday day-to-day.

    “I’ve under no circumstances fulfilled anybody as youthful as me,” he spelled out. “The closest I arrived was a number of of brokers of their mid-twenties that I fulfilled at my aggregator countrywide conference final 12 months. We rapidly linked in extra of the reality that we’ve been an amazing decade youthful than anyone else within the home.”

    Though the common age of a home loan dealer in Australia isn’t broadly printed, many home loan brokers are more likely to be educated specialists with a monitor file in finance, banking, or real property.

    Some others may come from quite a few career paths, the everyday subject is that individuals sometimes “fall into” broking and ship a wealth of experience to their roles.

    “At the occasion, we had been being surprised since we’re all on Instagram and we see so quite a few younger brokers in our feed that we simply assumed we had been a primary fee share of the dealer inhabitants – however seemingly not.”

    Broker occupation paths: Finance broking by the use of his veins

    Rising up, Will put within the higher aspect of his doing work life throughout school taking pleasure in time at his mum’s Bondi Junction brokerage, OURLOAN Finance Brokers.

    “I skilled finance working by way of my veins,” he claimed.

    Even so, the prospect of not heading to school proved unpopular amongst members of the family, buddies and the college. But within the face of all of it, his willpower prevailed, and he accomplished equally his HSC and his Certificate IV in Home loan Broking by the point he’d turned 18.

    Even so, to be a efficient dealer, Will Frazer realized that the experience and apply had been solely facet of the equation.

    “The actual driver of success is a dealer’s potential to meet the suitable people who skilled the the 2 the standing and the have an effect on to refer clientele,” he said.

    When he initially joined the corporate, Frazer labored on his mum’s recordsdata, discovering out “the A-Z of lending” and the worth of gadgets and processes.

    “From there I sat in on mum’s financial institution loan interviews after which alongside each other we might brainstorm our treatment techniques for all these consumers,” he mentioned. “I constructed my self esteem and proper after 9 months, I wrote my very first dwelling monetary loan.”

    His nineteenth yr was his initially yr broking – mastering the ropes, attending “a great deal of auctions and open up houses”, loan firm actions, and predominantly crafting monetary loans for 1st dwelling shoppers and rentvestors.

    “I’ll under no circumstances overlook that second, calling this younger few, buying for the primary time, and permitting them know their finance was accredited,” Frazer reminisced. “Being part of constructing their dream a actuality is every thrilling and coronary heart-warming.”

    Twelve months afterward, Will reported he operates on 5 to 6 monetary loan data every 7 days.

    Today, not loads has modified with round 70% of his buyer conferences carried out on the web.

    “Even if the patron principally lives 5 minutes away, I uncover most moments they need a ZOOM assembly,” he reported. “They by no means need to fuss about preparing for a property check out.”

    Frazer reported he’s further than comfy demonstrating procedures and choices onscreen, the place they are often “executed and dusted” in an hour.

    “Especially in case you’re a occupied certified millennial purchaser, which is almost all of my consumer base,” he mentioned.

    “This has enabled me to cost-free up my visitation time for enterprise enterprise enchancment actions with my true property referrers and to go to auctions and open up houses to help my impressed, pre-approved monetary loan clientele.”

    Mix that with do the job expertise or internship alternatives with neighborhood brokerages about college trip breaks, in order that HSC-pupils get the prospect to use their theoretical scientific research and data working in an workplace atmosphere pure atmosphere,” Frazer mentioned.

    For OURLOAN, the Frazers at the moment are putting this into apply.

    “Our Brokerage, like a number of other people, are rising and rising,” Frazer said. “We not too way back introduced two new appointments to the employees this calendar yr and depend on we might be using as soon as extra early in 2025.”

    “We could be extraordinarily divulge heart’s contents to utilizing on a HSC-graduate with ambitions to beginning to be a dealer in simply three-to-five a very long time.”

    When did you begin out mortgage loan broking? Comment down beneath.

    Related Tales

    Continue to maintain up with the newest data and occasions

    Be part of our mailing itemizing, it’s completely free!
  • Why use a Property finance loan Broker

    The house finance loan quantity pendulum swings nonetheless once more

    By Didier Malagies
    •
    18 Apr, 2024

    Anticipate 2024 to be mildly significantly better than 2023 with home loan charges falling within the subsequent fifty % of the calendar yr, housing gurus opined in their forecasts on the finish of the yr. Cuts to the Federal money cost (and subsequently to property finance loan charges) are imminent, merchants enthused simply after December’s convention of the Federal Open up Market Committee by which committee associates predicted a few charge cuts in 2024. Some business consultants forecasted as a lot of as six charge cuts within the calendar yr primarily based on this data. Level cuts are nonetheless coming, simply not in March , merchants and present market authorities reasoned extra a brief whereas in the past because the monetary system ongoing to run extremely scorching. And now on the heels of critiques of extra highly effective than envisioned positions development and stickier than predicted inflation , the market’s change from optimism to pessimism round cost cuts is full. Some even hope degree hikes forward of charge cuts. The pessimism is noticeable in house loan costs. Freddie Mac‘s weekly Major Mortgage Sector Survey is climbing again in path of seven%. HousingWire’s Mortgage loan Fee Centre , which depends on data from Polly, is now earlier talked about 7.2%. Charges have been being as minimal as 6.91% for Polly and 6.64% for Freddie as a brief whereas in the past as February. On Tuesday, they attained 7.50% on Mortgage News Day by day, a substantial for this calendar yr. Home loan costs maintain key capability within the housing business most significantly, excessive charges exacerbate the current affordability disaster by walloping the getting energy of would-be potential consumers and discouraging some would-be sellers – individuals with decrease, preset-level mortgages – from itemizing their houses, a drain on available inventories. All this leaves housing consultants after as soon as once more battling for his or her share of shrinking pies – as now we have observed with recently launched property finance loan data and RealTrends Verified’s brokerage data , as successfully as deeper dives on the brokerage landscapes in Jacksonville and San Diego . It is unsurprising, then, that true property shares have skilled contemplating that the FOMC’s March meeting and the present occupation and inflation reviews. That incorporates the nation’s main homebuilders (DR Horton and Lennar), house finance loan originators (United Wholesale House loan and Rocket Home finance loan), brokerages (Any the place and Compass) and family lookup portals (Zillow and CoStar, which owns Homes.com). There are different dynamics at play for a few of these firms, then again. The brokerages are additionally contending with the rule variations built-in in a proposed settlement by the National Affiliation of Realtors some merchants additionally really feel these rule modifications edge CoStar on the worth of Zillow . UWM, within the meantime, is contending with a scathing investigative report by a hedge-fund-affiliated information group whose hedge fund shorted UWM and went prolonged on Rocket it is usually coping with pending litigation . UWM denies the allegations constructed within the report.  High property finance loan charges, much less mortgage loan functions and fewer family earnings are regretably not the one results housing business consultants might see from a extra prolonged substantial-rate ambiance. There are additionally spillover results from different industries, specifically place of job real property. Regional banking establishments – which normally have been predominant family property finance loan originators – went vital on business true property loans as a lot bigger banking firms scaled once more on this place in new a number of years. That elevated their publicity to downtown place of job towers, which have seen an exodus of tenants and a bottoming out of appraised values simply as a doc $2.2 trillion in business real property debt comes thanks over the upcoming few a few years. That ties up cash that would usually transfer to residential house loans and in some cases stresses banking establishments like New York Local group Lender, mom or father of Flagstar Bank — the Seventh-premier financial institution originator of family house loans, Fifth-most vital sub-servicer of property finance loan loans and the 2nd-biggest home loan warehouse lender within the place. Homebuilders, too, really really feel the results of prolonged substantial charges. While homebuilder confidence is proceed to up noticeably as a result of truth final drop, new housing commences are slowing . The dim potential shoppers for homebuyers have turned some consumers to the nascent create-to-lease sector , primarily a guess that substantial charges are under to remain for in depth loads of that would-be customers are actually would-be renters.

  • Finsure companions with mentor Ruan Burger

    Finsure companions with mentor Ruan Burger | Australian Broker News

    News

    Finsure associates with coach Ruan Burger

    Partnership enhances dealer teaching

    Finsure partners with coach Ruan Burger

    Finsure Team has partnered with residence mortgage dealer mentor Ruan Burger’s Results and Broker software program, to ship education to its community of additional than 3,300 brokers.

    Finsure groups up with Ruan Burger

    Burger, who transitioned from mortgage mortgage brokering to teaching, expressed his goals for the partnership.

    “After so loads of a long time within the sector, I’m desperate to share what I’ve learnt and help different individuals come to really feel the similar diploma of achievement I felt as my enterprise grew,” he claimed.

    Burger methods to make use of his teaching utility to provide foundational courses and methods to spice up dealer achievement.

    Simon Bednar (pictured above), CEO of Finsure Group, described the Success and Broker utility.

    “Where the Achievements and Broker system really stands aside from different packages is that customary enterprise coaching solely focuses on the house mortgage course of, regardless that Success and Broker covers the way to productively function a small enterprise and to set and provide goals to turn into further worthwhile,” Bednar talked about.

    He additionally talked about that Finsure brokers might go to the first session of this system at no worth.

    Impact on dealer teaching

    The partnership goals to combine Burger’s program into Finsure’s coaching selections to ship a extra in-depth enterprise enterprise training and studying for brokers. This go is meant to equip Finsure brokers with broader capabilities in enterprise administration collectively with frequent residence mortgage instructing.

    Get the preferred and freshest mortgage mortgage data despatched proper into your inbox. Subscribe now to our FREE daily publication.

    Hold up with the most well liked information and features

    Sign up for our mailing guidelines, it’s free!

  • NSW adviser banned completely | Australian Broker News

    NSW adviser banned completely | Australian Broker News

    Information

    NSW adviser banned perpetually

    Ban for dishonest cash carry out

    NSW adviser banned permanently

    Company regulator ASIC has completely banned NSW cash adviser Adele Baaini from delivering any cash services or participating in credit score rating actions.

    The conclusion will come following conclusions of dishonest carry out and a deficiency of integrity and appear judgment in her skilled duties.

    Particulars of Adele Baaini’s misconduct

    ASIC’s investigation uncovered that Baaini equipped falsified {qualifications} to AAN Wealth Management (AAN Prosperity) and advisable consumers improperly. Particularly, she submitted a fake Monetary Adviser Examination certification and provided personal recommendation to 121 consumers even with determining she didn’t fulfill demanded training and training requirements.

    “Ms Baaini engaged in dishonest perform and unsuccessful to behave with integrity and sound judgment in relation to a fiscal supplier,” ASIC defined in a media launch, extra stating that she is “not a in fine condition and proper man or lady to supply financial suppliers.”

    ASIC on case observe file and proper to appeal

    Baaini, who was related to AAN Prosperity from April to June 2023 and served as the only real director and secretary of SMR Financial loans, has additionally been recognized incompetent to offer financial options under present-day legislative necessities.

    Her actions and expert benchmarks violations have been recorded on ASIC’s banned and disqualified sign-up.

    Baaini retains the proper to attraction ASIC’s option to the Administrative Appeals Tribunal.

    Get the most well liked and freshest house finance mortgage data shipped appropriate into your inbox. Subscribe now to our FREE every day e-newsletter.

    Preserve up with the newest information and actions

    Be a part of our mailing guidelines, it’s completely free!

  • FSC expands board | Australian Broker News

    FSC expands board | Australian Broker Information

    Information

    FSC expands board

    New voices, extra sturdy advocacy

    FSC expands board

    The Fiscal Providers Council (FSC) has introduced the appointment of 4 new administrators, broadening its management to incorporate issues like much more voices from the economical recommendation sector.

    The new administrators are Keith Cullen from WT Money Team, Neil Young from Fortnum Financial Group, Esther Kerr from Australian Unity, and Andrew Creber from J.P. Morgan Asset Management.

    FSC Chairman David Bryant pressured the strategic nice significance of the appointments.

    “The appointment of 4 senior sector leaders to the FSC board gives new depth of expertise to the FSC board and can extra fortify our illustration of {the marketplace},” Bryant claimed.

    Increasing financial data illustration

    FSC has welcomed many steerage licensees – Count, Fortnum Non-public Wealth, Infocus, Otivo, Rhombus Advisory, and WT Money Group – into its membership, in a transfer that goals to leverage their experience in shaping the council’s protection development processes amid ongoing economical strategies reforms.

    Blake Briggs (pictured above), CEO of the FSC, highlighted the value of a unified sector voice.

    “The cash corporations discipline is at its strongest when it speaks with a unified voice on regulatory and protection challenges that affect the sector and its clients,” Briggs defined.

    Administrators on their new roles

    The newly appointed administrators expressed enthusiasm for his or her roles in strengthening FSC’s advocacy makes an attempt.

    Cullen well-known the priority of constructing economical ideas extra cheap and accessible.

    “Delivering further economical and obtainable cash steerage for Australian clients is a precedence for the FSC and the ideas profession and I seem ahead to contributing to a strong, unified market voice that ensures reform continues to be a precedence for the federal government,” he claimed.

    In the identical approach, Youthful commented on the relevance of integrating the encounters of economic advisers into FSC’s coverage progress to boost regulatory frameworks for advisers and their clientele.

    Influence on the cash skilled providers business

    The addition of the brand new directors not solely shows the FSC’s broad membership but in addition its dedication to representing a assorted vary of pursuits inside the financial corporations sector.

    “FSC delivers with one another an ever extra diversified established of enterprises and views from all through the economical corporations discipline, all centered on acquiring sustainable, obtainable and related objects and skilled providers for our customers,” Kerr reported.

    Get the most well-liked and freshest house mortgage data despatched right into your inbox. Subscribe now to our FREE day-to-day publication.

    Latest Information

    FSC expands board

    Maintain up with the most well liked data and gatherings

    Be part of our mailing guidelines, it’s no value!

  • PennyMac Money Providers touts broker channel gains as earnings rebound

    PennyMac Monetary Providers documented some inexperienced shoots in its origination group, side of a extra substantial earnings restoration that was significantly dampened by hedging losses.

    The California residence finance mortgage massive posted a $39.3 million revenue within the preliminary quarter, pursuing a $36.8 million web loss to close 2023. The rebound, additionally a 29% enhancement from the similar time last 12 months, was pushed in part by significantly extra compact settlement obligations to know-how rival Black Knight. 

    The multichannel monetary establishment recorded slight  quarter-over-quarter declines in manufacturing pretax internet cash, coming in at $35.9 million, and complete amount of $21.7 billion. Its correspondent and broker achieve-on-sale margins ticked up then again, with the broker quick channel leaping from 79 foundation particulars to close 2023 to 103 within the present interval. Its purchaser direct lock quantity was additionally up 35% quarterly. 

    The agency stated it counts round 4,000 brokers, up 36% from the same time final yr. PennyMac Chairman and CEO David Spector attributed the broker margin and populace gains to his agency’s know-how and way more jumbo residence mortgage train, amongst different motives.

    “There was a time period of time a yr or two again once more when there was irrational pricing having put on this part of {the marketplace}, and I really feel now we have considered a type of a return to additional rational pricing,” he reported, exhibiting to consult with the wholesale pricing wars of yesteryear.

    The agency’s servicing capabilities recorded $4.9 million in pretax internet revenue within the initially quarter, up from a $95.5 million decline previously 3-thirty day interval lengthen. PennyMac additionally noticed $170 million in mortgage servicing authorized rights good price gains, a decide offset by $294.6 million in hedging declines for a $125 million complete lower. 

    Executives, responding to analyst queries concerning the hedging decline, stated the group had an elevated publicity to need quantity volatility and cited the inverted yield curve. 

    “We had been pretty appreciable alternative bills for shielding our regular hedge place,” talked about Daniel Perotti, senior caring for director and chief monetary officer. “We wanted to find out if we most popular to accept people hedge costs or open up up certain exposures.” 

    Firm leaders claimed PennyMac has contemplating that repositioned its hedge within the second quarter to a “extra standard profile.”

    PennyMac’s income in the meantime wavered at $305.7 million ending March, down from the fourth quarter’s $361.9 million mark and just a little bit up from $302.8 million on the related time previous yr. 

    Spector and Perotti additionally addressed the agency’s Office of Veterans Affairs mortgage profile in talking on the forthcoming VA Servicing Acquire plan, or VASP. The initiative is a successor to the VA’s pandemic-period partial assert for its distressed debtors.

    PennyMac counts 4,700 VA monetary loans in a deep delinquency place, or $1.2 billion of unpaid principal stability amongst its huge servicing portfolio. Executives appeared cautiously optimistic when requested about VASP.

    “Where by now we have potential drawback nowadays is near the moral hazard and the way that might lastly carry out out,” said Perotti. 

  • Queensland housing approvals | Australian Broker Information

    Queensland housing approvals | Australian Broker Information

    News

    Queensland housing approvals

    Streamlined strategy for a lot extra residences

    Queensland housing approvals

    The Queensland federal authorities has opened expressions of curiosity (EOI) for housing duties lower than a brand new streamlined approvals methodology.

    The initiative, part of the Properties for Queenslanders technique, goals to hurry up the constructing of latest homes, considerably economical varieties, by simplifying the scheduling and approvals phases.

    Meaghan Scanlon (pictured increased than), minister for Housing, Community Governing administration, Scheduling, and Community Is efficient, pressured the intention of creating properties quicker.

    “We are making it faster and simpler to assemble much more very reasonably priced, high quality households quicker within the supreme locations, within the neighborhood of suppliers and transport,” Scanlon claimed.

    ‘This new workers needs to look at all proposals to supply housing that fulfills the numerous wishes of Queenslanders,” Scanlon acknowledged.

    Business leaders endorse housing approach

    Nicole Bennetts, state supervisor for the Arranging Institute of Australia in Queensland and Northern Territory, praised the federal government’s strategy, highlighting the continued need for reasonably priced and varied housing resulting from sturdy inhabitants growth and altering family demographics.

    “Good scheduling is a part of the answer to help much more well-found economical and quite a few housing that meet up with the calls for of the neighborhood,” Bennetts acknowledged.

    Alan Miller, CEO of Villawood, expressed assist for the federal government’s initiative to reduce pink tape and speedy-keep monitor of enchancment apps that cater to assorted and really reasonably priced housing requires.

    He highlighted Villawood’s readiness to work together with the brand new laws and get the job completed with the SFD workforce on upcoming assignments in Queensland.

    Potential housing goals

    The Households for Queenslanders initiative has established formidable targets to produce a single million much more residences by 2046, akin to 53,500 social properties. The streamlined system launched by the SFD group is a important step in undertaking these targets and addressing the housing affordability catastrophe in Queensland.

    Get the most well liked and freshest dwelling finance mortgage information despatched supreme into your inbox. Subscribe now to our FREE day-after-day publication.

    Hold up with the most well liked information and conditions

    Join our mailing guidelines, it’s cost-free!

  • Visa queries major broker searches in March: L&G – Mortgage loan Method

    Queries about lenders’ visa requirements had been essentially the most searched-for element of situations in March, while demand for desire-only bargains dipped 8%, in accordance to knowledge from Lawful & General Ignite.

    The sourcing platform says considerably of brokers’ analysis train related to debtors with difficult situations because the second most-searched-for time period simply after “visa” was “default glad”.

    Echoing figures from CACI and Initially Immediate, revealed now, displaying a progress in lending to these getting their to start out with foot on the housing ladder, “first-time purchaser” was the Third-most looked for phrase on Ignite.

    At the opposite conclusion of the sector, searches for “most age” grew by 6% and have become a prime rated 4 lookup time period (up from ninth in February).

    Demand from clients for “shared possession” and “joint borrower sole proprietor” objects remained strong, with these phrases place eleventh and twelfth in March.

    Meanwhile, queries on behalf of shoppers trying to find a 2nd family grew by 7% in March, regardless of the Spring Spending plan announcement of a discount in funds positive factors tax on 2nd properties to essentially encourage homeowners to offer.

    L&G Property finance loan Products and providers head of things and transformation Jodie White claims: “While the mortgage loan market isn’t utterly out of the woods, the March info affords improbable objective to be cautiously optimistic.

    “Overall, train continues to be strong, and searches for among the further about situations queries (these as private debt administration concepts) are commencing to drop.

    “The stabilisation of swap and need premiums has carried out a major part in this – although the traditional fixed payment acquire-to-enable product was priced at 6.88% in August, it now sits at a considerably lower 5.52% in accordance to Moneyfacts.”

  • Unemployment rises in Australia | Australian Broker Information

    Unemployment rises in Australia | Australian Broker News

    Information

    Unemployment rises in Australia

    March sees slight work downturn

    Unemployment rises in Australia

    Abs has famous a modest elevate in the unemployment cost to three.8% in March.

    In March, the seasonally modified unemployment fee rose by a slight .1 share level to achieve 3.8%, with Ab muscle tissues noting a lower in employment numbers.

    “With work falling by throughout 7,000 individuals and the number of unemployed mounting by 21,000 folks right this moment, the unemployment value rose to three.8%,” stated Bjorn Jarvis (pictured over), head of labour knowledge on the Abs, in a media launch.

    The change in work figures adopted a surge in February and a slowdown in the previous two months. The common work-to-populace ratio additionally dipped by .2 share components to 64%, although the participation cost marginally lowered to 66.6%.

    Labour Current market Trends

    Inspite of the downturn, the labour business stays sturdy versus historic ranges.

    “The labour sector remained pretty tight in March, with an work-to-populace ratio and participation cost even now shut to their doc highs in November 2023 Jarvis,” Jarvis reported. “While they’ve each equally fallen by .4 share factors provided that then, they carry on to be considerably higher than their pre-pandemic ranges.”

    Several hours labored and underemployment

    Ab muscle tissues figures confirmed that full a number of hours labored in March noticed an improve of .9%. This restoration marks an enchancment in regards to the earlier months, with the yearly progress quantity in hrs labored reaching 1.7%, albeit even now trailing on the rear of the work development fee of two.4%.

    The underemployment value lessened just a little bit to six.5%, and the blended unemployment and underemployment costs, or the underutilisation value, stayed continuous at 10.3%.

    On the lookout on the traits

    The growth information for March indicated steadiness with the unemployment quantity holding at 3.9% for the fifth consecutive thirty day interval.

    “In growth phrases, the event cost in work and hours labored was weaker than the robust growth throughout late 2022 and early 2023. Having stated that, the the newest sample particulars proceed to stage to a restricted labour market place,” Jarvis said.

    Get the very best and freshest dwelling mortgage information despatched superb into your inbox. Subscribe now to our FREE day-to-day publication.

    Keep up with probably the most present data and actions

    Be part of our mailing checklist, it’s completely free!

  • Home loan fee move-as a result of slows | Australian Broker News

    Property finance loan worth move-by slows | Australian Broker News

    News

    Mortgage degree pass-via slows

    Tightening impacts lag powering {dollars} costs

    Mortgage rate pass-through slows

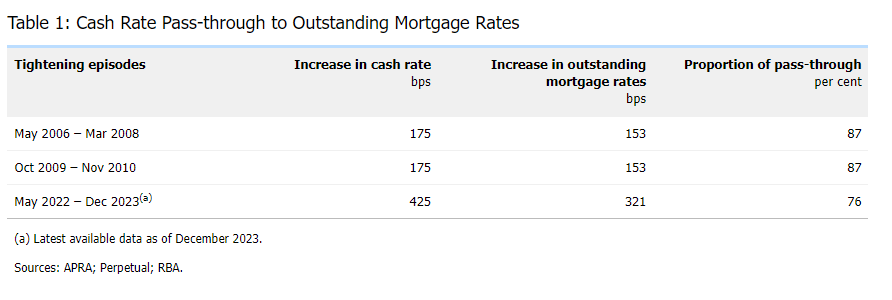
    As the Reserve Lender (RBA) lifted the arduous money fee goal by 425 basis factors from May 2022 to December 2023, the common distinctive house finance loan price elevated by round 320 foundation elements, reflecting a 75% move-by means of price.

    The lag in response when in comparison with prior tightening cycles in 2006 and 2009, through which nearly 90% of the funds fee boosts had been handed by method of, might be attributed to a excessive proportion of mounted-amount monetary loans and intensive mortgage lending degree of competitors, based on an RBA Bulletin.

    Impression of preset-charge loans

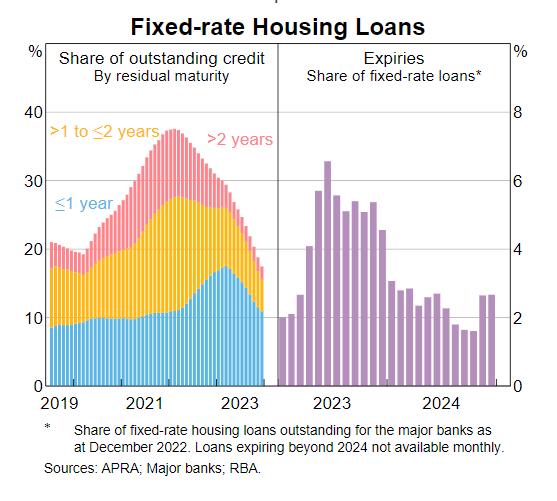
    A essential problem contributing to the slower go-by means of cost is the numerous share of set-amount house loans taken for the period of the COVID-19 pandemic at historically small premiums.

    “Many debtors took edge of the minimal mounted prices on provide by means of the COVID-19 pandemic to lock of their house loan repayments for a interval,” RBA acknowledged within the Bulletin.

    As these preset-price durations expire, these monetary loans are envisioned to reprice at bigger present-day variable fees, which can information to an enhance within the common improbable mortgage quantity.

    Mortgage loan lending opponents

    Another essential aspect affecting the move-via price is the heightened competitors amid mortgage collectors, notably within the latter 50 % of 2022 and early 2023, RBA documented.

    This opponents has led to the widespread mortgage loan cost on exceptional variable-price loans rising by round 75 basis elements significantly lower than the earnings price enhance.

    Financial establishments and different lenders have been aggressive in retaining high quality debtors by negotiating lower charges and providing incentives these as cashback specials and worth reductions.

    Future outlook

    The remaining inventory of lower-charge set mortgages is ready to run out throughout 2024, potential leading to a a lot extra full move-as a result of of {dollars} degree hikes to house finance loan prices, mirroring former financial tightening cycles.

    RBA expects the conventional improbable mortgage loan cost to rise by an extra 35 foundation elements in between December 2023 and December 2024, because the pace of set-amount loan expirations stays elevated within the 1st 50 p.c of the calendar 12 months.

    Economic implications

    Despite the slower first response, the impact of greater property finance loan costs on home money flows stays a sturdy channel by which financial coverage influences the broader monetary state.

    As extra set-charge monetary loans change to larger market prices, the entire scheduled house mortgage loan funds are projected to boost, maybe reaching all-around 10.5% of family disposable income by the shut of 2024.

    Summary

    The dynamics between money degree improves and mortgage loan worth adjustments spotlight the superior interplay of set-level monetary loan expiries, home loan lending competitiveness, and financial coverage. By the cease of 2024, the extent of pass-as a result of is anticipated to align with historic norms, reflecting the delayed however unavoidable impression of financial tightening on home loan debtors, RBA mentioned.

    To learn the RBA Bulletin in complete, take a have a look at the RBA web site.

    Get the most well liked and freshest mortgage loan information delivered supreme into your inbox. Subscribe now to our FREE every day publication.

    Maintain up with the newest information and gatherings

    Be a half of our mailing checklist, it’s free!