Tag: best?

  • Best money moves to make ahead of a Fed rate cut

    Fed Chair Powell is focused again on achieving a soft landing, says WSJ's Nick Timiraos

    Recent indicators that inflation is easing has paved the way in which for the Federal Reserve to begin chopping rates of interest as quickly as this fall.

    The shopper worth index, a key inflation gauge, dipped in June for the primary time in additional than 4 years, the Labor Department reported final week.

    “With plentiful indicators of a cooling financial system, the patron worth index for June definitely constitutes the ‘extra good knowledge’ on inflation that Fed Chair Jerome Powell has stated we want to see earlier than the Fed can start chopping rates of interest,” stated Greg McBride, chief monetary analyst at Bankrate.com.

    With a fall rate cut trying extra doubtless now, households could lastly get some aid from the sky-high borrowing prices that adopted the newest sequence of curiosity rate hikes, which took the Fed’s benchmark rate to the best degree in a long time.

    More from Personal Finance:
    High inflation is basically not Biden’s or Trump’s fault, economists say
    Why housing inflation remains to be stubbornly excessive
    More Americans are struggling at the same time as inflation cools

    Fed officers signaled they count on to cut its benchmark rate as soon as in 2024 and 4 further occasions in 2025.

    The federal funds rate, which is about by the U.S. central financial institution, is the curiosity rate at which banks borrow and lend to each other in a single day. Although that is not the rate shoppers pay, the Fed’s moves nonetheless have an effect on the charges they see every single day on issues resembling personal pupil loans and bank cards.

    “If you might be a shopper, now’s the time to say, what does my spending appear to be? Where would my money develop essentially the most and what choices do I’ve?” stated Leslie Tayne, an lawyer specializing in debt aid at Tayne Law in New York and creator of “Life & Debt.”

    Here are three key methods to contemplate:

    1. Watch your variable-rate debt

    With a rate cut, the prime rate lowers, too, and the rates of interest on variable-rate debt — resembling bank cards, adjustable-rate mortgages and a few personal pupil loans — are doubtless to observe, lowering your month-to-month funds.

    For instance, credit score cardholders may see a discount of their annual proportion yield, or APR, inside a billing cycle or two. But even then, APRs will solely ease off extraordinarily excessive ranges.

    Rather than look ahead to a small adjustment within the months ahead, debtors may swap now to a zero-interest stability switch bank card or consolidate and repay high-interest bank cards with a private mortgage, Tayne stated.

    Olga Rolenko | Moment | Getty Images

    Many householders with ARMs, that are pegged to a selection of indexes such because the prime rate, Libor or the eleventh District Cost of Funds, might even see their curiosity rate go down as properly — though not instantly as ARMs usually reset simply as soon as a yr.

    In the meantime, there are fewer choices to present householders with further respiratory room. “Your higher transfer could also be ready to refinance,” McBride stated.

    Private pupil loans additionally have a tendency to have a variable rate tied to the prime, Treasury invoice or one other rate index, which suggests as soon as the Fed begins chopping rates of interest, the rates of interest on these personal pupil loans will begin dropping.

    Eventually, debtors with current variable-rate personal pupil loans may additionally have the opportunity to refinance into a cheaper fixed-rate mortgage, in accordance to larger training skilled Mark Kantrowitz. 

    Currently, the fastened charges on a personal refinance are as little as 5% and as excessive as 11%, Kantrowitz stated.

    2. Lock in financial savings charges

    While borrowing will turn into cheaper, these decrease rates of interest will harm savers. 

    Since charges on on-line financial savings accounts, money market accounts and certificates of deposit are all poised to go down, specialists say that is the time to lock in some of the best returns in a long time.

    For now, top-yielding on-line financial savings accounts and one-year CDs are paying greater than 5% — properly above the rate of inflation.

    The alternative to earn 5% yearly on these money investments could not final for much longer.

    Howard Hook

    wealth advisor with EKS Associates

    “One factor it’s your decision to do is contemplate investing any idle money you will have into a higher-yielding money market fund,” stated licensed monetary planner Howard Hook, a senior wealth advisor with EKS Associates in Princeton, New Jersey.

    “Money market brokerage accounts normally pay larger charges than money market or financial savings accounts at banks,” he stated in an emailed assertion. “If the Fed is certainly trying to scale back charges 5 occasions over the following eighteen months (as at present projected), then the chance to earn 5% yearly on these money investments could not final for much longer.”

    3. Put off massive purchases

    If you are planning a main buy, like a residence or automobile, then it might pay to wait, since decrease rates of interest may scale back the fee of financing down the street.

    “Timing your buy to coincide with decrease charges can save money over the life of the mortgage,” Tayne stated.

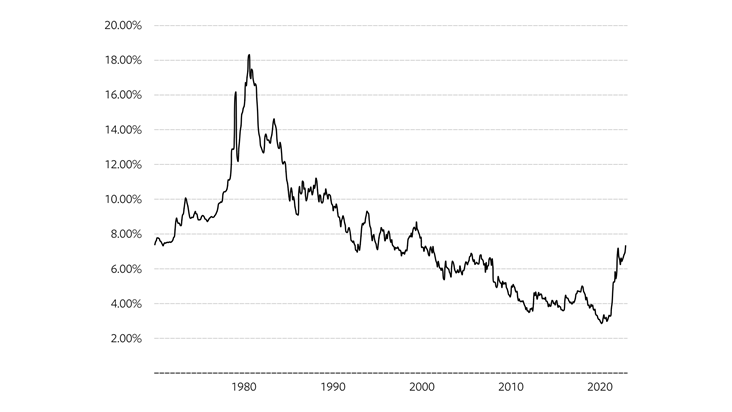
    Although mortgage charges are fastened and tied to Treasury yields and the financial system, they’ve already began to come down from latest highs, largely due to the prospect of a Fed-induced financial slowdown. The common rate for a 30-year, fixed-rate mortgage is now simply above 7%, in accordance to Bankrate.

    However, decrease mortgage charges may additionally increase home-buying demand, which might push costs larger, McBride stated. “If decrease mortgage charges lead to a surge in costs, that is going to offset the affordability profit for would-be patrons.”

    When it comes to auto loans, there isn’t any query inflation has hit financing prices — and car costs — onerous. The common rate on a five-year new automobile mortgage is now practically 8%, in accordance to Bankrate.

    But on this case, “the financing is one variable, and it is frankly one of the smaller variables,” McBride stated. For instance, a quarter-percentage level discount in charges on a $35,000, five-year mortgage is $4 a month, he calculated.

    In this case, and in lots of different conditions as properly, shoppers would profit extra from bettering their credit score scores, which may pave the way in which to even higher mortgage phrases, McBride stated.

    Subscribe to CNBC on YouTube.

  • Real estate stocks soar to best day of the year on rate cut bets

    The inventory market’s worst group is having its best day of the year as a cooler-than-expected inflation report stokes bets that the Federal Reserve will begin chopping rates of interest in September.

    Shares of actual estate firms jumped as a lot as 3.1% Thursday for his or her largest intraday acquire of 2024, climbing to their highest stage since March as buyers snap up homebuilder, digital and business actual estate stocks alike. Real estate is also the best-performing group in the S&P 500 Index Thursday, with quantity that is round 65% greater than the 30-day common, in accordance to information compiled by Bloomberg. 

    Arguably the most important information to come from the newest shopper worth index studying was a pullback in housing-related inflation. Shelter prices rose simply 0.2% for the slowest month-to-month enhance in three years. Homebuilders, which have risen 6% this year, are up practically 7% for the session. Shares of D.R. Horton Inc., which is scheduled to report earnings subsequent Thursday, gained as a lot as 7.4%. 

    “Housing has actually been the final shoe to drop in phrases of profitable the battle towards excessive inflation,” Preston Caldwell, chief U.S. economist at Morningstar wrote in a observe to purchasers Thursday. “Leading-edge information has strongly indicated for a while now {that a} fall in housing inflation was in the works.”

    A rally in actual estate stocks is unhealthy information for brief sellers who’ve been piling into the group, which is the worst performer in the S&P 500 this year. To begin the week, quick curiosity as a proportion of float hovered close to 49% in the SPDR Homebuilders ETF, the highest stage since February for the exchange-traded fund, in accordance to information from S3 Partners.

    Property house owners are rallying as nicely. Real estate funding trusts, which have been brutally penalized throughout the two-year run up in borrowing prices, superior by as a lot as 3%. The outlook for the group seems to have turned a nook, in accordance Rich Hill, senior vice chairman and head of actual estate technique and analysis at Cohen & Steers Capital Management.

    “We assume this can be a compelling backdrop for listed REITs particularly as elementary development stays on stable footing,” he mentioned, referencing the newest inflation information and rate outlook. “The rally that began in October of 2023 pushing returns greater than 20% above their trough seems set to proceed if inflation cools and rates of interest proceed to decline.” 

    Shares of industrial REIT Prologis Inc., which experiences second-quarter outcomes on Tuesday, rose as a lot as 3.6% to hit their highest intraday stage since April. U.S. Treasury yields tumbled, with the 10-year bond falling beneath 4.2% and the policy-sensitive two-year observe slipping to 4.5%.

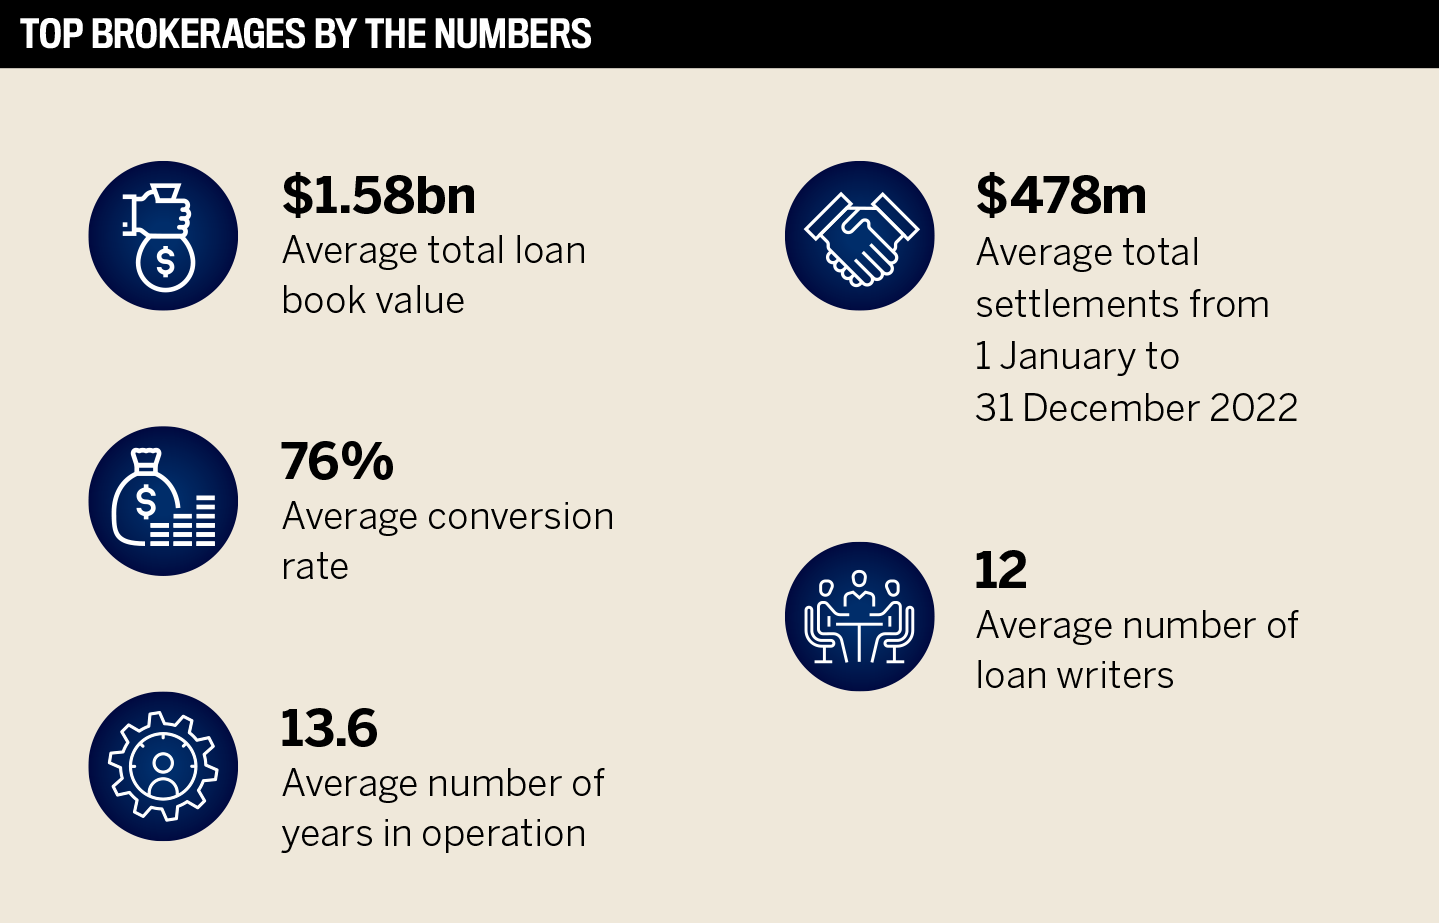
  • The Best Mortgage Brokerages in Australia


    focusing on area of interest clientele
    upskilling brokers and group members
    strategic planning


    While all have their very own secrets and techniques to success, every brokerage is resolute in its want to be a trusted trade associate to its prospects.

    Top Brokerage rank: 25

    Location: Liverpool, NSW

    Years in operation: 7

    Conversion fee of loans settled or written: 82% 


    While Rethink Financing is at the moment using excessive, it’s set to go even larger. It has constructed its title on business property investing and being a associate to its purchasers coping with:


    advanced constructions
    self-employment
    belief corporations
    SMSF


    Rethink managing director Son Pham says, “We’re not transactional. We’re about wealth constructing. Our purchasers don’t come to us saying they need the bottom fee. They need one other property; they wish to construct their portfolio and wish funding.”

    The agency has developed deep experience as a result of complexity of its purchasers having a number of properties.

    “We perceive their long-term imaginative and prescient of what they wish to do, and we clarify how we’re going to utilise sure lenders to get them the place they should go. We might must go to 1 lender first earlier than we get to the following spot,” says Pham.


    Son Pham, Rethink Financing

    “We’ve come a great distance in a brief period of time. My group is best than the typical dealer; they’re writing greater than the typical dealer, and I’m very pleased to see the place we’re headed”

    Son PhamRethink Financing


    Commonly, purchasers first encounter Rethink after being referred as a result of different brokerages being unable to assist them.

    “I adore it when somebody says, ‘I’ve spoken to a few brokers, and none of them can do it’,” says Son. “Then I actually look into it and go, ‘I feel it’s attainable.’ I may not get there straightaway, however with a little bit of digging and restructuring, we will make it occur.”

    The 10-strong broking group usually workshops offers in order to search out these options. Typically, Rethink’s purchasers make up about 1% of the market and have a number of funding properties.

    “Sometimes you may’t use an ordinary financial institution as a result of their insurance policies begin charging you these investor loadings, and banks have to carry extra capital reserves once they’ve acquired extra publicity to a shopper. It does put extra strain on me, however I just like the problem.”

    Post-pandemic situations have additionally pushed the agency’s development, as it will possibly now signal offers electronically, that means it will possibly work with prospects nationwide.


    While having the ability to entry extra of its area of interest goal purchasers is optimistic, discovering brokers with the talent set to help them is difficult. Most of the main business brokers are employed by banks.

    “They usually don’t transfer except we pay them massive cash,” says Pham. “We’ve been discovering residential brokers with expertise who wish to study and be higher, so I convey them on board. I put them by way of coaching and mentoring with myself, and the suggestions is that it’s very intense and a giant studying curve.”

    That upskilling is ready to proceed throughout the brokerage because it prepares for a relaunch later this 12 months. Under Pham’s management, there’s a detailed plan that goals to construct the enterprise out and seize a slice of the residential market.

    “All I say is ‘be careful’ for all these different companies on the market,” Pham says. “People are all the time looking for professionals who know a bit extra to assist them get extra. We have the experience and information, and the group is sweet. We’re going to increase lots in that house – that’s the large plan for the following 12 to 24 months.”


    Top Brokerage rank: 47

    Location: Mount Waverley, Victoria

    Years in operation: 4

    Conversion fee of loans settled or written: 66


    Weme Finance director and principal finance dealer Joanne Liu isn’t stunned by her brokerage’s development, as she was her personal goal buyer. Previously working in a company function and as an authorized observe accountant, she might see her friends wanted mortgage brokers to fulfill their wants.

    “Coming from knowledgeable background, I wished to assist folks like me,” Liu says. “Even although I had a grasp’s diploma in banking finance and the information, I didn’t have the time to handle my very own mortgage.”

    Weme was created to focus on professionals comparable to legal professionals, medical doctors, accountants, and many others. Liu additionally pitches in direction of self-employed enterprise house owners, as her accounting abilities imply she will be able to decipher their financials and perceive their limitations. All eight of the agency’s brokers share the identical background as Liu.

    “That’s the principle level of distinction; we’re a band of people who find themselves coming from finance and accounting backgrounds,” says Liu.

    With such a focused buyer base, Weme should function accordingly. It is open to reserving conferences between 9 p.m. and 11 p.m.

    Liu says, “We make ourselves accessible even at weekends, particularly for that first assembly, to know their objectives and present them the attainable choices. They’re tremendous busy, however we accommodate them, as I consider it’s much better to fulfill one another to kind a bond and create a sticky relationship.”


    Joanne Liu, Weme Finance

    “We spend lots of time educating our purchasers and explaining the attainable options, however we additionally inform them the main points in order that they know why”

    Joanne LiuWeme Finance


    The main driver of the brokerage’s success is Liu’s dedication. She based the enterprise on 6 June 2020, had her accreditation by the tip of July and had her first shopper by August.

    By the tip of the primary monetary 12 months, Weme had settled 50 loans, after which this rose to over 100 in the second. The brokerage is at the moment doing over double that.

    “We cope with lots of advanced instances and complex constructions; that’s how I’ve additionally made the brokerage totally different,” says Liu.

    Getting these tough instances over the road isn’t the tip level for Weme. Liu has instilled a deeply service-oriented mindset.

    She says, “We all the time consider we have to present excellent service to the purchasers, as lots of brokers deal with simply profitable enterprise.”

    Weme prides itself on presenting purchasers with a spread of choices and letting them select what’s finest for them.

    “We don’t promise something we will’t ship, and we don’t push folks to take the choice that we want. Everything is clear, and we make the shopper perceive utilizing easy language, so what they select is in their finest curiosity, not ours,” says Liu.

    Another function of Weme’s service is monitoring every shopper’s scenario and reaching out to see if one thing else might be completed.

    Liu says, “Maintenance doesn’t create any income, but it surely does create potential income in the long run.”


    Top Brokerage rank: 50

    Location: Canberra, ACT

    Years in operation: 4

    Conversion fee of loans settled/written: 72%


    Loan Market Canberra’s success permits its folks to play to their talent units.

    Franchise proprietor Nitish Kumar says, “Most brokerages get so caught up in admin, so one of many massive issues I wished after I began the enterprise was for brokers to have the ability to deal with the shopper and never fear in regards to the backend. That’s why we constructed out a extremely massive admin group.”

    This has a twofold profit:


    Brokers deal with being in entrance of the shopper
    The shopper will get an enhanced service expertise and might attain their dealer far more simply


    The second arm of Kumar’s overarching technique was to make sure that brokers had been as productive as attainable with their clearer schedules.

    “It’s vital for me that the brokers aren’t working six or seven days every week. I make it possible for they’ve a great work-life stability and might spend time with their households.”


    Nitish Kumar, Loan Market Canberra

    “The group deserves all of the credit score for every thing we do. When I decide, I take into consideration whether or not it’s going to assist somebody keep in the enterprise. As lengthy as my North Star is attempting to retain as many individuals as attainable, it typically tends to be the appropriate determination”

    Nitish KumarLoan Market Canberra


    To this finish, Loan Market Canberra operates a nine-day fortnight, giving these with kids or different commitments a day again solely for them.

    The fast rise of the brokerage isn’t right down to probability; Kumar had a clearly outlined blueprint from inception.

    “I began with ‘What does 2030 seem like?’ And then I labored backwards so I considered all the issues.”

    The constructing blocks are:


    20 brokers
    avoiding burnout by selling work-life stability
    massive admin group to take the load
    finish goal of $1 billion yearly (2,000 loans)


    Remarkably, each particular person in the enterprise has come in by way of referral, fortifying the interior environment.“They are routinely a part of the tradition as a result of they already know somebody, and that particular person finally ends up taking accountability for inducting them into the enterprise,” says Kumar. “We know {that a} employees member wouldn’t suggest an individual who’s not going to be good.”


    Loan Market Canberra sees most of its employees selecting to return to the workplace day by day, though they do have the choice to work remotely.

    Kumar has correspondingly moved right into a supervisory function, devoting time to fixing advanced instances as a result of his expertise.

    He says, “When I had purchasers, my capacity to truly be accessible was fairly restricted, so the concept behind getting off the instruments was to have a bit extra time. But the brokers all assist one another and are available collectively if they should discover a resolution. If they’re actually struggling, then I find yourself being the final resort, however we undoubtedly aren’t arrange in a manner the place I’m the primary resort.”


    From the Sponsor

    Bankwest has the ambition to be one of the best dealer financial institution in Australia and continues to help brokers in the crucial function they play in enhancing prospects’ monetary wellbeing throughout the nation. This is among the many explanation why sensible brokers select Bankwest. 


    Ian Rakhit, General Manager, Third Party BankingIan Rakhit 

    General Manager 

    Third Party Banking


    Top Brokerages 2024


    1. Simplicity Loans & Advisory
    2. The Australian Lending & Investment Centre
    3. (tie) Tiffen & Co
    3. (tie) AUSUN Finance
    5. Loan Gallery Finance
    6. Acceptance Finance
    7. My Mortgage Freedom
    8. (tie) Clarity Financial Group
    8. (tie) XIN Mortgage
    10. Green Finance Group
    11. Shore Financial
    12. Smartmove Professional Mortgage Advisors
    13. Empower Wealth
    14. Bernie Lewis Home Loans
    15. Aussie Prospect
    16. Azura Financial
    17. Podium Money
    18. Masters Broker Group
    19. Advanced Finance t/a Better Choice Mortgage Services
    20. (tie) AXTON Finance
    20. (tie) The Loan Company
    22. (tie) Mortgage Finance Solutions
    22. (tie) BlueRock Finance
    22. (tie) Entourage
    26. Pivotal Financial
    27. Aussie Gawler
    28. Absolut Financial
    29. Loan Market Razor
    30. (tie) Mortgage Choice Glenelg
    30. (tie) Mason Finance Group
    32. Loan Market Geelong City
    33. (tie) Original Wealth
    33. (tie) Aqua Financial Services
    35. Aussie Belmont
    36. Napoleon Finance
    37. (tie) DPN
    37. (tie) Loan Market New Farm
    39. (tie) Aussie Toukley
    39. (tie) Aussie Moonah
    41. InReach Finance
    42. North Coast Lending
    43. Aussie Launceston
    44. UFinancial
    45. Aussie Ipswich
    46. Aussie Townsville
    48. Aussie Berwick
    49. Mortgage Choice Indooroopilly

    Top Brokerages 2024 – Listing in order


    1. Simplicity Loans & Advisory
    2. The Australian Lending & Investment Centre
    3. (tie) Tiffen & Co
    3. (tie) AUSUN Finance
    5. Loan Gallery Finance
    6. Acceptance Finance
    7. My Mortgage Freedom
    8. (tie) Clarity Financial Group
    8. (tie) XIN Mortgage
    10. Green Finance Group
    11. Shore Financial
    12. Smartmove Professional Mortgage Advisors
    13. Empower Wealth
    14. Bernie Lewis Home Loans
    15. Aussie Prospect
    16. Azura Financial
    17. Podium Money
    18. Masters Broker Group
    19. Advanced Finance t/a Better Choice Mortgage Services
    20. (tie) AXTON Finance
    20. (tie) The Loan Company
    22. (tie) Mortgage Finance Solutions
    22. (tie) BlueRock Finance
    22. (tie) Entourage


    26. Pivotal Financial
    27. Aussie Gawler
    28. Absolut Financial
    29. Loan Market Razor
    30. (tie) Mortgage Choice Glenelg
    30. (tie) Mason Finance Group
    32. Loan Market Geelong City
    33. (tie) Original Wealth
    33. (tie) Aqua Financial Services
    35. Aussie Belmont
    36. Napoleon Finance
    37. (tie) DPN
    37. (tie) Loan Market New Farm
    39. (tie) Aussie Toukley
    39. (tie) Aussie Moonah
    41. InReach Finance
    42. North Coast Lending
    43. Aussie Launceston
    44. UFinancial
    45. Aussie Ipswich
    46. Aussie Townsville


    48. Aussie Berwick
    49. Mortgage Choice Indooroopilly


  • 3rd of people back again Labour to very best support FTBs, says Moneybox – House loan Finance Gazette

    A 3rd of people imagine Labour is the get collectively very best put to steering initially-time customers (FTBs), a Moneybox survey reveals.

    first-time-buyers-620x330.jpg

    The conserving and investing app’s newest analysis of 1,000 aspiring residence-homeowners all through the British isles discovered that 28% of respondents admitted they by no means place confidence in any political get collectively to support them purchase a house of their private, and solely 8% really feel the Conservatives have their back again. The Liberal Democrats and Inexperienced Bash noticed solely 4% and three% FTB help respectively.

    In the meantime, it confirmed that two-thirds (66%) of aspiring FTBs have reevaluated their homeownership goals within the earlier 6 months, with half (51%) now planning to purchase at a afterwards day.

    The common FTB has been saving for 2 a few years and 10 months and expects to be outfitted to acquire their first family in 4 a very long time and 6 months, an increase from 4 many years and two months in 2023.

    FTB self esteem has wavered within the facial space of persistent expense of dwelling worries and market volatility, with 41% admitting they’re feeling pessimistic about their chance of beginning to be a house owner, rising from 37% a 12 months back and 21% in 2022.

    Over 50 % stated that is primarily as a result of the value of dwelling has eroded their disposable cash, producing it tougher to protect a deposit although 51% are disheartened due to the actual fact of mounting home expenses and 37% are frightened that giant curiosity premiums have manufactured mortgages rather more unaffordable.

    Even so, 35% report they carry on to really really feel optimistic about their property buying methods with 21% assured they are going to get on the housing ladder irrespective of the at any time-transforming ecosystem.

    The most notable drivers of their optimism consist of the notion that curiosity premiums will get began to arrive down this summer season (26%), the fee of dwelling catastrophe is slowing down, and anticipation of help measures an incoming authorities would possibly introduce subsequent the frequent election (18%).

    On the opposite hand, unavoidable cash pressures have meant that FTBs at the moment are preserving 18% considerably much less towards their first residence deposit than a 12 months in the past, down from £344 to £286 a month, and 1 / 4 (26%) have had to dip into their hard-earned deposit monetary financial savings to shield unanticipated expenses.

    Regardless of these difficulties, proudly proudly owning a residence is further necessary than at any time for 79% of FTBs. Two-thirds (62%) imagine staying a house proprietor is crucial to acquiring monetary safety though 55% are largely motivated to acquire to escape the more and more dear rental business, up from 48% in 2023.

    Dollars price financial savings have remained the commonest means FTBs save for a deposit concerning the a very long time, ordinarily working with a combination of simple accessibility worth financial savings accounts (42%), Income ISAs (29%), and the Lifetime ISA (22%).

    In the meantime, very reasonably priced homeownership strategies have all come to be fewer well-known within the earlier six months with the amount considering the Very first Residences Scheme or Rent-to-purchase/Hire-to-own falling in extra of the calendar 12 months from 31% to 22%, and 26% to 20% respectively. Only 9% talked about they ended up fascinated about the Home finance loan Promise Scheme.

    Moneybox head of personal finance Brian Byrnes claims: “With the Normal Election simply all-around the nook, manifesto pledges from political occasions have fallen brief of giving considerably-needed reassurance and tangible economical steering to FTBs who’ve been navigating main worries across the final couple a few years.”

    “With dwelling worth progress significantly outpacing wage progress in fashionable many years, the strategies required to sustainably enhance homeownership with out extra inflating family promoting costs are sophisticated and can take a while to bear fruit. That is why we at Moneybox are contacting for the incoming governing administration to commit to pragmatic steps that may be despatched within the round time period, these varieties of as lengthy term-proofing the Life time ISA.”

  • Why waiting to obtain a household may not be very best

    &#13
    &#13

    The dream of homeownership is deeply embedded in fairly a few individuals’s aspirations. But, with reworking sector circumstances, some potential consumers may properly ponder waiting. Though distinctive situations should usually guideline your conclusions, listed below are good the explanation why delaying may probably not be in your very best curiosity:

    The unpredictable nature of curiosity costs

    Present-day fascination costs may be moderately greater than the file lows of newest many years, making some doable consumers cautious. But let’s embrace some viewpoint: predicting potential want charges is a in shut proximity to-extremely exhausting exercise. Waiting for an ‘best’ cost can be akin to playing. If you would possibly be apprehensive about present costs, it actually is worth noting that current day charges, within the grand sweep of home mortgage background, proceed to be significantly lower than a lot of highs we have now discovered.

    And this is wherever Evergreen House Financial loans strategies in with a {powerful} incentive. By selecting to buy now, you’ll be able to revenue from our Buyer Booster Plan*, accessible until September twenty ninth, 2023. This distinctive methodology delivers you with a $2,500 mortgage firm credit score rating for a long term refinance. Even although you’re leveraging aggressive rates of interest at present, you would possibly be additionally surroundings by your self up for potential monetary financial savings sooner or later—a {powerful} objective to act now.

    The worth of making fairness now

    Every dwelling finance mortgage fee you make builds equity in a tangible asset. By delaying a residence purchase, you would possibly be lacking out on this prosperity-constructing likelihood. This is particularly important when pondering of the appreciation of dwelling values in a number of areas.

    The hid prices of leasing

    Leasing may properly really feel charge-powerful brief-expression, however greater than the a number of years, it may be a numerous story. Hire funds create your landlord’s prosperity, not yours. With rents usually escalating, often surpassing inflation prices, you may properly find yourself spending significantly extra with out having any return in your expenditure.

    The intangible advantages of homeownership

    Outside of funds, homeownership presents immeasurable rewards. The safety, freedom to personalize your room, and a sense of belonging in a neighborhood are simply a variety of. Postponing a dwelling spend money on would possibly suggest missing out on these enriching ordeals.

    Closing concepts

    Selecting to buy a dwelling is main, affected by a number of issues. But if you have a look at the present present market traits, the current want charges, and the choice to construct equity coupled with our distinctive Customer Booster Software*, there’s definitely a persuasive argument for turning into a dwelling proprietor quicker alternatively than later.

    For tailored recommendation, contact your native Evergreen lender these days! Let us get you into your want residence.

    *Offer legitimate on purchase monetary loans beneath deal and refinance monetary loans shut regarding 7/1/2023 and 9/29/2023. The expert borrower(s) will obtain one $2,500 mortgage supplier credit score historical past certification redeemable in direction of a refinance on the very same property. Provide is non-transferrable, would possibly not be utilized to different transactions, and would possibly not be blended with a pricing concession. The refinance software date ought to be on or forward of three/31/2025. The borrower ought to have designed not less than six (6) consecutive on-time funds on the order mortgage upfront of closing the refinance. This is not a dedication to lend. Method is material to alter with out having detect. Not all candidates will qualify. Not all merchandise provided. More phrases, circumstances, and limits may properly implement. Call for specifics.

    ©2023 Evergreen Moneysource Home mortgage Company® NMLS ID 3182. Equal Housing Financial establishment. Trade/firm marks are the house of Evergreen Home Financial loans. All authorized rights reserved. Be certain to see www.evergreenhomeloans.com/licensing for licensing details.

    &#13

  • 5 Best Suggestions for Initially-Time Property Investors in Australia

    Australia’s genuine property market offers an enormous assortment of monetary funding alternatives and the possible for sturdy returns. As a 1st-time property dealer in Australia, making educated conclusions about your expense is important for a efficient and worthwhile expenditure journey. To help you navigate the whole world of residence expenditure for the initially time, in this text are 5 main tips, from deciding on the correct property to controlling your expense proficiently.

    3-Jun-12-2024-01-57-35-9358-AM

    1. Obtain very properly to begin with

    The essential to any productive residence monetary dedication journey lies in acquiring the appropriate house in the appropriate place on the appropriate promoting value. Below are some issues to contemplate in your look for for the correct funding home:

    Location: Appear for spots with vital rental demand, superior infrastructure, and alternative for future development.
    Assets variety: Select homes that attractiveness to a broad fluctuate of tenants, equivalent to flats close to to neighborhood transportation or properties in family-pleasant suburbs.
    Rate: Invest in at a aggressive value. Conduct complete investigation to realize an comprehending of the sector. Assess newest income in the placement and negotiate appropriately.

    2. Pick out an funding determination methodology

    Most home merchants decide to commit for simply considered one of two causes, and your monetary dedication system will handbook your residence vary and property administration tactic.

    Buying for money acquire: Cash receive is when the value of a house boosts in extra of time, making it attainable for you to make use of the fairness (the variance among the many worth of the home and the way rather a lot monetary debt you owe on the mortgage mortgage) to finance issues like acquiring an additional monetary funding home, heading on vacation, renovating your family or buying a brand new car. Or you would possibly choose to supply the property to return a monetary acquire.
    Acquiring for money transfer: Cash motion is the rental income you purchase from renting out the property to a tenant. If the rental money circulate addresses your prices, this sort of as house finance mortgage repayments, upkeep bills and residential administration service charges and so forth., the property successfully offers an extra supply of earnings that may be utilized for discretionary shelling out, to pay again payments or help pay out down bank card debt on your loved ones members house.

    3. Handle it like an organization

    When it arrives to investing in property, tactic your picks with a small enterprise mentality, using logic and monetary investigation considerably than ideas.

    Stick to a cash plan: Established a value vary, forecast your attainable returns, and put together for expenditures.
    Take the emotion out of ultimate determination producing: Steer away from deciding on attributes depending on personal preferences. Instead emphasis on what is going to draw in tenants and ship one of the best returns.
    Maintain stringent fiscal protocol: Continue to maintain thorough paperwork of all transactions and expenditures related to the property.

    4. Have an understanding of your rights and obligations as a landlord

    Currently being a landlord comes with a wide range of authorized obligations and it’s obligatory you familiarise your self together with your authorized rights and obligations to make sure compliance and avoid any disputes.

    Fully grasp the (*5*) Tenancies Act in your state or territory, which embody the rules all-around leases, bond, lease will enhance, and eviction procedures.
    Assure your residence meets all safety benchmarks, is nicely-preserved and perform frequent inspections and properly timed repairs.
    Connect clearly and fairly together with your tenants and cope with their considerations promptly to foster a optimistic marriage.

    5. Get a bunch of pros in your facet

    Handling an funding determination property as a 1st-time property investor can really feel an excessive amount of to deal with. So encompass you with gurus who can current useful steering and suppliers and assist make your property monetary dedication journey smoother.

    Get monetary recommendations from a house mortgage dealer who can allow you safe one of the best financing options for your monetary dedication home.
    Retain the providers of a residence supervisor, this sort of as people at Harcourts Assets Management, to amass care of the day-to-day duties, together with tenant screening, lease assortment, servicing, and licensed compliance.
    Enlist the services and products of an accountant to allow you navigate tax implications and make certain you maximise your funding determination returns.

    Get ready to commit in residence

    For extra tailored recommendations on funding your 1st monetary dedication residence or increasing a home portfolio, get in contact with a House mortgage Categorical house mortgage dealer close to you.

    When all remedy has been taken in the preparation of this publication, no assure is given as to the precision of the information and no duty is taken by Finservice Pty Ltd (Home mortgage Express) for any errors or omissions. This publication doesn’t represent personalised financial info. It is probably not pertinent to specific particular person circumstances. Nothing in any respect in this publication is, or ought to be taken as, an present, invitation, or suggestion to get, promote, or maintain any funding in or make any deposit with any human being. You ought to search skilled recommendations simply earlier than getting any movement in relation to the issues dealt in this publication. A Disclosure Assertion is available on ask for and completely freed from value.

    Finservice Pty Ltd (Home mortgage Specific) is authorised as an organization credit score rating marketing consultant (Company Credit rating Representative Quantity 397386) to engage in credit standing routines on behalf of BLSSA Pty Ltd (Australian Credit rating Licence vary 391237) ACN 123 600 000 | Complete member of MFAA | Member of Australian Economical Complaints Authority (AFCA) | Member of Preference Aggregation Products and providers.

  • Best locations to get an HMO in the United kingdom.

    12-06-2024

    Ideal locations to buy an HMO in the Uk.

    In this write-up, we look at the biggest spots to buy an HMO in the British isles. 

    This listing has considered as plenty of components together with locale, produce, regeneration, demand and different variables which have helped us to arrive up with our high rated 10 spots to get an HMO in the United kingdom.

    Criteria for a glorious place to make investments in an HMO

    If you might be trying to find a glorious HMO home, the produce can help you establish if the rental cash is really value the outlay to receive the home. 

    We have considered an maximize in rental yields greater than the earlier 12 months, outpacing property values. 

    When evaluating a spot to make investments in an HMO there are a lot of essential components any investor have to consider.

    Length out of your residence sort out. – How accessible is the residence from your home tackle, consider how usually you could want to have to pay a go to to the belongings. If you’re a fingers-on landlord dealing with lettings and servicing by your self then this may bear much more fats than a hands-off landlord working with a entire-provider lettings agent. 


    Obtaining home in an space you’ll be able to entry typically can help you develop up your community with product gross sales and lettings brokers. A superior community of home trade specialists can help you uncover off trade alternatives. 


    Your close by consciousness of the space. – How effectively are you aware the regional trade dynamics in that spot? Local dynamics can contain variations to organising constraints in addition to new infrastructure that will effectively impression letting want a majority of these as new hospitals, faculty growth or head workplaces for a primary employer, all of which may regulate the allowing dynamics of an place. 


    Area experience of an location could possibly be for the cause that of acquiring kids who’ve examined & lived in the space, possibly you grew up in or have family members in the place. Neighborhood experience can help detect good and horrible locations of a Metropolis/Town and proceed to hold educated of latest developments which have an impression on residence costs and tenant need. 


    Tenant demand from prospects. – Tenant demand is crucial as you need to keep away from void intervals. Know who you’ll rent to and what demand from prospects there may be in the house. Are there any imminent enhancements to the make up of an area which may carry in contemporary demand for permitting on your HMO. Becoming knowledgeable of a space councils housing designs is a helpful approach to detect impending areas. Also ponder regeneration applications for the spot and modifications to brief article 4 locations. 


    Post 4 organising. Report 4 requires a property to go by way of scheduling to modify from residential Course 3 to HMO use course C4 and is made to management the place and the way quite a few qualities are allow as an HMO. Obtaining a belongings and changing a belongings into an HMO earlier than submit 4 regs come into stress generally is a shrewd go. 

    Leading 10 locations to make investments in an HMO in the Uk. 

    Considering all the above elements and having data from our landlords as successfully as particulars from the trade, these are our prime 10 locations to spend in an HMO property in the United kingdom. 

    Edinburgh, Scotland’s funds, is the UK’s most economically efficient metropolis outdoors the home London. Unemployment has halved in the ultimate decade and common shell out is larger than the different 8 massive Towns outdoors the home of London. 

    Edinburgh has 6 universities with over 55,000 learners. Whole time faculty college students make up over 12% of Edinburgh’s inhabitants. 

    Ideal locations for HMO in Edinburgh are Bruntsfield, Marchmont, Morningside & Newington

    The typical dwelling worth in Edinburghis £334,000. 

    All residence charge data in this posting is taken from rightmove. 

    Cardiff has good transportation one-way links, 3 universities and has undergone an excessive amount of regeneration in trendy years. Cardiff is a favorite amid a lot of our landlords with properties in the Cathays area of Cardiff. There is a implausible mix of residence worth and generate in Cardiff. 

    Finest areas for HMO in Cardiff are Cathays & Plasnewydd.

    The common residence price ticket in accordance to Rightmove is £291,000. 

    Durham is a shocking Metropolis surrounded by the river Weare. It is residence to Durham faculty and the HMO properties beneath are sometimes allow to college students. 

    Most efficient locations for HMO in Durham County are in Durham City in close to approximation to the college. HMO yields notice about 9% gross proper right here. 

    The typical home worth in Durham is £194,036 creating it a reasonably priced Town for many landlords. 

    Cambridge is in fact home to one specific the handiest universities in the globe. The Cambridge faculty ranks fifth in the setting in the QS rankings. The pupil populace is round 24,000. Cambridge residence costs are usually stable.

    In accordance to the ONS residence promoting costs improved 3.5% 12 months on 12 months incomes this a powerful area for funds appreciation. Rents had been being up to for the similar time frame rising by 7.6%.

    The unusual residence price ticket in Cambridge is £605,261.


    Bristol is a implausible location to keep, actually do not simply think about our time period for it, this report in the Impartial ranked Bristol as an individual of the prime spots for youthful people to keep outdoors of London. The metropolis has two planet-class universities. Bristol is residence to some primary firms a majority of these as Ovo Group, Airbus and Hargreaves Lansdown. 

    Some of the finest areas for HMO in Bristol include Southville, Southmead, Bedminster, Filton & Clifton.

    Bristol ranks choice 1 in Aldermore’s buy to allow metropolis tracker for 2024.  

    The common residence value in Bristol is £384,414.


    Manchester is the main metropolitan place exterior of London and presents a balanced financial local weather anticipated to improve by 2.5% from 2024 – 2026 (third place at the rear of London and Birmingham).

    Manchester has a sturdy profession trade, and a big scholar inhabitants. There are greater than 100,000 college students dwelling in Increased Manchester together with 27,000 overseas learners. 

    With a sturdy monetary system and better pupil numbers demand from prospects for HMO is implausible. Manchester ranks subsequent in Aldermore’s make investments in-to-permit metropolis tracker. 

    The common home worth in Manchester is £300,282.


    Birmingham has the most vital financial output outdoors of London, largely dominated by the service sector. The metropolis can also be residence to 8 universities and has a scholar populace of approx. 80,000. The metropolis is in the system of massive regeneration with billions changing into spent on the metropolis centre, railways and the airport. 

    A report from JLL expects residence costs to elevate 27% by 2026 incomes Birmingham one in every of the high locations in the British isles to commit in property. 

    The unusual residence worth in Birmingham is £272,937.

    Portsmouth is a college metropolis and with in extra of 25,000 learners the spot has sturdy tenant demand from prospects. In accordance to the ONS personal rental prices improved 12% yr on 12 months in Portsmouth. 

    The finest HMO spots are central locations a majority of these as Southsea and Fratton.

    Portsmouth would make it into Aldermore’s main 10 get-to-permit metropolis tracker at quantity 7.


    The unusual family price ticket is £283,803 in Portsmouth. 


    Coventry College gives in over 30,000 faculty college students and that need presents it the selection 3 location in Aldermore’s get-to-permit metropolis tracker. 

    The most well-known spots for HMO are in the Northeast of the metropolis involving Coventry college and Coventry University. 

    In accordance to the ONS property promoting costs are up 2.4% yr on 12 months and rents are up 10% round the identical time frame. 

    The unusual residence value in Coventry is £241,809.

    A College City with some 25,000 moreover college students. Sunderland will make our document because it ranks high for yield in a 2024 Zoopla report with a generate of for an typical BTL (regular AST allow) of 8.96% (regular rent £626pm and property worth £83,842). The regular residence charge is at the lower conclusion of the scale for the Uk and due to this fact could possibly be enticing to these individuals on a lesser worth vary.

    So, there we have now it, our greatest 10 locations to make investments in an HMO belongings in the British isles. Ideally this report has supplied you some insights and is effective in incomes your HMO expense selections. 


    Fox Davidson.

    Fox Davidson are a consultant HMO Mortgage mortgage Broker. We have been advising buyers on HMO funding selections for residence throughout the United kingdom for greater than 10 a long time. To discuss HMO residence loans make certain to merely name or complete our small enquiry kind. 

  • Best mortgage rates today | Fixed rates from 4.32%

    Santander lowers a few of its fastened mortgages rates.

    Back in December 2021, the Bank of England’s base charge sat at 0.1%. Since then, it has elevated 14 consecutive occasions to five.25% because the UK fought rocketing inflation. 

    These will increase have put pressure on the property market, with mortgage rates following the same trajectory. So in case you’re available in the market for a brand new deal, then we’ve listed a few of the greatest rates under. 

    Remember, evaluating the most effective mortgage rates in the marketplace could be a good way to analysis your borrowing choices. However, it’s key to contemplate different components too. 

    This article explores:  

    *This article could comprise affiliate hyperlinks that earn us income

    Will I pay extra for my mortgage in 2024?

    Most debtors coming off fastened charge offers shall be paying extra on their mortgage this yr. 

    This is as a result of the Bank of England’s base charge now sits at a 15-year excessive, and was a lot decrease when these debtors final sought a set charge deal. 

    Back in June 2022, the standard two yr fastened mortgage charge was 3.25%, in line with Moneyfacts, a knowledge agency. This meant somebody borrowing £250,000 over 25 years would pay round £1,218 a month for that preliminary time period. 

    Fast ahead to today, and somebody borrowing the identical quantity on this time period would pay round £381 extra a month. 

    Likewise, the typical 5 yr fastened deal has risen from 2.85% in June 2019 to five.49% this month. On the identical £250,000, this represents a close to £370 enhance on the typical month-to-month mortgage cost.

    The excellent news is that these are simply common figures, and extra aggressive rates exist if you perform a little analysis.

    Read extra: Six steps to contemplate in case your fixed-rate mortgage deal is ending quickly

    Consult an skilled mortgage dealer and discover the most effective rates for you


    When it involves mortgages there’s no “one measurement suits all” coverage. The greatest offers are sometimes based mostly on quite a lot of your private circumstances, similar to revenue, credit score rating, and financial savings. That’s why sitting down with a professional, impartial skilled will help you establish the fitting offers.

    Continue to a dealer


    What is the most effective charge for remortgage debtors?

    Below are a few of the lowest rates for remortgage debtors, right as of seven June 2024.   

    Rate: 4.82% Fixed for 2 years
    APRC: 7.1%
    Upfront charges: £999
    Max LTV: 60%

    Additional notes: This mortgage comes with £250 cashback

    Representative instance:  A reimbursement mortgage of £250,000 payable over 25 years, on a set charge of 4.82% for two years and 4 months, after which on a variable charge of seven.50% for the remaining 22 years and eight months. You can be required to make 28 funds of £1,435.38 and 272 funds of £1,816.38. The complete quantity payable can be £534,995.92 made up of the mortgage quantity plus curiosity (£283,996.92) and charges (£999). The general price for comparability is 7.1% consultant.

    Rate: 4.99% Discounted for two years
    APRC: 7.8%
    Upfront charges: £20
    Max LTV: 80%

    Additional notes: This mortgage comes with no incentives.

    Representative instance: A reimbursement mortgage of £250,000 payable over 25 years, on a reduced charge of 4.99% for two years, after which on a variable charge of 8.24% for the remaining 23 years. You can be required to make 24 funds of £1,460.02 and 276 funds of £1,936.96. The complete quantity payable can be £569,660.19 made up of the mortgage quantity plus curiosity (£319,640.19) and charges (£20). The general price for comparability is 7.8% consultant.

    Rate: 4.42% Fixed for 5 years
    APRC: 7.3%
    Upfront charges: £1,034
    Max LTV: 60%

    Additional notes: This mortgage comes with £350 cashback or free authorized charges

    Representative instance: A reimbursement mortgage of £250,000 payable over 25 years, on a set charge of 4.42% for five years and 5 months, after which on a variable charge of seven.50% for the remaining 19 years and seven months. You can be required to make 65 funds of £1,378.25 and 235 funds of £1,760.01. The complete quantity payable can be £503,937.33 made up of the mortgage quantity plus curiosity (£252,938.33) and charges (£999). The general price for comparability is 6.4% consultant.

    Rate: 5.64% Discounted for five years
    APRC: 7.5%
    Upfront charges: £1,255
    Max LTV: 75%

    Additional notes: This mortgage comes with free authorized charges

    Representative Example: A reimbursement mortgage of £250,000 payable over 25 years, on a reduced charge of 5.64% for five years, after which on a variable charge of 8.39% for the remaining 20 years. You can be required to make 60 funds of £1,556.19 and 240 funds of £1,925.34. The complete quantity payable can be £556,706.84 made up of the mortgage quantity plus curiosity (£305,451.84) and charges (£1,255). The general price for comparability is 7.6% consultant.

    What is the most effective charge for transferring residence?

    Below are a few of the lowest rates for residence movers, right as of 6 June 2024.

    Rate: 4.80% Fixed for 2 years
    APRC: 7.1%
    Upfront charges: £999
    Max LTV: 65%

    Additional notes: This mortgage comes with no incentives

    Representative instance: A reimbursement mortgage of £160,000 payable over 25 years, on a set charge of 4.79% for two years and three months, after which on a variable charge of 6.74% for the remaining 22 years and 9 months. You can be required to make 27 funds of £915.87 and 273 funds of £1,090.79. The complete quantity payable can be £323,513.13 made up of the mortgage quantity plus curiosity (£162,514.13) and charges (£999). The general price for comparability is 6.5% consultant.

    Rate: 4.99% Fixed for two years
    APRC: 7.5%
    Upfront charges: £20
    Max LTV: 80%

    Additional notes: This mortgage comes with no incentives

    Representative instance: A reimbursement mortgage of £160,000 payable over 25 years, on a reduced charge of 4.99% for two years, after which on a variable charge of 8.24% for the remaining 23 years. You can be required to make 24 funds of £934.41 and 276 funds of £1,239.65. The complete quantity payable can be £364,589.72 made up of the mortgage quantity plus curiosity (£204,569.72) and charges (£20). The general price for comparability is 7.8% consultant.

    Rate: 4.28% Fixed for five years
    APRC: 6.4%
    Upfront charges: £999
    Max LTV: 60%

    Additional notes: This mortgage comes with no incentives

    Representative instance: A reimbursement mortgage of £160,000 payable over 25 years, on a set charge of 4.33% for five years and 4 months, after which on a variable charge of 8.74% for the remaining 19 years and eight months. You can be required to make 64 funds of £873.96 and 236 funds of £1,232.42. The complete quantity payable can be £347,519.98 made up of the mortgage quantity plus curiosity (£186,785.98) and charges (£734). The general price for comparability is 7.3% consultant.

    Rate: 5.79% Fixed for five years
    APRC: 7.6%
    Upfront charges: £35
    Max LTV: 60%

    Additional notes: This mortgage comes with no incentives

    Representative instance: A reimbursement mortgage of £160,000 payable over 25 years, on a reduced charge of 5.79% for five years, after which on a variable charge of 8.49% for the remaining 20 years. You can be required to make 60 funds of £1,010.44 and 240 funds of £1,244.01. The complete quantity payable can be £359,224.90 made up of the mortgage quantity plus curiosity (£199,189.90) and charges (£35). The general price for comparability is 7.6% consultant.

    Free Times article: Use your tax-free allowance earlier than the election


    The quantity of tax-free allowance you may get is at its highest since 2010 and persons are dashing to make use of it earlier than the July common election. Learn extra

    How can I get the most effective mortgage charge? 

    While it’s unimaginable to manage all components influencing your mortgage rates, there are steps you may take to boost your odds of touchdown a beneficial deal, in line with Mansi Behl, Lead Mortgage Broker at Koodoo. 

    “Securing the most effective mortgage charge includes a mixture of preparation, analysis, and negotiation,” she stated. 

    Below we’ve listed a few of these measures you may take:  

    Enhance Your Credit Standing

    Lenders throughout the nation will keep in mind your credit score rating when passing you thru their affordability checks. 

    So earlier than this takes place, it could be value reviewing your credit score report for any inaccuracies. In addition, it’s also vital to remain up-to-date along with your invoice funds and to cut back your current money owed the place doable.

    Explore Your Options

    Utilise digital instruments for mortgage charge comparisons and collect charge quotes from numerous lenders, together with conventional banks, constructing societies, and on-line entities.

    An ideal place to start out is by utilizing our mortgage comparability software which you could find under.

    Engage a Mortgage Specialist

    “Brokers can present entry to a wider vary of lenders, typically revealing extra aggressive rates and phrases,” stated Behl. 

    In addition, a great mortgage dealer ought to have a great understanding of the market. So in case you’re uncertain of whether or not you wish to take out a set or variable charge, a dealer may give you personalised recommendation to information you thru your determination. 

    Read extra: Should I take advantage of a mortgage adviser?

    By being proactive about your credit score well being, evaluating properly, and staying up to date, you’ll be well-placed to snag essentially the most beneficial mortgage rates on the market.

    Should I solely take a look at the most effective mortgage rates?

    While charge performs an vital position when taking a look at your mortgage choices, there are different vital components to contemplate. 

    One of those are the charges which might be charged on high of the mortgage. 

    Some of the bottom rates in the marketplace sometimes include increased than common charges, which can make the general price of your mortgage dearer than different choices. 

    Read extra: What are the prices of shopping for a home?

    What else ought to I contemplate when selecting the most effective mortgage charge? 

    In addition to charges, there are different elements of your mortgage deal to contemplate. Below we’ve listed some issues to contemplate:  

    • Overpayments – Overpayments are extra contributions you may make in direction of your mortgage to cut back the curiosity you owe. Most lenders mean you can overpay as much as 10% of your mortgage earlier than charging you a penalty payment. However, this isn’t all the time the case, so if you want this selection you will need to examine your lender’s phrases and situations. 
    • Early reimbursement cost – If your lender does mean you can overpay in your mortgage, then it would cost you an early reimbursement cost. Otherwise generally known as a redemption or exit payment, this may doubtless come within the type of a share of your mortgage worth.  
    • Incentives – Some lenders supply incentives to entice new clients and scale back the price of their mortgage. These sometimes take the type of cashback or a complimentary service, like a free valuation. 

    Are mortgage rates happening?

    Generation Home ended 2023 with a sub 4% mortgage, with a number of different suppliers hovering simply above this threshold.

    In the primary month of the yr quite a lot of suppliers minimize their rates and, as illustrated above, some high-street banks now supply rates under this determine. Whether or not these rates fall additional will depend upon how the market expects curiosity rates to fluctuate. 

    There isn’t any method of realizing for sure what is going to occur, however it’s unlikely that the Bank of England will make any reductions till inflation is below management. 

    Read extra: Will UK mortgage rates go down in 2023?

    Should I contemplate a set or variable charge?

    One of the primary advantages of a set mortgage deal is that it gives a level of certainty. If you’re taking out a set deal today and the Bank of England is compelled to proceed growing curiosity rates, then you definately’ll be protected from these rises over your time period. 

    However, the other can be true. If the Bank of England feels the necessity to decrease its base charge then you can find yourself paying a dearer mortgage. 

    Read extra: Should I get a long-term fastened charge mortgage?

    This is the place a variable deal has its advantages. A tracker mortgage, for instance, will mimic the actions of the Bank of England’s base charge. So if curiosity rates start to fall so will your month-to-month repayments. 

    Important data

    Some of the merchandise promoted are from our affiliate companions from whom we obtain compensation. While we intention to function a few of the greatest merchandise out there, we can’t assessment each product in the marketplace.

  • FCA strategies to make United kingdom ‘the best location to do business in the world’   – Home finance loan Method

    The head of the Economical Carry out Authority mentioned it is “working tough to make the United kingdom the splendid location in the earth to do business enterprise.”  

    Main govt Nikhil Rathi included: “We actually do not simply make the rules, we assist situation the ecosystem and really long-time interval chance starvation that firms function with.”  

    The head of the Metropolis regulator laid out the agenda of the watchdog in extra of the remainder of the yr and past at the once-a-year conference of the Affiliation of Company Treasurers yesterday.  

    Nevertheless, his speech comes as the watchdog has locked horns with the Town and the Chancellor greater than its proposals to ‘identify and disgrace’ firms lower than investigation.    

    Very final 7 days, the total physique promised to “have interaction additional extra with business” greater than the technique, which it thinks is in the public want.  

    On the different hand, earlier than this month 16 City groups reported the plan may hit the valuations of corporations and “destabilise financial markets”. Jeremey Hunt urged the regulator to “re-look” at its proposals.        

    In a broad-ranging speech previous evening, Rathi said the FCA would “at all times purchase a realistic strategy”.  

    Last 12 months ministers gave the physique a secondary aim to assist enhance United kingdom growth and elevate the intercontinental competitiveness of the British financial system over the medium to prolonged-time interval.  

    To that cease, the FCA head mentioned the physique was trying at benchmarks for crypto, AI and different areas.  

    Also, he included that internet lending from non-banking establishments has jumped by throughout £425bn over the earlier 15 yrs.  

    Rathi identified: “Much of the progress has taken place whereas fascination prices have been minimal. Therefore, vulnerabilities may be uncovered by the adjustment to higher curiosity costs and the reworking macro-money environment.  

    “For instance, non-public finance valuations have been lower than pressure, and funding and exit routes have develop to be far tougher.   

    “I’ve made clear that the response is just not to attain rapidly for the regulatory cudgel. And I would love to see way more proof forward of we declare we’ve got a systemic state of affairs in the private finance sector.”  

    The regulator reported it is at the moment supporting the Lender of England with its stress testing on banking publicity to private fairness hazard.  

    Rathi additional that the FCA is enterprise its private function on valuation methods in the fund discipline, which is able to embrace “a multi-organization critique analyzing valuation techniques for personal property,” that will function till the conclusion of the calendar 12 months. 

  • The very best information house report ever

    Sometimes preserving components easy tends to make the idea further crystal clear. I’ve been constant in my stance that all through the a very long time 2008 to 2019, we had the weakest housing restoration at any time. I said that housing begins off would on no account begin a calendar yr at 1.5 million till lastly we achieved the yrs 2020-2024. Only then would we see greater than sufficient demand from the brand new house income present market to warrant that a lot building.

    This hasn’t transpired however, however the present hew house product gross sales report implies we’re

     getting there.

    The Census Bureau studies: “New Property Sales Product gross sales of latest one-household residences in October 2020 have been being at a seasonally adjusted once-a-year fee of 999,000, in line with estimates unveiled collectively now by the U.S. Census Bureau and the Department of Housing and Urban Advancement. This is .3% (±13.6%)* down under the revised September degree of 1,002,000, however is 41.5% (±22.6%) earlier talked about the Oct 2019 estimate of 706,000.” 

    Along with the event in new property income, the common month-to-month present for brand new households has declined radically. This details line has normally been my most significant housing chart to abide by, and it has on no account appeared much better.

    All over once more from the Census report: “The seasonally modified estimate of latest residences on the market on the conclude of Oct was 278,000. This signifies a present of three.3 months on the present-day income charge.” 

    Why is builder self-assurance at an all-time? Anything down under 4.3 months of provide implies that builders can have the utmost self-confidence to create. Larger levels of Stock within the number of 4.4 to six.4 months reveal gradual and regular growth for housing begins, like what we noticed from within the earlier development.

    If stock breaks over 6.5 months, then the business has challenges, and builders will in all probability stall on growth. This occurred in 2018 when mortgage charges reached 4.75% to five%. I then put the housing business within the penalty field proper up till the supply obtained beneath 6.5 months. I warned again then to not imagine that the housing present market peaked, as much better conditions had been simply concerning the nook after we would happen into the best housing demographic patch at any time by the a very long time 2020 to 2024.

    We spent 2019 having rid of the excess housing supply to shut the 12 months flat in housing begins. Now, new house revenue are 41.5% yr about calendar yr and 20.6% calendar yr to this point.

    With all this hoopla, proceed to maintain in mind that this data will affordable. Also, by no means ever neglect about this sector of our monetary system is fairly delicate to increased house mortgage premiums, so if the financial local weather will get higher, it would impression the brand new family product sales market

     all housing particulars moderates to a further typical demand growth and the brand new dwelling product gross sales specifically

    The housing present market about time shouldn’t be like rest room paper revenue. It doesn’t go parabolic in the midst of a hoarding session. Month-to-month provide quantity tendencies are way more helpful than anyone report to gauge the brand new dwelling income market’s power, and it seems fantastic now because the 3-month present sample is at the moment at 3.33 months.

    Not like March and April, order software program details is maintaining extraordinarily very effectively, even with the rise in conditions. I talked about this lately on HousingWire. Today’s report from the MBA confirmed a 19% enhance in acquire applications yr greater than yr — down from final week’s increase of 26% yr round 12 months. This would be the twenty seventh straight week of calendar year-more than-12 months growth.

    Some have been anxious that the brand new monumental spike in COVID-19 circumstances would dampen want prefer it did in March and April, however we’re in a much better monetary spot now than we had been again then. We additionally now think about that Individuals who bought households at some point of the more serious months of the pandemic didn’t have any opposition and had been not outbid.


    The total housing sector has modified as a result of that point interval. Although the progress degree can neat down throughout this interval working with the spike in Covid19 eventualities, it gained’t be like what we seen beforehand within the calendar yr.