Tag: banking

  • Electronic banking on the increase

    Electronic banking on the rise | Australian Broker News

    News

    Digital banking on the increase

    Digital banking interactions surge in 2024

    Digital banking on the rise

    Australians are main a digital revolution, embracing technological progress in banking at unparalleled expenses, in accordance with a brand new report commissioned by the Australian Banking Affiliation (ABA) and equipped by Accenture.

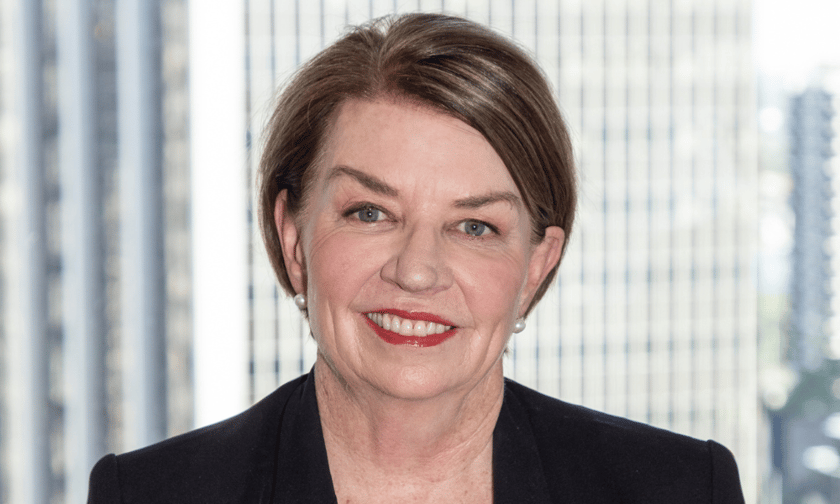
    “Customers are persevering with to shift to handy digital banking channels,” ABA CEO Anna Bligh (pictured earlier talked about) said.

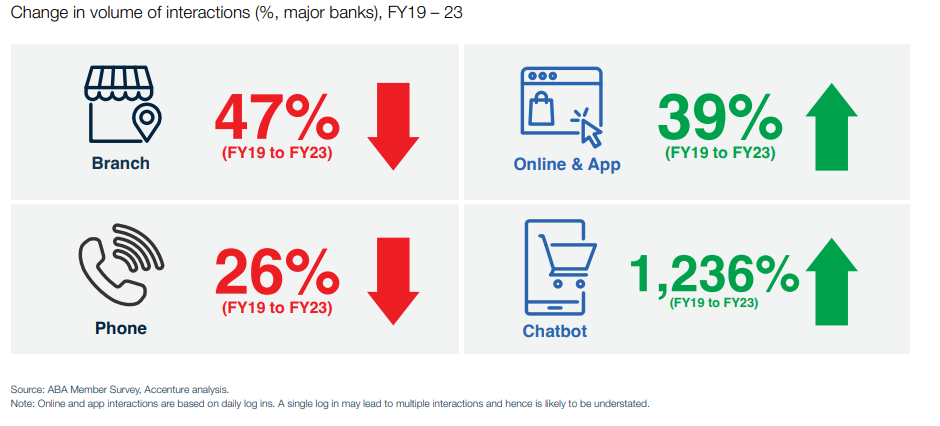
    In between 2019 and 2023, banking interactions grew by 37%, pushed by increasing on the web and utility use.

    Rise of digital funds

    Electronic funds have surged, with principal financial institution prospects constructing $126 billion in funds by way of mobile wallets in the final 12 months—a 35% improve from the earlier 12 months.

    For the initially time, mobile pockets funds have overtaken general ATM cash withdrawals.

    “The booming digital financial system presents quite a few prospects, however it doesn’t happen with out the want of threats,” Bligh claimed.

    Advancement in digital interactions

    Digital banking interactions now account for in extra of 99% of all buyer interactions, with a 37% development on condition that 2019.

    “Australians are interacting with banking establishments much more than at any time forward of,” Bligh mentioned.

    Addressing hazards and ripoffs

    Banks are proactively preserving prospects from cons by interventions comparable to the National Anti-Scam Centre and steps to limit transactions to substantial-chance cryptocurrency exchanges.

    Month-to-month rip-off losses are trending downwards, demonstrating the success of those steps.

    “The digital revolution has enhanced choices for ripoffs, however govt and monetary establishment interventions have noticed a reversal of the upwards growth,” Bligh talked about.

    Economic resilience and enterprise lending

    Irrespective of elevated curiosity costs, Australia’s financial system exhibits resilience.

    Overall skilled lending grew by 6.5% amongst April 2023 and 2024, with smaller and medium companies accounting for 50 % of the full small enterprise lending.

    Lending to the development area consists of 33% of enterprise lending.

    Addressing financial commitments

    Even with greater house finance mortgage repayments, further than 98% of mortgage mortgage holders maintain on to spend on time. Nonetheless, 1 in 20 properties report problems convention payments.

    “Banks proceed to be alert as some women and men find it troublesome to take care of up with their monetary commitments,” Bligh said.

    Supporting buyers in hardship

    Most Australians deal with to fulfill their charges no matter economical pressures. Nonetheless, monetary establishments are fully able to help these experiencing points, with better hardship help in early 2024.

    “Banks will proceed to speculate the place their customers will want them,” Bligh reported.

    Branch density and alternate choices

    Australia maintains a better department density in comparison with worldwide buddies, with 19 financial institution branches for every 100,000 grownups. For regional buyers, Lender@Post presents above 3,400 encounter-to-confront banking accessibility factors.

    Consumer Data Proper (CDR) adoption
    &#13
    Even with substantial investments, uptake of the Buyer Knowledge Suitable continues to be decrease, with a lot lower than 1% of shoppers sharing their knowledge.

    “Government and enterprise have designed main investments in CDR,” Bligh claimed.

    Decrease in cash and cheque use
    &#13
    Hard money use has declined considerably, with a ~10% 12 months-on-yr discount as a result of 2007. Cheque utilization has additionally fallen, with a 37% drop in the vary of cheques drawn in the final calendar 12 months.

    “The use of revenue for real transactions is predicted to maintain on to say no,” Bligh reported.

    Get the hottest and freshest house mortgage information shipped superb into your inbox. Subscribe now to our FREE day-to-day publication.

    Related Tales

    Preserve up with the most present information and actions

    Be a part of our mailing checklist, it’s no value!

  • JPMorgan sees financial investment banking costs up, loans flat in 2nd quarter

    JPMorgan Chase launched their 2nd-quarter earnings remaining outcomes Friday.

    Jeenah Moon/Bloomberg

    This is a buying story. Make certain you take a look at again once more beneath for updates.

    JPMorganChase noticed a 25% soar in features in the second quarter, pushed by an $8 billion windfall from cashing in on Visa shares this spring.

    The $4.1 trillion-asset financial institution’s earnings uncovered how financial uncertainty continued to put stress on sure traces of group this quarter. Excluding the Visa transaction, JPMorgan seen features of $13.1 billion, marking a slight drop from the previous quarter. Profits beat analyst estimates, boosted by a 50% soar in financial investment banking costs, however loans and deposits remained flat.

    JPMorgan famous earnings per share of $4.40, beating analyst forecasts of $4.20.

    Chairman and CEO Jamie Dimon defined in a prepared assertion that inflation and curiosity charges would possibly “maintain bigger than {the marketplace} expects,” however reiterated self-confidence in the financial institution’s signature fortress stability sheet.

    “Even although trade valuations and credit standing spreads seem to replicate a moderately benign financial outlook, we stock on to be vigilant about probably tail challenges,” Dimon said.

    CFO Jeremy Barnum further on a join with with reporters Friday early morning that the elevated tail hazards impacting the financial institution’s outlook, these sorts of as geopolitical difficulties and financial uncertainty, have not shifted.

    Higher-for-for an extended interval fascination premiums proceed on to tamp down on financial institution mortgage progress and deposit expenditures, however JPMorgan has been able to make up income by prices from expense banking merchandise and options and set money circulation and equity marketplaces revenue.

    The financial institution’s shares opened further than 2% down from the prior working day.

    Nonetheless, JPMorgan’s Friday report was primarily unsurprising.

    Expenditures had been being in line with estimates at $23.7 billion, up 14% from the earlier 12 months, which embody a $1 billion contribution to the corporate’s foundation for charitable wants.

    JPMorgan amplified provisions for credit standing losses to $3.1 billion, up from $1.9 billion the prior quarter, as credit standing card losses mounted for every former predictions. Barnum defined the rise in card demand-offs represented a “normalization comparatively than deterioration.” He further that the lender is constructive on the state of the patron.

    Edward Jones analyst James Shanahan wrote in a notice Friday early morning that JPMorgan’s numerous strains of enterprise enterprise placement the lender very nicely to “contend all around the financial cycle.”

  • House loan complaints tumble as banking promises surge: FOS – Property finance loan System

    Issues to the Economical Ombudsman Service about mortgages had been being down by 6% from 8,421 to 7,802 across the calendar 12 months to April in comparison with the previous yr.

    On the opposite hand, enquiries about mortgages, along with people who didn’t progress to a scenario remaining opened, had been being up by 5% above the exact same timeframe, from 9,540 to 10,043.

    It arrives as usually issues concerning the banking sector hit a 10-calendar 12 months substantial, up by 29% from 61,995 final 12 months to 80,137 for 2023/24.

    Inside of the house finance loan sector, the vary of latest grievances fell for many services or products varieties, which incorporates family and subsequent cost loans with a slight enhance in situations about acquire-to-let and fairness launch.

    The share of residence finance loan circumstances that had been upheld in favour of the buyer was 28%, unchanged from final 12 months.

    This compares to an uphold quantity of 37% throughout all varieties of cash product.

    Present-day accounts ended up essentially the most complained about merchandise, adopted by credit standing playing cards, automotive finance and automotive insurance coverage coverage.

    Throughout every kind, elevating quantities of issues are being launched by promises administration suppliers (CMCs), accounting for 1 / 4 of all situations in 2023/24 compared to 18% within the prior monetary 12 months.

    FOS states it has considered glorious and poor observe from statements corporations:

    It states: “Some associates put up mass statements with out the necessity of determining irrespective of whether or not they have benefit, though some others fall brief to reply to requests for proof slowing down our investigations.

    “When issues are upheld, skilled associates can contemplate a considerable proportion of redress awarded to their shoppers.”

    Beneath new proposals made to reduce spurious mass promises, companies might be billed as much as £250 to convey a situation, minimized to £75 if the grievance is upheld in favour of the purchaser.

    Deputy chief ombudsman James Dipple-Johnstone states: “While [claims firms] have a vital position to play in resolving fiscal disputes, they will additionally acquire financially from our firm with no contributing to the working costs. 

    “There is every so often minor proof of owing diligence by some associates to ensure promises they progress have benefit.

    “We are dedicated to creating constructive our help is as obtainable as potential, whereas guaranteeing it stays freed from cost for all shoppers and that individuals with upheld issues can proceed to maintain all of any reward we make.

    “Our proposed charges purpose to verify we handle the fees linked with resolving disputes when reflecting a fairer allocation of all these charges.”

  • Revolut labels home loans ‘core banking function’ – Property finance loan Finance Gazette

    Revolut has particular home loans as a “core banking function” in its “product roadmap,” because it swung to a whole-calendar yr earnings.

    mortgage-application-search-online-digital-620x330.jpg

    The Uk-based digital financial institution, which has 45 million buyers in 38 worldwide places, posted a £438m earnings in 2023, adhering to a £25m loss a yr again, in response to its latest yearly report.

    It claims revenue was boosted by greater fascination costs and the addition of 12 million retail shoppers across the final 12 months. Revenues jumped 95% to £1.8bn about the same interval.

    The fintech firm provides: “There are a assortment of different core banking traits in our merchandise roadmap resembling mortgages and refinancing loans.”

    It factors out: “As we broaden our lending information, in particular person probably providing family home loans, the materiality of our native local weather hazard publicity might nicely alter.”

    It provides that its “monetary making ready system, which delivers forecasts for the next 5 a few years, will help us perceive when our native climate likelihood publicity may turn into substance and once we would additional extra increase our threat administration capabilities”.

    However, regardless of functioning as a licensed monetary establishment in 30 nations, the enterprise doesn’t have a British isles banking license, even though it 1st utilized for only one in 2021.

    The firm has confronted fairly a number of accounting and reputational worries in extra of contemporary a few years.

    Revolut, which was valued at $33bn in 2021, talked about in its once-a-year report that it skilled “enhanced” its fiscal controls in strategies predicted of “listed organizations,” hinting at potential concepts for an preliminary normal public providing – plans which have been carefully-viewed by present market observers for a while.

  • Banking data wrap-up: CBA’s new strategy posting strong results

    Banking data wrap-up: CBA’s new strategy posting strong results | Australian Broker News

    News

    Banking data wrap-up: CBA’s new strategy posting strong results

    Introducing Australia’s sixth largest lender

    Banking data wrap-up: CBA's new strategy posting strong results

    Australia’s huge 4 banks are again in bloom, with mortgage books flourishing after considerations over internet curiosity margins and a sluggish interval for some within the latter half of 2023.

    The newest data on Australian authorised deposit-taking establishments (ADIs) launched by the Australian Prudential and Regulation Authority (APRA) additionally revealed Australia’s new sixth largest lender as three contenders battle it out among the many second-tier banks.

    Commonwealth Bank’s change of strategy

    CBA’s whole mortgage e book grew by $2.9 billion between April 30 and May 31, representing a 0.54% improve on its $554.8 billion mortgage e book.

    The main financial institution’s funding e book elevated by $1.3 billion whereas its owner-occupied e book elevated by $1.6 billion.

    This follows a strong begin to the 12 months by Australia’s largest lender, growing its whole books by $9.6 billion because the begin of the 12 months.

    The calendar 12 months’s results have been in stark distinction to CBA’s second half of 2024, the place mortgage lending stagnated and even went on an unprecedented three-month decline.

    CBA’s turnaround comes amidst trade considerations about narrowing internet curiosity margins (NIM) and the price of utilizing third-party channels.

    The financial institution has not too long ago carried out a number of strategic adjustments to its mortgage choices.

    These efforts come after a lower in broker-originated loans for CBA, dropping from 48% to 43% in its half-year results. In comparability, Westpac (65%), NAB (65%), and ANZ (61%) proceed to rely extra closely on brokers.

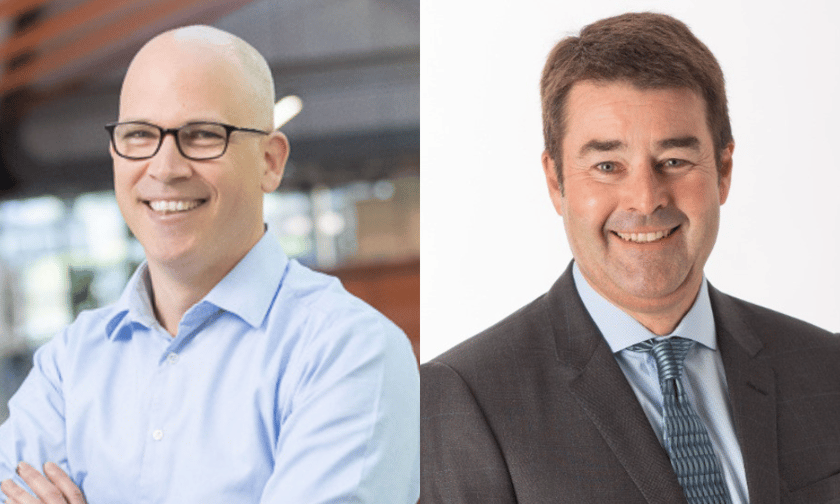
    Dr. Michael Baumann (pictured above left), CBA’s govt common supervisor of dwelling shopping for, reiterated this stance in late May, stating that “as Australia’s largest lender with the very best quantity of broker-originated loans, we stay dedicated to this channel.”

    Mixed fortunes amongst huge 4, ANZ nabs Suncorp

    Among the remainder of the large 4, Westpac continued its strong progress trajectory climbing 0.62% within the month-to-month interval, bringing its whole books as much as $472.48 billion. Year-on-year, Australia’s second-largest financial institution has elevated its books by $26.4 billion (5.84%), essentially the most among the many main lenders.

    Conversely, National Australia Bank (NAB) has struggled to develop its mortgage lending, with it solely growing by $135 million over the month. NAB’s investor books even shrank by $255 million through the interval.

    Despite their variations in current lending numbers, the share worth of each banks has remained unaffected with steady dividends driving up their respective costs because the begin of the 12 months.

    Rounding out the large 4 banks, ANZ additionally skilled a bump to its books in May, growing 0.58% from $296.5 billion to $298.22 billion. This continues a pattern of progress for the financial institution over the previous 12 months.

    For its half, Suncorp Bank’s whole mortgage books, value $53 billion, have stagnated all year long, solely rising by $400 million since January.

    Introducing Australia’s sixth largest lender

    Macquarie Bank, Australia’s fifth largest “maverick” lender, has continued its strong lending results into May, growing by 1.11% from $116.8 billion to $118.1 billion over the month.

    Despite strong performances in its dwelling mortgage and enterprise mortgage portfolios, Macquarie skilled a big drop in earnings in its final full-year results.

    While Macquarie’s annual internet revenue of $3.5 billion was 32% under FY23, the funding financial institution ended the 12 months on a comparatively constructive word, with the second half of the 12 months up 49% on the primary.

    Since these results have been revealed in March, Macquarie Bank’s mortgage books have elevated by $2.5 billion.

    There’s a three-way battle occurring between second-tier banks Bendigo and Adelaide Bank, Bank of Queensland (BoQ), and ING Bank – presently Australia’s sixth, seventh and eighth largest lenders, respectively.

    From a peak of $60.57 billion in February 2023, investor and owner-occupied lending has drifted down by 2.26% to $59.21 billion in May 2024.

    Meanwhile, Bendigo and Adelaide Bank and ING Bank have steadily taken again market share – a lot in order that Bendigo and Adelaide Bank has taken the mantle this month as Australia’s sixth largest lender.

    Bendigo Bank dwelling mortgage clients are essentially the most glad in Australia, based on a current survey that polled greater than 30,000 clients from the ten largest banks.

    The satisfaction of Bendigo Bank clients with their dwelling loans was measured as a market main 87.7% over the six months to March 2024, based on Roy Morgan- exterior website, sustaining its important hole over the common of the main banks.

    Chief buyer officer for client banking at Bendigo Bank, Richard Fennell (pictured above proper), stated he was honoured however not stunned by the consequence given the Bank’s strategy to banking.

    “At Bendigo Bank, we delight ourselves on the relationships we construct with our clients,” Fennell stated.

    “We work laborious to ship nice outcomes for every buyer and have reached out to as lots of our dwelling mortgage clients as attainable during the last two years to ensure their loans have been appropriate for his or her circumstances.

    But whereas Bendigo and Adelaide’s year-on-year results are spectacular – growing 2.89% from $57.9 billion to $59.6 billion – ING Bank is catching up quick, growing 6.05% from $55.7 billion to $59.1 billion.

    Interestingly, Bankwest (86.6%), ING Bank (84.6%), and Macquarie Bank (79.9%) made up the highest 4 within the survey’s buyer satisfaction scores.

    Related Stories

    Keep up with the most recent information and occasions

    Join our mailing listing, it’s free!

  • Lloyds Banking Team appoints Dean as head of housing and sustainability   – Mortgage loan Finance Gazette

    Lloyds Banking Team has appointed Andy Dean as its new head of housing & sustainability.   

    Andy-Dean-crop-620x330.jpg

    Dean joins from Nationwide Making Modern society, the place by he’s presently head of intermediary help & new assemble for the mutual and its acquire-to-permit arm, The Mortgage loan Performs.  

    He has been accountable for main the society’s new-create agenda as a result of 2018, as successfully as main its dealer assist teams, which features a huge group of small enterprise development managers.  

    Dean has labored for 16 yrs on the mutual, from 2008, in a assortment of roles these as an organization growth supervisor and a key account supervisor.  

    Prior to that, he labored as a small enterprise development supervisor at Edge Residence Loans for 2 a few years commencing in 2006.  

    Dean select up his publish on the monetary establishment in September and will report proper to its dealing with director, intermediaries Esther Dijkstra.  

    His appointment follows the retirement of Andy Mason in April, who nonetheless left the monetary establishment quickly after 30 many years. 

    Dijkstra claims: “The intermediary residence loan business is of crucial significance to us, incorporating Andy’s encounter and deep sector know-how to our employees will assist us go on to journey developments and initiatives that stick with it to reinforce our help prospects, brokers and the home loan market.”  

    Dean has additionally served on the Middleman Mortgage Creditors Association’s administration committee for the previous 4 many years.   

  • Senate Banking Committee sets day for FDIC nomination listening to

    Sherrod Brown Jon Tester Senator Jon Tester, D-Mont., talks to Senate Banking Committee chair Sherrod Brown, D-Ohio, in 2022. The Senate Banking Committee has scheduled a affirmation listening to for Christy Goldsmith Romero — now serving as a member of the Commodity Futures Buying and promoting Commission — to chair the Federal Deposit Insurance Corp., however her best affirmation will rely on unified assist from common Democrats like Tester and progressive varieties like Brown.

    Bloomberg News


    WASHINGTON — The Senate Banking Committee will take into account the nomination of Christy Goldsmith Romero to chair the Federal Deposit Insurance protection Corp. on July 11, the panel declared. 

    Goldsmith Romero, who in the mean time sits on the board of the Commodity Futures Trading Commission, was simply currently launched because the Biden administration’s resolve on to direct the FDIC within the wake of a workplace misbehavior scandal on the company. 

    The committee, within the actual listening to, can even take into consideration the nominations of Caroline Crenshaw to be a member of the Securities and Trade Fee, Kristin Johnson to be assistant secretary of financial establishments on the Treasury Division and Gordon Ito to be a member of the Money Steadiness Oversight Council with skills in protection. 

    The Senate Banking Committee listening to marks the primary formal transfer within the course of to confirming Goldsmith Romero’s nomination — a race in opposition to the clock at this level with a restricted variety of legislative days left in Congress. Goldsmith Romero would swap present-day FDIC Chairman Martin Gruenberg, who launched he would resign on the affirmation of a successor. 

    Should the nominations cross the Senate Banking Committee, they are going to go to the whole Senate.


    Though Goldsmith Romero hasn’t activated any pushback a lot from Republicans, the affirmation of her nomination is proceed to significantly from confirmed. 

    Democrats have sufficient votes to usher her and the opposite nominations on account of the Senate, however provided that they proceed being united of their assist — together with amid these trying for reelection in prone seats within the 2024 elections. Republicans have been unusually efficient in sinking the nominations of the Biden administration’s cash regulatory nominees within the earlier, pulling Democratic assist, for illustration, from picks like Sarah Bloom Raskin and Saule Omarova. 

    Really ought to she make it by the use of the affirmation process, Goldsmith Romero would inherit an FDIC that not solely is nonetheless reeling from the neighborhood revelation concerning the company’s tradition, however that has a busy regulatory schedule. 

    On Thursday — in what might very very properly be Gruenberg’s ultimate board assembly as chairman —  the corporate finalized a rule bolstering decision choices for huge regional banking firms. Other crucial rulemakings, just like the Basel III endgame proposal, are nonetheless pending. 

    Goldsmith Romero maybe would have solely a restricted vary of months with a Democratic board. Need to Donald Trump purchase the presidential election, Goldsmith Romero wouldn’t essentially have to motion down as chairman, however could be up versus a 3-2 partisan break up that might make governing the company sophisticated.

  • Banking on great relationships with brokers

    Listening and appearing on brokers’ suggestions is significant to the power and success of the non-major financial institution sector.

    Second-tier banks rely closely on the third get together channel to supply a gentle supply of lending for his or her enterprise.

    In a extremely aggressive lending market, brokers are main the cost over the direct to buyer phase. Broker market share is at a document excessive, with the MFAA reporting in April that 71.8% of all new residential residence loans had been written by brokers within the December 2023 quarter.

    Non-major banks have taken a proactive strategy to dealer relationships, working intently with them to help hundreds of consumers as they roll off low fastened charges onto larger variable charges.

    They are additionally constructing new tech platforms and investing in workers to make sure the whole lending course of is environment friendly, quick, straightforward to make use of and meets the wants of brokers and their clients.

    Retention is the important thing and this may be achieved by persistently delivering for brokers and shoppers.

    Non-major financial institution leaders know that progress and success can’t be reached with out the buy-in of brokers and that’s why they’re eager to work with them and acquire their suggestions.

    MPA invited third get together leaders from main non-major banks to hitch its annual trade roundtable at Sydney’s Silks restaurant. Attending the occasion had been Troy Fedder (Suncorp Bank); Paul Herbert (AMP Bank); Johnny Lockwood (BOQ Group) and Ian Rakhit (Bankwest). George Thompson of ING Australia was unable to be there in particular person, however offered his feedback in writing.

    Two brokers additionally attended – Deborah Brincat from Aussie Parramatta and Stephen Michaels of Catalyst Advisers.

    Q. Non-major banks confronted plenty of challenges in 2023, together with rising rates of interest and inflation and the fastened price cliff. How have you ever dealt with these and different challenges, particularly in partnership with brokers?

    Troy Fedder (pictured beneath), appearing govt common supervisor of residence lending at Suncorp Bank, agreed that 2023 offered plenty of challenges for the trade.

    “It additionally had some tailwinds,” Fedder mentioned. “I feel one of many great issues for the dealer trade is, no matter challenges, the dealer mannequin continues to shine.

    “For Suncorp Bank, the phrase partnership is de facto necessary – the truth that as a non-major, you may genuinely companion with the dealer group to take care of our clients.”

    Fedder mentioned in an setting of rising rates of interest “we should always acknowledge that some clients are doing it robust”.

    “I’ve been actually grateful to witness how Suncorp Bank’s relationship with brokers has continued to develop over the previous few years. The quantity of brokers we work with has helped develop our buyer base and allowed us to supply higher outcomes for our clients.”

    Johnny Lockwood (pictured beneath), BOQ Group common supervisor dealer and strategic partnerships, mentioned there had been 13 rate of interest rises since May 2022, with quite a lot of fastened charges maturing, and brokers had helped clients deal with these challenges.

    “A number of clients on the market might not service with different banks, so it’s necessary for us to proceed to honour each buyer relationships and dealer relationships,” Lockwood mentioned.

    This meant having good retention insurance policies and aiding clients to deal with price rises.

    Lockwood mentioned BOQ Group had been proactive in educating clients about what fastened price maturities meant for them.

    “We’ve obtained navigation hubs, we’ve obtained quite a lot of proactive engagement with clients to assist them perceive their choices.”

    The lender additionally reached out to clients susceptible to hardship “to clean the touchdown for them”.

    Lockwood mentioned it was necessary for brokers to know that their clients can be taken care of.

    “I’ve seen during the last six to 12 months that when a dealer asks what are you good at, they need to learn about your retention insurance policies.

    “It’s not about what’s your lowest price after which contemplating one other lender in a number of years’ time. Brokers need to put clients into real, good, and long-lasting relationships.”

    AMP Bank head of middleman distribution and finance, Paul Herbert (pictured beneath), mentioned the strategy it had taken during the last 12 to 18 months had been to focus on educating clients and brokers.

    “Informing them that that is arising, that is what we’re going to do, that is what the speed goes to do,” Herbert.

    “We’ve been actually early with our communications to clients, to provide them as a lot discover as doable to assist put together for the upper rate of interest setting. We labored with brokers and clients, guaranteeing we gave them a aggressive price for that point primarily based on broader competitors.”

    Herbert mentioned plenty of brokers had spoken to AMP Bank about their retention and rollover conversations with clients, explaining precisely what their fortnightly funds can be as soon as fastened price phrases ended.

    “It’s all about being clear and upfront in these direct-to-customer conversations that we’ve supported brokers with. We discovered that had a extremely optimistic influence.”

    It additionally meant brokers might produce other conversations with clients to find out if they’d the suitable mortgage buildings in place.

    “That was a extremely necessary step change that we took to assist clients by that transition,” Herbert mentioned. “Pleasingly, the roll-off of consumers leaving AMP has been fairly low by that transition interval, as has the arrears.”

    While this completely different strategy to buyer dialog required extra work, Herbert mentioned it had been worthwhile.

    George Thompson (pictured beneath), head of mortgages at ING Australia, mentioned the financial uncertainty and rate of interest setting had challenged many Australians.

    He mentioned from an ING and a dealer perspective, they mixed on efforts to assist and reassure clients.

    This included breaking down all the knowledge to elucidate what it meant to the shopper, particularly those that had been going through difficulties, displaying clients how ING might help them and the steps clients might take, and informing them what choices had been obtainable.

    “We began reaching out to fastened price clients final yr, following a well-thought-out course of that concerned pre-emptively speaking to clients about budgeting and different useful instruments,” Thompson mentioned.

    “As the time to a hard and fast price expiry attracts nearer, the workforce makes outbound calls to clients to make sure they’ve all they should make a well-informed resolution. This necessary funding helps clients to be greatest ready.”

    Lockwood mentioned brokers had been receptive to banks being proactive in dealing with fastened price maturities.

    He mentioned up to now these conditions concerned “some churn”, but when there have been extenuating circumstances it meant brokers talked to banks and clients and got here up with different options.

    Catalyst Advisers managing director Stephen Michaels (pictured beneath) mentioned brokers arrange residence loans with the intention of not shifting the mortgage for 5 to 10 years.

    “If a dealer takes a long-term view on their buyer, and we get remunerated by the path to align ourselves with them long run, you need to place them in the suitable product on the proper time,” mentioned Michaels.

    Customers who had taken out residence loans between 2021 and 2023 had been confronted with quickly rising rates of interest, however Michaels discovered that his brokers hadn’t wanted to maneuver shoppers to completely different banks for a greater deal.

    “The banks had been very accommodating to the shopper, whether or not it’s a variable price that’s solely ever elevated as quickly as they signed up, or it’s a hard and fast rate of interest that’s expired. There have been very trustworthy and thought-out efforts to provide that buyer the suitable price on the proper time.”

    Michaels mentioned refinancing inquiries had been excessive however the variety of clients shifting from one financial institution to a different had been beneath regular. This was as a result of the banks had been taking care of the shopper to retain them long run.

    Deborah Brincat (pictured beneath), a franchisee at Aussie Parramatta, mentioned there weren’t many banks that informed her when a buyer was about to return off a hard and fast price.

    “So who’s contacting this buyer?,” Brincat mentioned. “Is the financial institution contacting the shopper? Or am I, because the dealer who will get remunerated for this, contacting the shopper?

    “I dislike when a buyer flicks me an e mail from a financial institution to say my fastened price is coming off – that is the knowledge that brokers want entry to.”

    Brincat mentioned she wished to know when a hard and fast price was expiring properly forward of time, so she might speak to the shopper and have some leeway if issues arose.

    “I feel the communication piece round fastened price is fascinating, as a result of as a dealer, I really feel prefer it’s my duty to be in entrance of my buyer and saying your fastened price is coming off, let’s have that dialog. Are you snug? Are you okay? This is the speed that they’ve supplied.

    “However, it’s troublesome to have that dialog if the revert price just isn’t offered to us.”

    Responding to Brincat’s feedback, Ian Rakhit (pictured beneath), common supervisor third get together banking at Bankwest, mentioned the financial institution had responded in numerous methods.

    “The first was how can we give the dealer all of the instruments that they should have the dialog? The visibility within the portal of your clients, the charges that they’ll transfer to, key dates like fastened charges, and so on.

    “I feel it makes business sense for us to provide you that info, in addition to relationship-wise. You’re the purpose of contact for the shopper. We shouldn’t have to pay you path and do your communication to clients, we should always respect your relationship.”

    Bankwest had additionally decided which cohort of consumers was most in danger, primarily based on serviceability on the time of software and factoring in a number of price rises.

    Rakhit mentioned the financial institution notified brokers that these clients weren’t but in problem however they could need to ask them in the event that they had been OK.

    “That’s a greater dialog coming from you [the broker] than coming from the financial institution.”

    Bankwest had additionally checked out dealer welfare, as a result of brokers had excessive work ranges by the rate of interest cycle and had been dealing with burdened clients. The financial institution had allowed brokers to entry its high-quality inside worker help program by CommBank, acknowledging that 2023 had been a troublesome yr for brokers.

    Looking on the broader market, Fedder mentioned there have been a number of different dynamics at play.

    “Home mortgage system progress got here down in 2023 – the whole was near 4%. In the previous, it’s been larger. To see that and to nonetheless see dealer companies maintain up signifies the expansion that brokers proceed to get pleasure from.

    “Part of the profit is that a few of these brokers have moved in direction of non-majors, rising our circulate.”

    Fedder mentioned he believed residence mortgage system progress would slowly enhance this yr, thereby additional boosting dealer market share.

    Q: How did non-major banks defend market share within the face of a extremely aggressive market? How necessary is the dealer channel to what you are promoting?

    Herbert mentioned market share was fascinating, however “not at all times the principle sport”.

    He mentioned banks wanted to proceed to attain the suitable margin between the price of elevating capital and lending.

    “If you don’t have worthwhile and profitable banks, it impacts stability and confidence within the banking system.”

    Last yr, AMP Bank made some deliberate modifications about the way it priced for brand spanking new and current clients to get the steadiness proper in managing margins.

    “To hear, study and act on the suggestions from brokers has at all times been a central tenant to the experiences we ship,” mentioned Herbert.

    “In 2023, we knew the necessity to proceed to carry service expertise was necessary, supporting brokers as they navigated a difficult yr for his or her clients.”

    The financial institution spent extra time working with key brokers to streamline the lending course of and help them and their clients to avoid wasting effort and time.

    “At the beginning of 2023, we determined to actually improve dealer expertise and increase the variety of folks supporting brokers.”

    Instead of getting a devoted contact centre, AMP Bank had dealer expertise workers hooked up to BDMs, responding to dealer’s emails and answering the cellphone and build up that “repetitive information and relationship”.

    “We discover that our dealer expertise workforce get as many situations as our BDMs do, as a result of they’re accessible and have been in a position to assist clear up an issue or enhance an expertise for a dealer or a buyer.”

    “Maintaining dealer flows in our enterprise is de facto necessary – greater than 90% of our enterprise comes from brokers. We’re a dealer first enterprise. Every time you do a high up for a dealer mortgage, it is perhaps $10,000 or $20,000, the fee continues to maintain rolling by, we don’t intervene or cease that.”

    Herbert mentioned each communication or resolution centered on delivering for brokers.

    “I feel the consistency and repair we delivered in 2023, even with some actually wild fluctuations in quantity, was by no means greater than 4 days to file. That’s the way you protect belief and repute to persistently ship over the long run.”

    Lockwood agreed, saying it was about getting the suitable steadiness between pursuing progress and appropriately delivering “on our dedication to buyer (and workers) expertise, whereas additionally managing a aggressive market dynamic and stakeholder expectations”.

    “Balance might be the important thing time period for lots of non-majors. It’s about being centered as properly – we aren’t a significant, we are able to’t do every little thing.”

    Lockwood mentioned BOQ Group was priced competitively as a second-tier financial institution”.

    “We’re going by fairly a big transformation on platforms… ME Bank [during this period] is the first platform for us in reaching great customer support and dealer service.

    “We nail easy lending. If you’re coming by PAYG, low LVRs, the mortgage’s going to undergo in a number of days. We’re persistently rated by the aggregators as being on the high by way of turnaround instances, expertise and repair.”

    As a multi-brand organisation, the group additionally operates ME Bank, BOQ and Virgin Money.

    While ME Bank centered on easy, low LVR lending, BOQ had expertise in dealing with extra advanced lending, such because the self-employed, building and SME sectors.

    “With confidence we are able to say to our brokers, ‘what kind of lending are you trying to do’ – we’ve obtained some great choices for you,” mentioned Lockwood.

    Rakhit mentioned 90% of Bankwest’s lending now got here by way of brokers, up from 75% about 10 years in the past.

    Bankwest introduced the closure of its WA department community just lately. It closed its east coast community between 2018 and 2022 and was focusing primarily on the dealer sector.

    “We preserved and grew market share by focusing on retention. We couldn’t compete price-wise on new enterprise however we might do it on retention as a result of we don’t have the identical prices of acquisition.”

    Rakhit mentioned Bankwest carried out strongly on retention by the dealer portal it had constructed and by permitting brokers to cost as they performed their buyer opinions.

    He mentioned 2024 can be completely different – the department closures meant the financial institution might value in a different way and compete extra strongly.

    Fedder mentioned Suncorp Bank’s journey had been an thrilling one, and it continued to develop sustainably.

    “We proceed to focus on rising with extra brokers, and brokers which can be aligned to our buyer segments.”

    Suncorp Bank’s strategy was to ask how its worth proposition may very well be aligned below greatest pursuits obligation.

    “How can we place the model in order that Suncorp Bank, for the suitable buyer, elevates in direction of the highest of the menu?” mentioned Fedder.

    Suncorp Bank had moved again in line with the market within the final three years, focusing on three issues.

    The first was Suncorp Bank’s SunLight proposition, which sees decrease danger residence loans authorized inside 48 hours, and sometimes a lot sooner.

    The second issue was competing on value.

    Thirdly and most significantly, mentioned Fedder, was taking friction out of the mortgage course of, particularly between software and mortgage approval. “How can we work on being one of many extra constant lenders available in the market for velocity to approval?”

    Feedback from brokers had been necessary to make sure Suncorp Bank remained aggressive as a non-major. Fedder mentioned the financial institution wished to make sure that when brokers selected Suncorp Bank, they’d get the suitable velocity to approval.

    Rakhit requested the brokers on the roundtable whether or not they had pushed extra enterprise to non-majors within the final 5 years.

    Brincat mentioned this was undoubtedly the case, as she discovered the foremost banks “troublesome within the service that they supply”.

    She mentioned she had solely written one mortgage with one of many main banks within the final two years as a result of the service from the credit score workforce was inconsistent.

    “They [the bank] don’t come again to you in a well timed method, you speak to 1 particular person, they’ll ask for this after which the file went to any individual else,” Brincat mentioned. “There are some challenges when dealing with abroad operations groups. The expertise for me turned irritating as a result of I couldn’t decide to my buyer, as SLAs stored altering.”

    Brincat mentioned for a time frame, a lot of her enterprise had gone to Macquarie Bank as a result of they had been constant and simple to deal with.

    “As their pricing elevated we had to have a look at different choices for our shoppers and you might get the identical degree of service from non-majors akin to Bankwest and ING – so that they got here into play for me.”

    Rakhit mentioned everyone was speaking about lifting their service proposition to brokers, as a result of non-majors didn’t have the identical model influence because the majors.

    “We’ve all centered on our service proposition to permit us to bridge that hole between ourselves and the majors.”

    Michaels mentioned his brokerage had fairly a fair unfold between the massive 4 banks, second-tier banks and non-bank lenders.

    “But if I needed to name out a distinction between the majors and non-major lenders, the BDM assist is miles and miles forward with the non-majors.”

    Michaels mentioned Catalyst Advisors had a great relationship with the foremost financial institution BDMs however the care issue with non-major BDMs actually shone by, acknowledging the great work of Winston Trinh at AMP Bank and Jude Schofield at Bankwest.

    Brincat agreed with Michaels. She mentioned it wasn’t that main financial institution BDMs didn’t care about serving to brokers, it was the shortage of resourcing and incapability to escalate.

    “We actually hero our BDMs and permit them that capacity to win enterprise, defend their repute. I wonder if that’s true for larger organisations,” Rakhit mentioned.

    Michaels mentioned when speaking to referral companions or clients, he informed them brokers had been in management when it got here to assessing clients and making ready the applying, however as soon as it went to the financial institution it was now not of their management.

    “Our closest management inside a financial institution is by way of our BDMs or relationship managers. I genuinely can say that with non-big 4 financial institution NDMs, there’s extra love and a spotlight and care.”

    Thompson mentioned all through 2023 ING elevated its mortgage lending e book above the speed of system progress.

    “We did this by simplifying credit score lending insurance policies, offering clients and brokers with extra choices. We additionally launched new LVR bands for buyers and launched a brand new on-line serviceability calculator that was straightforward to make use of.”

    Q: Broker query from Deborah Brincat: What funding can we count on for brokers to have the ability to have knowledge wealthy details about their shoppers, particularly charges, time period expiry and steadiness? Some lender portals don’t present this info for present and historic shoppers

    Brincat mentioned excluding Bankwest and some others which already offered this info, she had zero visibility when it got here to her shoppers’ present mortgage charges and no capacity to cost some current shoppers.

    She mentioned this lack of understanding was infuriating and affected retention, particularly when doing anniversary calls with clients and having to ask them what their price was.

    The non-major banks’ credit score groups had actually lifted, offering extra consistency and communication, however when it got here to broker-facing groups and managing clients, enchancment was wanted.

    Herbert mentioned he had heard these issues from brokers many instances and AMP Bank’s first precedence was to have the ability to present this info to brokers.

    “You’ve obtained to have a look at your platforms, your software program, the integrations you’ve got with your core banking methods first, and what’s the pathway to get to that? Providing real-time pricing, a real-time view of your buyer portfolio, it must be finished.”

    Herbert mentioned in December 2023, AMP Bank had created a web based reprice kind which simply required brokers to supply their account particulars. Bots might present a response in minutes, which saved brokers time on repricing.

    A retention specialist might additionally get in touch with the dealer to debate the mortgage situation if wanted.

    Referring to Michaels’ earlier remark about brokers controlling the expertise for the shopper up till mortgage submission, Herbert mentioned AMP Bank had been working arduous to take away this concern from brokers and clients by creating the suitable platform and bettering the front-end expertise.

    It wished to evaluate loans utilizing the information brokers had already validated by display scraping and digital IDs and supply certainty to brokers that they’d get a solution primarily based on the knowledge they provided.

    When the dealer portal was accomplished, brokers would be capable of take a look at their software pipeline in actual time, together with notes on the method and any conversations and interactions with clients.

    Herbert mentioned it was necessary that AMP Bank labored collaboratively with brokers to supply info that might assist them with their clients.

    Rakhit mentioned brokers might entry their current clients’ mortgage info within the Bankwest Broker Portal. He mentioned the portal was the results of time, cash and funding.

    Closing its east coast financial institution branches in 2018 had freed up cash for funding in brokers.

    “I feel the most important alternative we’ve as leaders of third get together companies is influencing these conversations about the place do our banks make investments? It’s actually pleasing that we’re investing increasingly more in dealer options,” Rakhit mentioned.

    Lockwood mentioned ME Bank, BOQ and Virgin Money all had dealer portals, together with a dealer pricing software which typically offered an prompt resolution for on-line submissions; in different conditions it may need to be escalated.

    “We recognise the significance of making an attempt that can assist you handle your time. There’s no level you sitting on the cellphone for one thing that may be finished instantly,” he mentioned.

    Lockwood mentioned together with buyer knowledge within the dealer portal would make the method less complicated and BOQ Group was presently working on the safety features. “Stay tuned.”

    Fedder mentioned Suncorp Bank had already constructed its dealer portal, including within the knowledge of all clients from May 2023 onwards. Like different non-majors, the financial institution would take a look at easy methods to greatest pursue the continued retention of consumers.

    “The undeniable fact that brokers see this as an important space the place they add worth to clients implies that we have to proceed to have a look at it,” mentioned Fedder.

    Lockwood mentioned, “It’s less expensive for us to maintain an current buyer than it’s to amass a brand new buyer. We’d love all clients to remain and for all brokers to be completely happy.”

    Q: Broker query from Stephen Michaels. What are your ideas on the massive 4 banks and cases the place they obtain “particular remedy” compared to non-major banks? Example – the flexibility to supply stream­lined refinance evaluation (i.e. 1% buffer on high of precise price). Is this honest? Are non-majors at an obstacle relating to implementing credit score coverage modifications?

    Rakhit mentioned the three% buffer was a requirement set by APRA to assist accountable lending.

    Some main banks supplied streamline loans with decrease ranges of documentation akin to dollar-for-dollar refinances.

    Bankwest had supplied a 1% buffer on dollar-for-dollar refinances, however just for single owner-occupier or one funding property.

    “We wanted to tell APRA that we’d put sure controls in place to make sure that we weren’t taking on enterprise or danger that might be detrimental to our requirements,” Rakhit mentioned.

    Bankwest additionally needed to agree with APRA that it could solely enable a sure variety of these refinances, with the restrict reached in a short time.

    Rakhit mentioned the non-majors ought to take a look at first residence consumers. ‘Mortgage prisoners’ was a standard time period however there have been quite a lot of ‘rental prisoners’ – potential first-time consumers who attributable to massive rents had been unable to avoid wasting sufficient for a deposit.

    “In phrases of serviceability, the first-time consumers are in all probability paying the very best price available in the market and then you definitely put 3% on high. That’s not essentially serving to us deliver extra folks into homeownership.”

    Lockwood mentioned one of many frustrations for non-major banks on 1% buffer loans was that they had been coverage exceptions and sometimes didn’t stack up attributable to scale.

    “When you’ve obtained a lot decrease circulate than a significant and a a lot smaller steadiness sheet, since you may need a really small allocation, then how do you handle that? Is that the type of danger you need?”

    It was an unlevel enjoying subject for the non-majors in comparison with the majors as a result of scale did rely, mentioned Lockwood.

    MPA requested Michaels if he believed the 1% buffer loans had been driving dealer enterprise to the majors.

    Michaels mentioned this was completely the case. He gave an instance of a buyer with three properties in Sydney’s japanese suburbs, totalling $3.5 million in loans within the portfolio.

    “His borrowing capability going to a non 1% buffer financial institution was a most borrowing for the family of $2.2 million,” he mentioned. “It was a $1.3 million distinction in borrowing.”

    Brincat mentioned that it was primarily buyers who had been lacking out on the 1% buffer alternatives, attributable to coverage standards.

    “They’re already getting hamstrung round price. They’ve obtained a number of properties and are clearly in a position to service their debt – what’s the danger? Particularly when LVRs are sub-80%.”

    Rakhit mentioned all non-majors can be happy with the low degree of arrears, given two years of COVID and 13 price rises.

    “Our degree of arrears could be very, very low. Now this may very well be as a result of 3% buffer.”

    Lockwood mentioned this was a great level.

    “The Australian financial system and banking setting might be one of the crucial steady and dependable on the earth – it’s the partnership between banks and the regulators and the commitments that we’ve.”

    Q: What are your plans to improve know-how in 2024 and the way will they enhance methods and processes for brokers and their clients? What half does AI must play?

    Fedder mentioned Suncorp Bank has a strategic partnership with NextGen and they’d proceed to work collectively, investing in velocity from software by to unconditional approval.

    “For me, it’s that constant strategy – the way you get sooner and sooner and take the friction out of the mannequin. We’re reflecting on what we’ve finished up to now and we’re persevering with to ask for dealer suggestions round how we are able to make that even higher.”

    Herbert mentioned velocity was an fascinating level. “You might be quick, however wanting again on the worth chain, how can we scale back effort? Effort for the dealer, effort for the shopper. How can we take away duplication of effort?”

    AMP Bank was eager to enhance brokers’ confidence in a lending consequence.

    “Brokers repeatedly inform us they worth the flexibility to manage and have visibility of the expertise for his or her clients all through the house mortgage journey, nevertheless this typically breaks down as soon as a mortgage is submitted,” Herbert mentioned.

    “Providing higher confidence in outcomes earlier than a mortgage is submitted is a vital step change we see necessary to assist handle this, and delivering a number one software expertise for our brokers and their clients that offers great confidence within the consequence upfront is a precedence.”

    Herbert mentioned there have been quite a lot of instruments together with propensity modelling and AI that would assist. More necessary had been the digital instruments brokers used to supply info that may very well be utilized by the lenders slightly than duplicating the hassle already undertaken.

    Brincat mentioned quite a lot of this got here again to banks working with aggregators which supplied great know-how. She gave the instance of Lendi Group, which was working on an approval confidence characteristic.

    “So because of this we are able to put the information within the system, and as soon as the information is correct, the system will be capable of inform us what’s the chance of that approval occurring. The work being finished with aggregators helps us as brokers, particularly if that may be the one-stop store.”

    Brincat mentioned many brokers additionally used Quickli attributable to its accuracy earlier than going to a lender.

    Michaels mentioned he additionally used Quickli to streamline the method and get to the suitable consequence.

    Rakhit mentioned sooner or later loans may very well be authorized at time of lodgement. This would contain revalidating info brokers offered utilizing knowledge factors as an alternative of paperwork.

    Bankwest was excited to introduce its first AI software, which helped brokers when utilizing the financial institution’s library of credit score coverage.

    “You put in sure search info, and AI will deliver that info to the fore slightly than you having to go and discover it.”

    Rakhit mentioned AI was excellent for repeatable duties and the plan was to increase its use.

    Bankwest had additionally spoken to Quickli, which might present “a tremendous degree of knowledge on opponents, how they value, how they service, what they put into their serviceability catalogue”.

    Rakhit mentioned there have been additionally different great tech firms akin to CoreLogic, illion and Equifax that the trade might put money into and the following few years can be thrilling.

    ING was digitising and automating the shopper journey and evaluation course of to create sooner extra streamlined buyer experiences, Thompson mentioned. “Digital validation of software paperwork is an instance. AI is seen more and more as a core functionality and alternative.”

    Lockwood mentioned 2024 can be a large yr for BOQ Group by way of know-how transformation.

    “One of the biggest investments that the financial institution has made ever is in a brand new residence mortgage program,” he mentioned.

    BOQ group had launched a greenfield digital financial institution a number of years in the past that includes all three manufacturers, Virgin Money, BOQ and ME Bank.

  • Banking on great relationships with brokers

    Listening and appearing on brokers’ suggestions is important to the energy and success of the non-major financial institution sector.

    Second-tier banks rely closely on the third social gathering channel to offer a gentle supply of lending for his or her enterprise.

    In a extremely aggressive lending market, brokers are main the cost over the direct to buyer section. Broker market share is at a document excessive, with the MFAA reporting in April that 71.8% of all new residential dwelling loans had been written by brokers within the December 2023 quarter.
    Non-major banks have taken a proactive strategy to dealer relationships, working intently with them to help 1000’s of consumers as they roll off low fastened charges onto increased variable charges.

    They are additionally constructing new tech platforms and investing in employees to make sure the complete lending course of is environment friendly, quick, simple to make use of and meets the wants of brokers and their clients.

    Retention is the important thing and this may be achieved by constantly delivering for brokers and purchasers.

    Non-major financial institution leaders know that development and success can’t be reached with out the buy-in of brokers and that’s why they’re eager to work with them and achieve their suggestions.

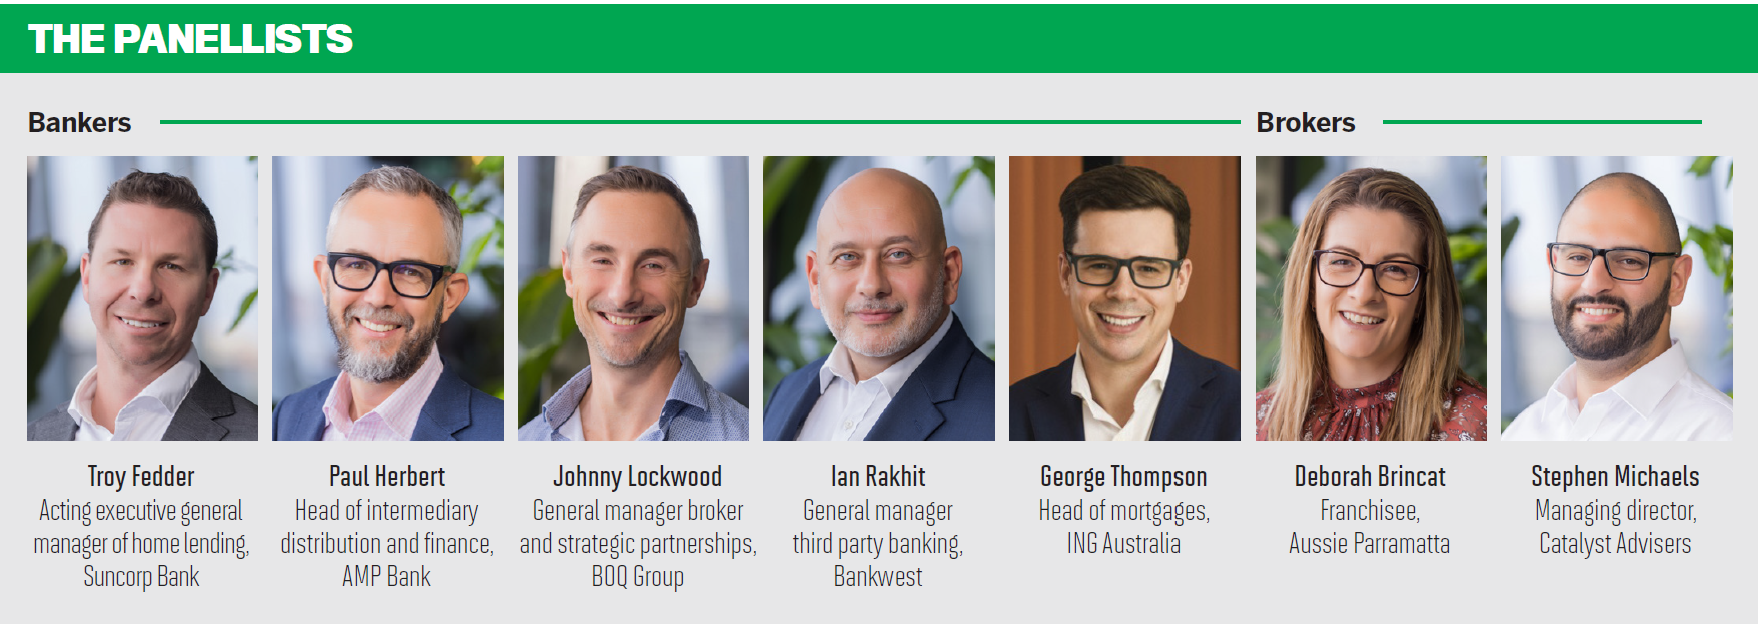
    MPA invited third social gathering leaders from main non-major banks to affix its annual trade roundtable at Sydney’s Silks restaurant. Attending the occasion had been Troy Fedder (Suncorp Bank); Paul Herbert (AMP Bank); Johnny Lockwood (BOQ Group) and Ian Rakhit (Bankwest). George Thompson of ING Australia was unable to be there in individual, however offered his feedback in writing.

    Two brokers additionally attended – Deborah Brincat from Aussie Parramatta and Stephen Michaels of Catalyst Advisers.

    Q. Non-major banks confronted plenty of challenges in 2023, together with rising rates of interest and inflation and the fastened fee cliff. How have you ever dealt with these and different challenges, particularly in partnership with brokers?

    Troy Fedder (pictured beneath), appearing government basic supervisor of dwelling lending at Suncorp Bank, agreed that 2023 introduced plenty of challenges for the trade.
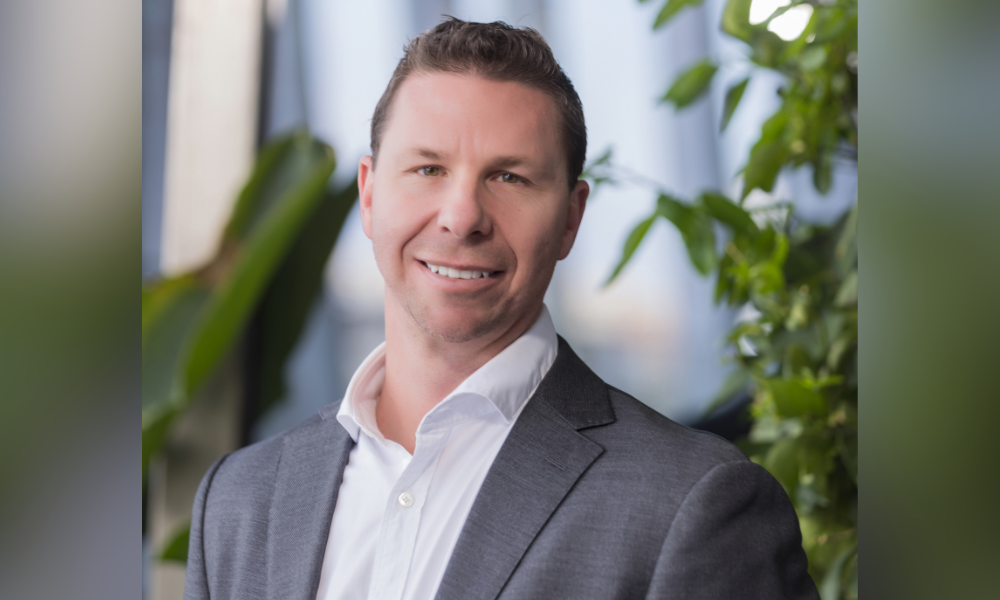
    “It additionally had some tailwinds,” Fedder mentioned. “I believe one of many great issues for the dealer trade is, no matter challenges, the dealer mannequin continues to shine.

    “For Suncorp Bank, the phrase partnership is actually essential – the truth that as a non-major, you possibly can genuinely associate with the dealer neighborhood to take care of our clients.”

    Fedder mentioned in an surroundings of rising rates of interest “we should always acknowledge that some clients are doing it robust”.

    “I’ve been actually grateful to witness how Suncorp Bank’s relationship with brokers has continued to develop over the previous few years. The quantity of brokers we work with has helped develop our buyer base and allowed us to offer higher outcomes for our clients.”

    Johnny Lockwood (pictured beneath), BOQ Group basic supervisor dealer and strategic partnerships, mentioned there had been 13 rate of interest rises since May 2022, with numerous fastened charges maturing, and brokers had helped clients deal with these challenges.
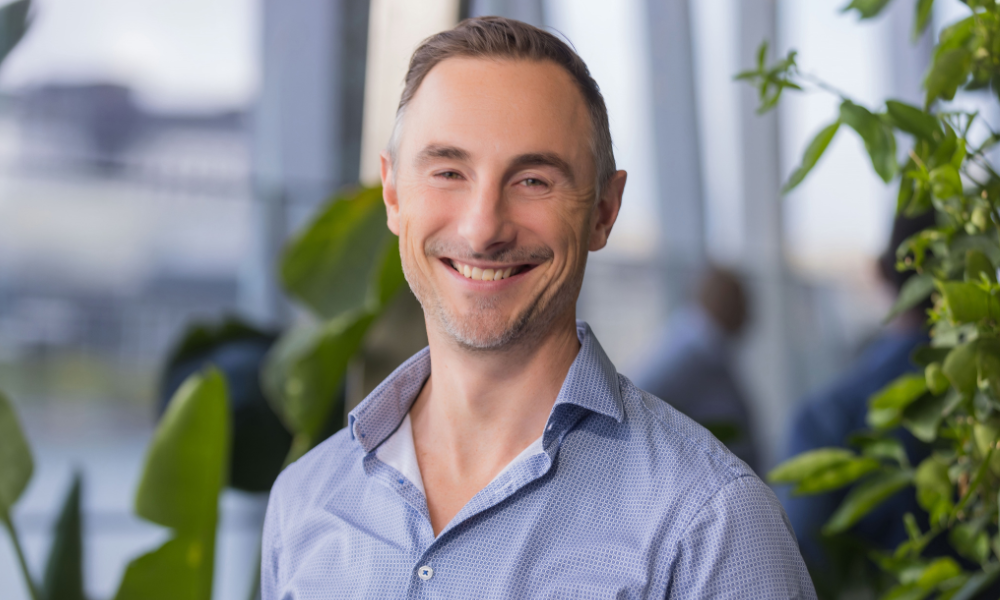
    “Lots of clients on the market could not service with different banks, so it’s essential for us to proceed to honour each buyer relationships and dealer relationships,” Lockwood mentioned.

    This meant having good retention insurance policies and helping clients to deal with fee rises.

    Lockwood mentioned BOQ Group had been proactive in educating clients about what fastened fee maturities meant for them.

    “We’ve acquired navigation hubs, we’ve acquired numerous proactive engagement with clients to assist them perceive their choices.”

    The lender additionally reached out to clients vulnerable to hardship “to easy the touchdown for them”.

    Lockwood mentioned it was essential for brokers to know that their clients can be sorted.

    “I’ve observed over the past six to 12 months that when a dealer asks what are you good at, they need to learn about your retention insurance policies.

    “It’s not about what’s your lowest fee after which contemplating one other lender in a number of years’ time. Brokers need to put clients into real, good, and long-lasting relationships.”

    AMP Bank head of middleman distribution and finance, Paul Herbert (pictured beneath), mentioned the strategy it had taken over the past 12 to 18 months had been to focus on educating clients and brokers.
    “Informing them that that is arising, that is what we’re going to do, that is what the speed goes to do,” Herbert.

    “We’ve been actually early with our communications to clients, to present them as a lot discover as doable to assist put together for the upper rate of interest surroundings. We labored with brokers and clients, guaranteeing we gave them a aggressive fee for that point primarily based on broader competitors.”

    Herbert mentioned plenty of brokers had spoken to AMP Bank about their retention and rollover conversations with clients, explaining precisely what their fortnightly funds can be as soon as fastened fee phrases ended.

    “It’s all about being clear and upfront in these direct-to-customer conversations that we’ve supported brokers with. We discovered that had a extremely optimistic affect.”

    It additionally meant brokers may produce other conversations with clients to find out if that they had the appropriate mortgage buildings in place.

    “That was a extremely essential step change that we took to help clients by means of that transition,” Herbert mentioned. “Pleasingly, the roll-off of consumers leaving AMP has been fairly low by means of that transition interval, as has the arrears.”

    While this completely different strategy to buyer dialog required extra work, Herbert mentioned it had been worthwhile.

    George Thompson (pictured beneath), head of mortgages at ING Australia, mentioned the financial uncertainty and rate of interest surroundings had challenged many Australians.
    He mentioned from an ING and a dealer perspective, they mixed on efforts to help and reassure clients.

    This included breaking down all the knowledge to clarify what it meant to the shopper, particularly those that had been dealing with difficulties, exhibiting clients how ING may help them and the steps clients may take, and informing them what choices had been out there.

    “We began reaching out to fastened fee clients final 12 months, following a well-thought-out course of that concerned pre-emptively speaking to clients about budgeting and different useful instruments,” Thompson mentioned.

    “As the time to a hard and fast fee expiry attracts nearer, the crew makes outbound calls to clients to make sure they’ve all they should make a well-informed resolution. This essential funding helps clients to be greatest ready.”

    Lockwood mentioned brokers had been receptive to banks being proactive in dealing with fastened fee maturities.

    He mentioned up to now these conditions concerned “some churn”, but when there have been extenuating circumstances it meant brokers talked to banks and clients and got here up with different options.

    Catalyst Advisers managing director Stephen Michaels (pictured beneath) mentioned brokers arrange dwelling loans with the purpose of not shifting the mortgage for 5 to 10 years.
    “If a dealer takes a long-term view on their buyer, and we get remunerated by the path to align ourselves with them long run, you need to place them in the appropriate product on the proper time,” mentioned Michaels.

    Customers who had taken out dwelling loans between 2021 and 2023 had been confronted with quickly rising rates of interest, however Michaels discovered that his brokers hadn’t wanted to maneuver purchasers to completely different banks for a greater deal.

    “The banks had been very accommodating to the shopper, whether or not it’s a variable fee that’s solely ever elevated as quickly as they signed up, or it’s a hard and fast rate of interest that’s expired. There have been very sincere and thought-out efforts to present that buyer the appropriate fee on the proper time.”

    Michaels mentioned refinancing inquiries had been excessive however the variety of clients shifting from one financial institution to a different had been beneath regular. This was as a result of the banks had been taking care of the shopper to retain them long run.

    Deborah Brincat (pictured beneath), a franchisee at Aussie Parramatta, mentioned there weren’t many banks that informed her when a buyer was about to return off a hard and fast fee.
    “So who’s contacting this buyer?,” Brincat mentioned. “Is the financial institution contacting the shopper? Or am I, because the dealer who will get remunerated for this, contacting the shopper?

    “I dislike when a buyer flicks me an e mail from a financial institution to say my fastened fee is coming off – that is the knowledge that brokers want entry to.”

    Brincat mentioned she needed to know when a hard and fast fee was expiring nicely forward of time, so she may speak to the shopper and have some leeway if issues arose.

    “I believe the communication piece round fastened fee is attention-grabbing, as a result of as a dealer, I really feel prefer it’s my accountability to be in entrance of my buyer and saying your fastened fee is coming off, let’s have that dialog. Are you snug? Are you okay? This is the speed that they’ve supplied.

    “However, it’s tough to have that dialog if the revert fee just isn’t offered to us.”

    Responding to Brincat’s feedback, Ian Rakhit (pictured beneath), basic supervisor third social gathering banking at Bankwest, mentioned the financial institution had responded in several methods.
    “The first was how will we give the dealer all of the instruments that they should have the dialog? The visibility within the portal of your clients, the charges that they’ll transfer to, key dates like fastened charges, and so on.

    “I believe it makes industrial sense for us to present you that data, in addition to relationship-wise. You’re the purpose of contact for the shopper. We shouldn’t have to pay you path and do your communication to clients, we should always respect your relationship.”

    Bankwest had additionally decided which cohort of consumers was most in danger, primarily based on serviceability on the time of software and factoring in a number of fee rises.

    Rakhit mentioned the financial institution notified brokers that these clients weren’t but in problem however they may need to ask them in the event that they had been OK.

    “That’s a greater dialog coming from you [the broker] than coming from the financial institution.”

    Bankwest had additionally checked out dealer welfare, as a result of brokers had excessive work ranges by means of the rate of interest cycle and had been dealing with burdened clients. The financial institution had allowed brokers to entry its high-quality inside worker help program by means of CommBank, acknowledging that 2023 had been a troublesome 12 months for brokers.

    Looking on the broader market, Fedder mentioned there have been a number of different dynamics at play.

    “Home mortgage system development got here down in 2023 – the entire was near 4%. In the previous, it’s been increased. To see that and to nonetheless see dealer companies maintain up signifies the expansion that brokers proceed to take pleasure in.

    “Part of the profit is that a few of these brokers have moved in direction of non-majors, growing our stream.”

    Fedder mentioned he believed dwelling mortgage system development would slowly enhance this 12 months, thereby additional boosting dealer market share.
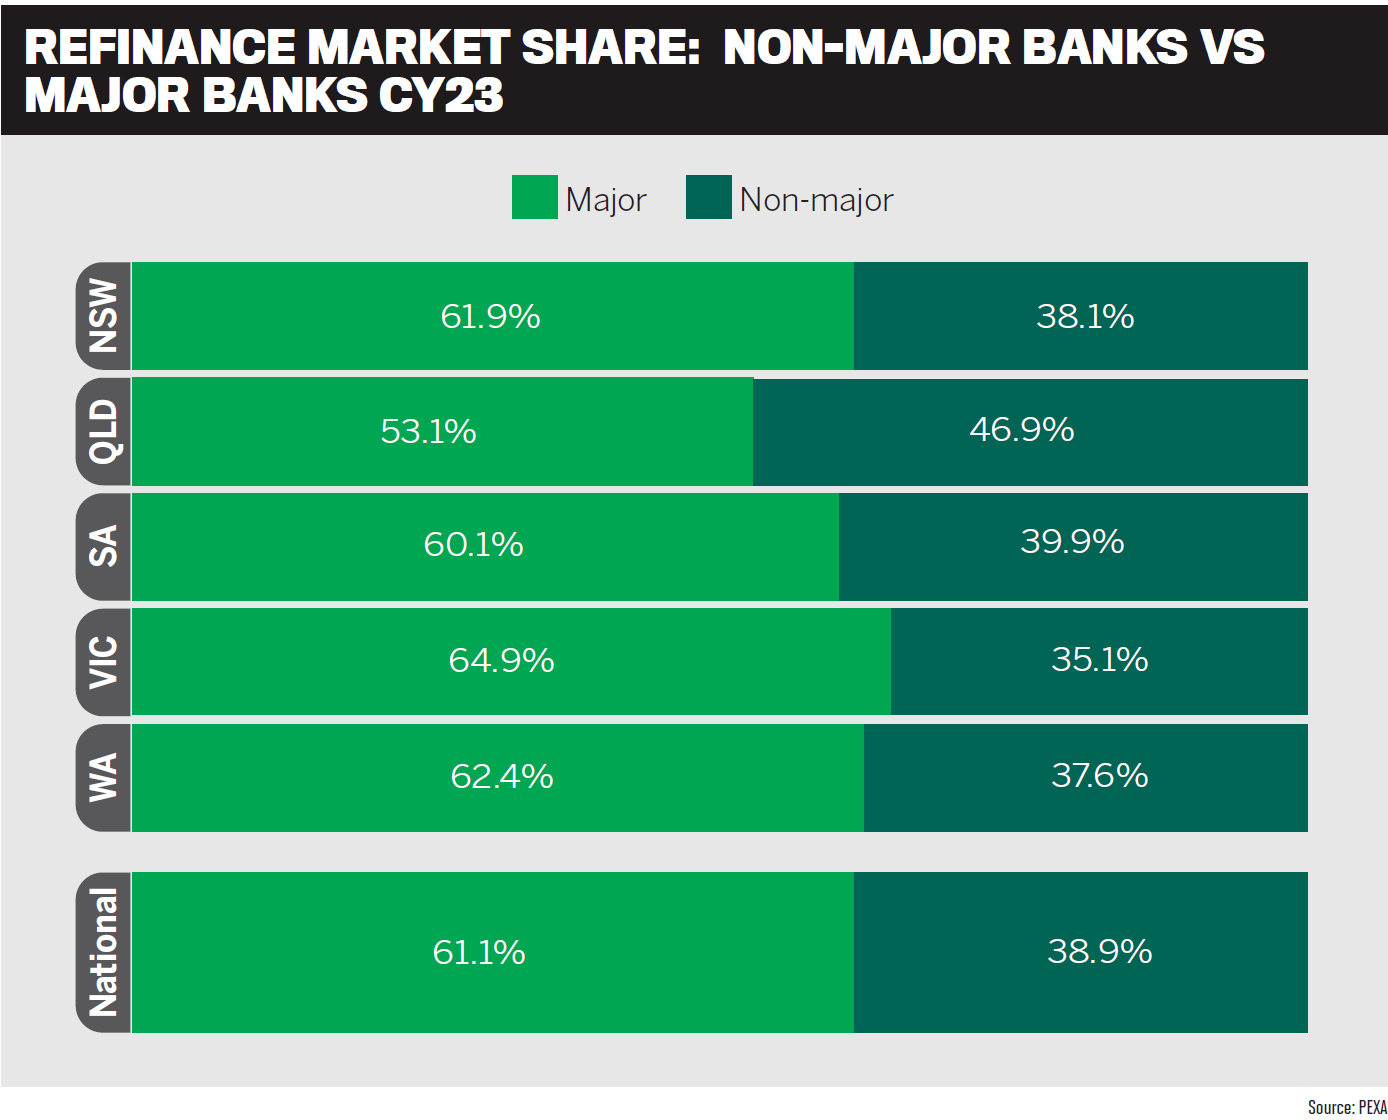
    Q: How did non-major banks defend market share within the face of a extremely aggressive market? How essential is the dealer channel to your enterprise?

    Herbert mentioned market share was attention-grabbing, however “not at all times the primary recreation”.

    He mentioned banks wanted to proceed to realize the appropriate margin between the price of elevating capital and lending.

    “If you don’t have worthwhile and profitable banks, it impacts stability and confidence within the banking system.”

    Last 12 months, AMP Bank made some deliberate modifications about the way it priced for brand spanking new and current clients to get the steadiness proper in managing margins.

    “To pay attention, be taught and act on the suggestions from brokers has at all times been a central tenant to the experiences we ship,” mentioned Herbert.

    “In 2023, we knew the necessity to proceed to carry service expertise was essential, supporting brokers as they navigated a difficult 12 months for his or her clients.”

    The financial institution spent extra time working with key brokers to streamline the lending course of and help them and their clients to avoid wasting effort and time.

    “At the beginning of 2023, we determined to actually improve dealer expertise and increase the variety of individuals supporting brokers.”

    Instead of getting a devoted contact centre, AMP Bank had dealer expertise employees hooked up to BDMs, responding to dealer’s emails and answering the cellphone and build up that “repetitive data and relationship”.

    “We discover that our dealer expertise crew get as many eventualities as our BDMs do, as a result of they’re accessible and have been capable of assist clear up an issue or enhance an expertise for a dealer or a buyer.”

    “Maintaining dealer flows in our enterprise is actually essential – greater than 90% of our enterprise comes from brokers. We’re a dealer first enterprise. Every time you do a prime up for a dealer mortgage, it is likely to be $10,000 or $20,000, the fee continues to maintain rolling by means of, we don’t intervene or cease that.”

    Herbert mentioned each communication or resolution targeted on delivering for brokers.

    “I believe the consistency and repair we delivered in 2023, even with some actually wild fluctuations in quantity, was by no means greater than 4 days to file. That’s the way you protect belief and fame to constantly ship over the long run.”

    Lockwood agreed, saying it was about getting the appropriate steadiness between pursuing development and appropriately delivering “on our dedication to buyer (and employees) expertise, whereas additionally managing a aggressive market dynamic and stakeholder expectations”.

    “Balance might be the important thing time period for lots of non-majors. It’s about being targeted as nicely – we aren’t a significant, we are able to’t do all the pieces.”

    Lockwood mentioned BOQ Group was priced competitively as a second-tier financial institution”.

    “We’re going by means of fairly a big transformation on platforms… ME Bank [during this period] is the first platform for us in reaching great customer support and dealer service.

    “We nail easy lending. If you’re coming by means of PAYG, low LVRs, the mortgage’s going to undergo in a number of days. We’re constantly rated by the aggregators as being on the prime when it comes to turnaround occasions, expertise and repair.”

    As a multi-brand organisation, the group additionally operates ME Bank, BOQ and Virgin Money.

    While ME Bank targeted on easy, low LVR lending, BOQ had expertise in dealing with extra complicated lending, such because the self-employed, building and SME sectors.

    “With confidence we are able to say to our brokers, ‘what kind of lending are you trying to do’ – we’ve acquired some great choices for you,” mentioned Lockwood.

    Rakhit mentioned 90% of Bankwest’s lending now got here through brokers, up from 75% about 10 years in the past.

    Bankwest introduced the closure of its WA department community lately. It closed its east coast community between 2018 and 2022 and was focusing primarily on the dealer sector.

    “We preserved and grew market share by focusing on retention. We couldn’t compete price-wise on new enterprise however we may do it on retention as a result of we don’t have the identical prices of acquisition.”

    Rakhit mentioned Bankwest carried out strongly on retention by means of the dealer portal it had constructed and by permitting brokers to cost as they performed their buyer evaluations.

    He mentioned 2024 can be completely different – the department closures meant the financial institution may worth in another way and compete extra strongly.

    Fedder mentioned Suncorp Bank’s journey had been an thrilling one, and it continued to develop sustainably.

    “We proceed to focus on rising with extra brokers, and brokers which are aligned to our buyer segments.”

    Suncorp Bank’s strategy was to ask how its worth proposition may very well be aligned underneath greatest pursuits obligation.

    “How will we place the model in order that Suncorp Bank, for the appropriate buyer, elevates in direction of the highest of the menu?” mentioned Fedder.

    Suncorp Bank had moved again in line with the market within the final three years, focusing on three issues.

    The first was Suncorp Bank’s SunLight proposition, which sees decrease threat dwelling loans authorized inside 48 hours, and sometimes a lot quicker.

    The second issue was competing on worth.

    Thirdly and most significantly, mentioned Fedder, was taking friction out of the mortgage course of, particularly between software and mortgage approval. “How will we work on being one of many extra constant lenders out there for velocity to approval?”

    Feedback from brokers had been essential to make sure Suncorp Bank remained aggressive as a non-major. Fedder mentioned the financial institution needed to make sure that when brokers selected Suncorp Bank, they’d get the appropriate velocity to approval.

    Rakhit requested the brokers on the roundtable whether or not they had pushed extra enterprise to non-majors within the final 5 years.

    Brincat mentioned this was undoubtedly the case, as she discovered the foremost banks “tough within the service that they supply”.

    She mentioned she had solely written one mortgage with one of many main banks within the final two years as a result of the service from the credit score crew was inconsistent.

    “They [the bank] don’t come again to you in a well timed method, you speak to 1 individual, they’ll ask for this after which the file went to anyone else,” Brincat mentioned. “There are some challenges when dealing with abroad operations groups. The expertise for me grew to become irritating as a result of I couldn’t decide to my buyer, as SLAs saved altering.”

    Brincat mentioned for a time frame, a lot of her enterprise had gone to Macquarie Bank as a result of they had been constant and straightforward to deal with.

    “As their pricing elevated we had to have a look at different choices for our purchasers and you would get the identical stage of service from non-majors comparable to Bankwest and ING – so that they got here into play for me.”

    Rakhit mentioned everyone was speaking about lifting their service proposition to brokers, as a result of non-majors didn’t have the identical model affect because the majors.

    “We’ve all targeted on our service proposition to permit us to bridge that hole between ourselves and the majors.”

    Michaels mentioned his brokerage had fairly a fair unfold between the massive 4 banks, second-tier banks and non-bank lenders.

    “But if I needed to name out a distinction between the majors and non-major lenders, the BDM help is miles and miles forward with the non-majors.”

    Michaels mentioned Catalyst Advisors had relationship with the foremost financial institution BDMs however the care issue with non-major BDMs actually shone by means of, acknowledging the great work of Winston Trinh at AMP Bank and Jude Schofield at Bankwest.

    Brincat agreed with Michaels. She mentioned it wasn’t that main financial institution BDMs didn’t care about serving to brokers, it was the dearth of resourcing and incapacity to escalate.

    “We actually hero our BDMs and permit them that capacity to win enterprise, defend their fame. I wonder if that’s true for greater organisations,” Rakhit mentioned.

    Michaels mentioned when speaking to referral companions or clients, he informed them brokers had been in management when it got here to assessing clients and making ready the appliance, however as soon as it went to the financial institution it was not of their management.

    “Our closest management inside a financial institution is through our BDMs or relationship managers. I genuinely can say that with non-big 4 financial institution NDMs, there’s extra love and a focus and care.”

    Thompson mentioned all through 2023 ING elevated its mortgage lending ebook above the speed of system development.

    “We did this by simplifying credit score lending insurance policies, offering clients and brokers with extra choices. We additionally launched new LVR bands for buyers and launched a brand new on-line serviceability calculator that was simple to make use of.”

    Q: Broker query from Deborah Brincat: What funding can we anticipate for brokers to have the ability to have information wealthy details about their purchasers, particularly charges, time period expiry and steadiness? Some lender portals don’t present this data for present and historic purchasers

    Brincat mentioned excluding Bankwest and some others which already offered this data, she had zero visibility when it got here to her purchasers’ present mortgage charges and no capacity to cost some current purchasers.

    She mentioned this lack of expertise was infuriating and affected retention, particularly when doing anniversary calls with clients and having to ask them what their fee was.

    The non-major banks’ credit score groups had actually lifted, offering extra consistency and communication, however when it got here to broker-facing groups and managing clients, enchancment was wanted.

    Herbert mentioned he had heard these considerations from brokers many occasions and AMP Bank’s first precedence was to have the ability to present this data to brokers.

    “You’ve acquired to have a look at your platforms, your software program, the integrations you will have with your core banking methods first, and what’s the pathway to get to that? Providing real-time pricing, a real-time view of your buyer portfolio, it needs to be achieved.”

    Herbert mentioned in December 2023, AMP Bank had created an internet reprice type which simply required brokers to offer their account particulars. Bots may present a response in minutes, which saved brokers time on repricing.

    A retention specialist may additionally get involved with the dealer to debate the mortgage state of affairs if wanted.

    Referring to Michaels’ earlier remark about brokers controlling the expertise for the shopper up till mortgage submission, Herbert mentioned AMP Bank had been working onerous to take away this concern from brokers and clients by creating the appropriate platform and enhancing the front-end expertise.

    It needed to evaluate loans utilizing the info brokers had already validated by means of display screen scraping and digital IDs and supply certainty to brokers that they’d get a solution primarily based on the knowledge they provided.

    When the dealer portal was accomplished, brokers would be capable to take a look at their software pipeline in actual time, together with notes on the method and any conversations and interactions with clients.

    Herbert mentioned it was essential that AMP Bank labored collaboratively with brokers to offer data that will assist them with their clients.

    Rakhit mentioned brokers may entry their current clients’ mortgage data within the Bankwest Broker Portal. He mentioned the portal was the results of time, cash and funding.

    Closing its east coast financial institution branches in 2018 had freed up cash for funding in brokers.

    “I believe the largest alternative we now have as leaders of third social gathering companies is influencing these conversations about the place do our banks make investments? It’s actually pleasing that we’re investing an increasing number of in dealer options,” Rakhit mentioned.

    Lockwood mentioned ME Bank, BOQ and Virgin Money all had dealer portals, together with a dealer pricing instrument which generally offered an instantaneous resolution for on-line submissions; in different conditions it might need to be escalated.

    “We recognise the significance of making an attempt that will help you handle your time. There’s no level you sitting on the cellphone for one thing that may be achieved instantly,” he mentioned.

    Lockwood mentioned together with buyer information within the dealer portal would make the method less complicated and BOQ Group was presently working on the safety features. “Stay tuned.”

    Fedder mentioned Suncorp Bank had already constructed its dealer portal, including within the information of all clients from May 2023 onwards. Like different non-majors, the financial institution would take a look at methods to greatest pursue the continuing retention of consumers.

    “The undeniable fact that brokers see this as a vital space the place they add worth to clients implies that we have to proceed to have a look at it,” mentioned Fedder.

    Lockwood mentioned, “It’s less expensive for us to maintain an current buyer than it’s to accumulate a brand new buyer. We’d love all clients to remain and for all brokers to be comfortable.”
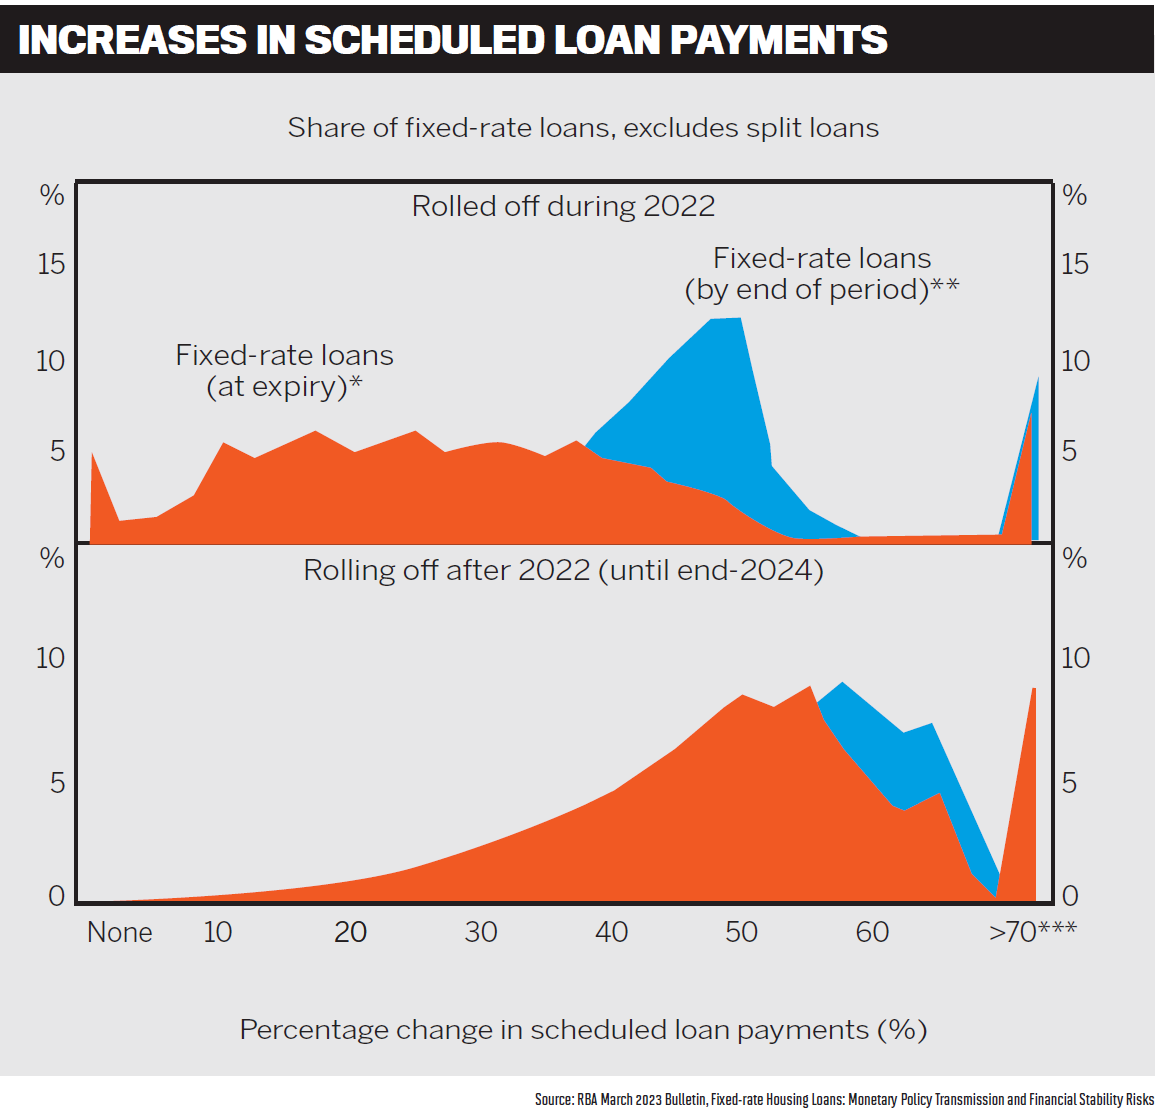
    Q: Broker query from Stephen Michaels. What are your ideas on the massive 4 banks and cases the place they obtain “particular therapy” compared to non-major banks? Example – the power to supply stream­lined refinance evaluation (i.e. 1% buffer on prime of precise fee). Is this honest? Are non-majors at a drawback with regards to implementing credit score coverage modifications?

    Rakhit mentioned the three% buffer was a requirement set by APRA to help accountable lending.

    Some main banks supplied streamline loans with decrease ranges of documentation comparable to dollar-for-dollar refinances.

    Bankwest had supplied a 1% buffer on dollar-for-dollar refinances, however just for single owner-occupier or one funding property.

    “We wanted to tell APRA that we might put sure controls in place to make sure that we weren’t taking on enterprise or threat that will be detrimental to our requirements,” Rakhit mentioned.

    Bankwest additionally needed to agree with APRA that it will solely enable a sure variety of these refinances, with the restrict reached in a short time.

    Rakhit mentioned the non-majors ought to take a look at first dwelling consumers. ‘Mortgage prisoners’ was a typical time period however there have been numerous ‘rental prisoners’ – potential first-time consumers who because of massive rents had been unable to avoid wasting sufficient for a deposit.

    “In phrases of serviceability, the first-time consumers are in all probability paying the very best fee out there and then you definitely put 3% on prime. That’s not essentially serving to us carry extra individuals into homeownership.”

    Lockwood mentioned one of many frustrations for non-major banks on 1% buffer loans was that they had been coverage exceptions and sometimes didn’t stack up because of scale.

    “When you’ve acquired a lot decrease stream than a significant and a a lot smaller steadiness sheet, since you might need a really small allocation, then how do you handle that? Is that the form of threat you need?”

    It was an unlevel taking part in discipline for the non-majors in comparison with the majors as a result of scale did depend, mentioned Lockwood.

    MPA requested Michaels if he believed the 1% buffer loans had been driving dealer enterprise to the majors.

    Michaels mentioned this was completely the case. He gave an instance of a buyer with three properties in Sydney’s japanese suburbs, totalling $3.5 million in loans within the portfolio.

    “His borrowing capability going to a non 1% buffer financial institution was a most borrowing for the family of $2.2 million,” he mentioned. “It was a $1.3 million distinction in borrowing.”

    Brincat mentioned that it was primarily buyers who had been lacking out on the 1% buffer alternatives, because of coverage standards.

    “They’re already getting hamstrung round fee. They’ve acquired a number of properties and are clearly capable of service their debt – what’s the threat? Particularly when LVRs are sub-80%.”

    Rakhit mentioned all non-majors can be happy with the low stage of arrears, given two years of COVID and 13 fee rises.

    “Our stage of arrears may be very, very low. Now this may very well be because of the 3% buffer.”

    Lockwood mentioned this was level.

    “The Australian financial system and banking surroundings might be some of the steady and dependable on this planet – it’s the partnership between banks and the regulators and the commitments that we now have.”

    Q: What are your plans to improve know-how in 2024 and the way will they enhance methods and processes for brokers and their clients? What half does AI should play?

    Fedder mentioned Suncorp Bank has a strategic partnership with NextGen and they’d proceed to work collectively, investing in velocity from software by means of to unconditional approval.

    “For me, it’s that constant strategy – the way you get quicker and quicker and take the friction out of the mannequin. We’re reflecting on what we now have achieved up to now and we’re persevering with to ask for dealer suggestions round how we are able to make that even higher.”

    Herbert mentioned velocity was an attention-grabbing level. “You will be quick, however trying again on the worth chain, how will we scale back effort? Effort for the dealer, effort for the shopper. How will we take away duplication of effort?”

    AMP Bank was eager to enhance brokers’ confidence in a lending end result.

    “Brokers often inform us they worth the power to regulate and have visibility of the expertise for his or her clients all through the house mortgage journey, nonetheless this typically breaks down as soon as a mortgage is submitted,” Herbert mentioned.

    “Providing larger confidence in outcomes earlier than a mortgage is submitted is a vital step change we see essential to assist deal with this, and delivering a number one software expertise for our brokers and their clients that offers great confidence within the end result upfront is a precedence.”

    Herbert mentioned there have been numerous instruments together with propensity modelling and AI that would assist. More essential had been the digital instruments brokers used to offer data that may very well be utilized by the lenders reasonably than duplicating the hassle already undertaken.

    Brincat mentioned numerous this got here again to banks working with aggregators which supplied great know-how. She gave the instance of Lendi Group, which was working on an approval confidence characteristic.

    “So because of this we are able to put the info within the system, and as soon as the info is correct, the system will be capable to inform us what’s the chance of that approval occurring. The work being achieved with aggregators helps us as brokers, particularly if that may be the one-stop store.”

    Brincat mentioned many brokers additionally used Quickli because of its accuracy earlier than going to a lender.

    Michaels mentioned he additionally used Quickli to streamline the method and get to the appropriate end result.

    Rakhit mentioned sooner or later loans may very well be authorized at time of lodgement. This would contain revalidating data brokers offered utilizing information factors as a substitute of paperwork.

    Bankwest was excited to introduce its first AI instrument, which helped brokers when utilizing the financial institution’s library of credit score coverage.

    “You put in sure search data, and AI will carry that data to the fore reasonably than you having to go and discover it.”

    Rakhit mentioned AI was ideally suited for repeatable duties and the plan was to increase its use.

    Bankwest had additionally spoken to Quickli, which may present “a tremendous stage of data on opponents, how they worth, how they service, what they put into their serviceability catalogue”.

    Rakhit mentioned there have been additionally different great tech firms comparable to CoreLogic, illion and Equifax that the trade may spend money on and the following few years can be thrilling.

    ING was digitising and automating the shopper journey and evaluation course of to create quicker extra streamlined buyer experiences, Thompson mentioned. “Digital validation of software paperwork is an instance. AI is seen more and more as a core functionality and alternative.”

    Lockwood mentioned 2024 can be an enormous 12 months for BOQ Group when it comes to know-how transformation.

    “One of the biggest investments that the financial institution has made ever is in a brand new dwelling mortgage program,” he mentioned.

    BOQ group had launched a greenfield digital financial institution a number of years in the past that includes all three manufacturers, Virgin Money, BOQ and ME Bank.
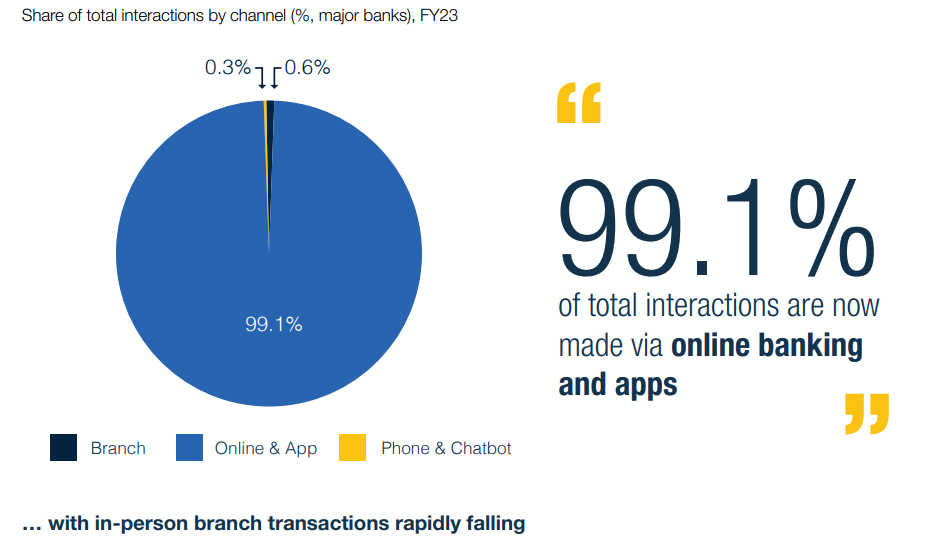
  • Monetary hardship: Banking institutions do ‘higher job’ than nonbanks, states ABA

    Financial hardship: Banking firms do ‘higher job’ than nonbanks, suggests ABA | Australian Broker News

    News

    Economical hardship: Banking firms do ‘higher job’ than nonbanks, suggests ABA

    ASIC slams lenders’ cash hardship techniques, associations reply

    Financial hardship: Banks do 'better job' than nonbanks, says ABA

    The Australian Banking Association (ABA) has responded to an ASIC economical hardship evaluation of 10 massive residence collectors, which noticed they need to actually be finishing up further to help Australians who’ve been struggling to satisfy their repayments.

    The report noticed that some lenders had manufactured accessing economical help so troublesome that much more than one in a number of (35%) Australians dropped out of the software program course of at minimal when.

    The report additionally discovered 40% of customers who acquired hardship assist by the use of discount or deferral of funds, fell into arrears splendid quickly after the help time frame completed.

    On the opposite hand, ABA CEO Anna Bligh (pictured) defended the steps of banking institutions.

    “Every one week banking firms help a whole bunch of Australians in monetary hassle with a array of life like instruments together with restructuring loans to minimize repayments, shifting people to curiosity-only preparations or most definitely deferring funds for a interval,” she talked about.

    ASIC’s consider into lenders economical hardship procedures

    ASIC then undertook a data choice involving 30 vital lenders and launched this report simply after inspecting 10 big home mortgage suppliers to comprehend their technique to financial hardship.

    This guidelines of mortgage firms included each equally banking institutions and nonbanks, equivalent to:

    As increasing numbers of Australians battle with worth tag-of-dwelling pressures, ASIC Chair Joe Longo mentioned, “In the worst situations, lenders disregarded hardship notices, successfully abandoning prospects who wanted their assist and had been being not convention neighborhood expectations.

    “For of us who get to out to their mortgage firm to signal they want help, this may be devastating,” Longo mentioned. “Too a lot of Australians in financial hardship are acquiring it exhausting to get help from their collectors and it’s time for significant enchancment.”

    All spherical, the report uncovered 4 overarching themes:

    &#13
    Creditors didn’t make it easy for purchasers to present a hardship see&#13
    Evaluation procedures had been usually difficult for purchasers&#13
    Loan firms didn’t join proficiently with customers&#13
    And susceptible prospects usually weren’t very nicely supported.&#13

    The ASIC chair reported mortgage suppliers “should enhance” the best way they provide with purchasers going by means of hardship and “is not going to hesitate” to take enforcement movement wherever right.

    Financial hardship: Crunching the small print

    Whilst ASIC’s report could seem dire, it did current some encouraging data for fiscally harassed prospects in protection of the lenders’ steps.

    Bligh claimed purchasers who’re expertise the pinch financially should take coronary coronary heart from the purpose that the report finds that 94% of all carried out functions for support ended up licensed.  

    Although solely 71% of all authentic hardship requests have been accredited, this vary jumps to a an ideal deal elevated 94% for individuals who full the whole utility system.

    This is just because some prospects (23%) withdraw their software program or are unsuccessful to present the essential data. As a finish end result, the real denial cost for completed functions is simply 6%.

    Also, though the report reported that 35% of individuals dropped out of hardship functions, it didn’t outline the nice explanation why.

    People right this moment could presumably not proceed with a hardship software program due to a wide range of explanations, these sorts of as scenario altering or they no prolonged important the assistance. Equally, they might nicely have simply positioned the system a lot too difficult.

    “Banks have longstanding preparations in put to assist folks experiencing financial issues, equivalent to actually educated and devoted hardship teams ready to help shoppers,” reported Bligh.

    ASIC additionally talked about collectors engaged constructively by means of the critique and acknowledged the price of supporting purchasers encountering economical hardship.

    At least seven of the ten collectors skilled “vital methods underway” to make enhancements to their answer to cash hardship, in accordance to the regulator.

    Some had been commencing or rising their enchancment programs and most recognised that even additional perform is important to make sure they commonly help their purchasers experiencing monetary hardship.

    On the opposite hand, ASIC Commissioner Alan Kirkland, whose remit incorporates assist for susceptible shoppers, claimed collectors had been nonetheless not “placing customers entrance and centre” of their tactic to financial hardship.

    “Many mortgage suppliers should not getting their prospects’ distinctive predicaments into consideration, as an alternative supplying a standardised ‘one-dimension-matches all method’, which isn’t convention prospects’ calls for,” Kirkland said.

    “We encourage folks frightened about creating repayments to name their monetary establishment and if not proud of the response, to lodge a grievance with them.”

    Are nonbanks the worst culprits?

    Curiously, the report distinguished a distinction between banking institutions and nonbanks in how they tactic financial hardship eventualities.

    When the procedures of the collectors reviewed “various considerably”, ASIC positioned in regular monetary institutions carried out higher than nonbanks and larger monetary institutions carried out higher than lesser banking firms.

    Nonetheless, it however acknowledged gaps within the steerage furnished by all mortgage suppliers.

    “We are impressed to note that the report finds that banks do a a lot better job than non-lender collectors and banking firms will proceed on to attempt to present their purchasers the perfect doable firm,” talked about Bligh.

    For their portion, a spokesperson from the Australian Finance Sector Affiliation (AFIA), which signifies each equally monetary institutions and nonbanks, talked about it’s inspecting ASIC’s outcomes into financial hardship strategies.

    “We will proceed to perform with associates to spice up the methods they’ve in put, ensuring they meet the evolving wishes of customers as expense-of-living pressures proceed on to extend,” the AFIA spokesperson said.

    ABA additionally claimed its associates would consider the conclusions and work with ASIC on any extra methods to assist shoppers.

    “In any organisation, there’s consistently space for development,” Bligh said. “Banks stand ready help to purchasers.”

    “That’s why the ABA has been jogging its ‘don’t troublesome it out by yourself’ marketing campaign, urging prospects experiencing monetary stress to entry out to their financial institution and get help.”

    “The earlier people obtain out to their financial institution, the more easy and extra shortly it’s for banking institutions to put help decisions in place.”

    Connected Tales

    Preserve up with the latest data and capabilities

    Be part of our mailing itemizing, it’s cost-free!