Tag: and

  • Safe Path for Client’s and Companies

    As completely everyone seems to be commencing to acknowledge, the general economic system is slowing
    owing to the Federal Reserve tightening (elevating charges), Tariff battles, and
    inflation creeping into our day-to-day life.  

    What must not be a shock is we’re 10+ a very long time earlier the earlier recession.  The historic atypical restoration interval is 7
    a few years. 
    In the home mortgage market all of us basically get revenue from the
    related space to lend to shoppers.  The


    competence and help we offer is the differentiator for shoppers.  Unlicensed Financial establishment Originators and Licensed
    Non-Financial establishment Originators, shell out 6-8 a number of hours working with a client.  The shopper spends 15 – 30 a few years with their
    help.  Based totally on the automated
    underwriting methods (AUS aka LP / DU), the last word cost is acknowledged quickly after utility.  Consumers are much better served to not be involved about an
    1/8  or a 1/4 per cent up or down.  Get the simplest product for your necessities and
    select a Loan Originator that’s licensed by your state and that focuses on have to have and not payment.  Level shall be what it’s based on the confirmed particulars within the mortgage mortgage software program.

    House mortgage corporations usually contend on the idea of
    Competence, Services, or Amount.  There is a
    prudent concord for new family potential patrons.  Costs are established by secondary marketplaces and the danger / economical dynamics of the corporate presenting them.  However many suppliers are usually not knowledgeable of their chance profile nor the small print that impacts their web margins.  I join with that driving with a blacked out entrance windshield and no speedometer.

    The romantic relationship involving the speed a buyer will get and the speed
    previous to hazard premium and allocation of expenses to shut usually has a fixed
    “unfold” or margin.  There isn’t any particular
    within the mortgage cost sector.  If you
    reduce expenses previous what regular spreads situation with no slicing bills or lending to raised FICO, LTV, DTI debtors,
    there’s a consequence down the road. 
    Most Home mortgage Originators don’t care nevertheless, their consequence is acquiring a
    new employer down the road.

    In actuality, because the financial local weather slows debtors have greater
    curiosity funds on credit score taking part in playing cards, their job would possibly slide prey to downsizing, and so on.  As a outcome, the danger high quality required in
    pricing mortgage mortgage loans must go up not down. 
    Very finest state of affairs, the margin stays the similar however the costs will improve
    proportionately with the present market or disregarding sustainable progress will assert
    its preliminary recessionary property finance mortgage company sufferer.  366 Mortgage Corporations failed https://ml-implode.com/ organising in 2006 (6 many years following the restoration) with the capitulation in 2008.  Lots of of you’ve gotten a few of these suppliers in your resume.  Understand from their blunders.

    At the end of each financial cycle I see teams of house finance mortgage
    organizations fear and artificially reduce prices to create a brief-time interval enhance
    in amount.  If they did the investigation,
    they might uncover this doesn’t change the trajectory of an monetary cycle’s
    impression on mortgage mortgage quantity.  It is sort of
    like flapping your arms though falling off a mountain.  Flapping could presumably make you’re feeling improved however gravity
    has its personal technique that you’ll not change the tip outcome.

    Cal Haupt, Chairman & CEO

    Southeast Home finance mortgage of Georgia, Inc.

    Celebrating 25 a number of years

    My suggestions based mostly totally on my learnings from three worthwhile
    recession crossings, think about buyer will want and keep in mind origination amount does
    not pay again the payments.  Profits and Competence
    is the risk-free bridge to cross uncertain waters. 

    The services or products you set
    your shopper in is not only one more shut mortgage, it’s the foundation for your
    consumer’s family members and long term.

    www.southeastmortgage.com
    Mobile cellphone: 770-279-0222

  • Curiosity Costs and Dwelling Prices

    Penned on 3 February 2023 by Ray Boulger

    Interest Rates and House Prices

    While the preliminary media goal on February’s Lender Level alternative was on the .5% increase, that was not probably the most important side of the MPC’s announcement. Arriving at a desired vacation spot vastly predicted by most market place members, as was the Financial establishment Level improve to 4%, shouldn’t be in itself heading to have a fantastic deal have an effect on on present market prices.

    Considerably much more necessary was the dovish tone adopted, for the first time because of the reality charges begun rising. Despite the truth that the MPC caveated its responses by declaring: “there had been sizeable uncertainties all around the outlook”, it now appears to be very not going the Financial establishment Amount will arrive at 4.5% on this cycle and a strong probability it can peak at 4%.

    The MPC additionally commented that: “the current location of Financial establishment Fee can be possible to decrease inflation to completely below consider within the medium time period. As the coverage location skilled become extra and extra restrictive, this might convey ahead the place at which new value improves would require to be reversed.”

    The results on the gilt trade was extraordinary, with huge falls in yields for a solitary day – e.g. the 5 calendar 12 months gilt yield fell by 30b.p. Swap prices matched the slide in gilt yields and as a final result we are able to count on a brand new sub 4% benchmark to be quick acknowledged for aggressive 5 12 months preset mortgage charges.

    With unique tracker and low cost prices transferring larger than the best 5 calendar 12 months preset prices – and in lots of eventualities within the close to potential nearly actually additionally 2 yr fixes – the selection of irrespective of if to decide on for a fixed or variable degree (tracker or cheaper price) turns into far more difficult and is a dialogue nearly each borrower actually ought to have with their unbiased home mortgage adviser, based mostly on their customized conditions.

    The argument for sticking with a tracker or cheaper price degree is that, even whereas the pay again value could be very more likely to be higher than charges out there on a brand new mounted quantity, it’s a promoting value price having to pay within the expectation of receiving a a lot cheaper mounted cost afterwards this 12 months. The draw again of this argument is that you’ll eventually want a good cheaper mounted charge to make up for shelling out additional in extra of the next couple months and it is going to be difficult to know when to swap preset charges could maybe now drop additional slowly and, because the MPC stated: “There are sizeable uncertainties all around the outlook.”

    On the opposite hand, as most trackers don’t have any ERCs everybody with a tracker who’s planning to maneuver within the upcoming 12 months or so could maybe really really feel that paying out a a little bit higher value than is out there on a preset cost is a superior trade-off for not having any ERCs.

    Apart from the affect on the mortgage mortgage market there will likely be a number of different knock-on outcomes from the autumn in gilt yields, together with a reward for The Chancellor with a big discount in Uk Authorities borrowing expenditures.

    Just one different evident have an effect on from mortgage charges peaking reduce and earlier than than previously anticipated, and beginning off to tumble sooner, is that home value ranges will drop loads lower than appeared possible in Oct final 12 months.

    Although a number of economists take pleasure in their seasonal changes, my view is that the seasons at the moment are primarily irrelevant to property prices, while to not transaction volumes, and there could be minor query that the brand new drop in residence costs is right down to different elements.

    Dependent on the Nationwide true property price ticket index – i.e. not the much more broadly quoted seasonally adjusted 1 – value ranges have fallen by 5.6% from their August peak to January, with a tumble of 1.4% in January. In a weblog I posted on 11/10/22 quickly proper after the Truss/Kwarteng mini value vary I forecast that the 12 months-on-calendar 12 months index would change unfavorable in March or April this yr but it surely now seems to be somewhat most likely this may transpire as shortly as this thirty day interval.

    I additionally proposed that charges would fall by 15% from their peak however with the ending of the financial illiteracy of the Liz Truss interval and the next speedy enhancement within the need value outlook I now think about the slide will solely be throughout 10%.

    Category: Ray Boulger

  • Penrith pulls shared possession bargains and adds new fixes – House loan Strategy

    Penrith Setting up Society has withdrawn its shared possession offers to evaluation its lending on this spot.

    At the same time the lender has launched a couple of new mounted prices and created a quantity of merchandise enhancements.

    Penrith’s shared possession offers skilled been low cost variable charges, which it states haven’t proved widespread, so it’s now analyzing its requirements and contemplating bringing out preset payment promotions.

    On the opposite hand, it claims it continues to be dedicated to initial-time purchasers and supporting shared possession as aspect of this.

    Penrith’s new reductions are all two-yr set premiums at 5.19%.

    Its Heartland spend money on set worth, for debtors inside simply its catchment area,  has no charges and is on the market as much as 90% LTV, with a most mortgage of £500,000.

    Its National receive set cost, for debtors open air the house, has a product worth of £499 with the identical utmost LTV and loan sizing.

    Penrith’s Heartland remortgage, has no bills, and is obtainable as much as 80% LTV on loans of as much as £750,000.

    The monetary establishment has additionally decrease the fork out degree on its expat acquire-to-permit three yr low price quantity from 7.23% to five.59% (or 2.4% down beneath its SVR).

    Penrith has improved the optimum LTV on every its Heartland remortgage and National buy two-calendar yr worth lower bargains from 80% to 90%.

    Nonetheless, for equally options it has diminished probably the most financial institution loan dimensions from £750,000 to £500,000.

    On the new fastened quantity launches, head of products Tim Vigeon suggests: “The premiums, mixed with our prevalent-perception underwriting will make the wishes of individuals wishing to buy a family or remortgage their current dwelling a fact.

    “Our different modifications mirror strategies that we now have obtained and enhance our generally proposition inside simply the market.

    “We repeatedly assessment our merchandise and standards with shoppers and brokers on the coronary coronary heart of our considering and additional extra modifications might be declared over the approaching weeks.”

  • Great importance Of Credit rating Score In Mortgage Funding And How It Will get Amplified

    The credit score historical past rating is cherished to assemble your image in addition to acquiring execs though making use of for the private mortgage. Most of the individuals don’t consider the credit score historical past rating given that they’re absent from the price of this. A credit score rating rating is expounded to match rating, however the large distinction is that credit score calls for in banking and recreation want within the take pleasure in floor. But the importance of each equally may be very similar in two various locations.

    How to enhance the credit score rating:

    The credit score rating scores couldn’t be amplified shortly as women and men promote on 7 days, months or couple of occasions. The phony commitments don’t stand anymore as a result of the precise rating asks for the precise facets. You need to fork out the month-to-month invoice on an right day. Your faith and rating will robotically maximize as the cardboard is utilized lower than the foundations and phrases of financial institution and a private monetary establishment.

    Now a number of banks give the provision to purchaser through the use of the credit score rating supplier by way of their farm. Also, some delivers to insert card beneath your key card presents the terrific worth discount as properly as particulars. Using two taking part in playing cards from the similar financial institution makes the constructive photographs and using it for max looking out current the terrific low cost charges as completely because the rating to card.

    A session with property finance mortgage funding help is essential to enhance credit score rating just because they will advise you higher to make use of it for incomes factors. Various approaches could make fast to up the rating, and these could be completed by the collectors so you could check out as quickly as to undertake the useful strategies.

    How the credit score rating rating is critical all through the finance:

    If we talk about about mortgage then numerous house mortgage mortgage suppliers Florida are ready to supply the income as considerably as the patron necessity. But a single factor they wish to ensure that is the standing of a borrower and this may very well be confirmed by quite a few strategies equivalent to inquiring to neighbors, lender or get the job achieved put. But credit score rating rating which is offered by the monetary establishment with paying out properly timed mortgage funds impacts elevated to create a monitor file.

    The monetary establishment will blindly trust within the buyer to present higher funds proper after seeing the historic previous credit score historical past rating. Most of the events it will get tough to confirm the client’s picture just because, they will arrange the fake recordsdata. For that motive it’s far more intricate to get again once more money for a monetary establishment which is why they maintain within the queue private mortgage acceptance. But when you’ve got glorious credit score rating background then they don’t fear about providing the {dollars} and are available to really feel completely free to current the opposite services and products.

     At remaining, if you’re organizing for private mortgage and wish to get speedy approval then preferring the credit score rating is significant.  Make your credit score rating no matter whether or not you might be additionally not fascinated about monetary mortgage correct now given that may very well be using for foreseeable future.

  • 5 Approaches to Decrease Taxready Earnings and Hold Extra Money in Your Pocket

    The ongoing superior price of residing has fairly just a few Australians searching for methods to maintain more money in their possess pockets and shell out lots much less at tax time. As tax time methods, there’s no improved time to uncover fiscal methods that would assist scale back tax liabilities. By leveraging these cash tools and savvy methods, it’s attainable to enable you to save money while nonetheless being compliant with Australian tax pointers. Browse on as we share six efficient procedures to receive this intention.

    2-Feb-13-2024-12-41-08-5133-AM

    1. Use Salary Sacrificing

    Wage sacrificing permits taxpayers to divert part of their pre-tax wage in the course of positive constructive points. The hottest earnings sacrifice advantages are superannuation contributions, motor vehicles, and digital tools. Income sacrificing could be utilised to spend for a brand new automobile, laptop computer, protection, lease funds, house finance mortgage funds, or different positive aspects, whereas saving numerous numbers of kilos in taxes yearly. Many employers provide wage sacrificing preparations, so it is actually value testing this various together with your HR division or monetary adviser.

    2. Continue to maintain Correct Tax and Financial Records

    About the sooner few yrs, the ATO has tightened up on scrutiny, in distinctive in the locations of report-maintaining, income and deductions, which is why conserving meticulous data of income, prices, and investments is so vital when it comes to optimising tax deductions. Use digital assets and apps to streamline document-keeping and give your self sufficient time to do the job because of your tax return to avoid speeding and producing errors. By being organised and retaining maintain observe of of deductible prices, you possibly can maximise your tax deductions and lower your taxable cash.

    3. Assert ALL Deductions

    Verify that you just is perhaps saying all eligible deductions that make the most of to your situation. If you make investments any cash related to incomes an earnings, expense houses, instruction or scientific prices, you’ll need to assert it. Be assured to maintain receipts and documentation to again again-up your claims in state of affairs of an audit and search the recommendation of with a professional tax specialist who can assist you determine any deductions you might maybe have missed in buy to get essentially the most out of your tax return.

    4. Add to Your Tremendous to Save Tax in Australia

    Building supplemental contributions to your superannuation fund could be a tax-successful approach to increase your retirement financial savings and lower down taxable cash. (*5*) great contributions, these sorts of as wage sacrifice or specific deductible contributions, are taxed at a decreased worth inside simply the great fund – a charge of simply 15 for each cent – in comparability to the marginal tax charge which might be as excessive as 49 for each cent!

    5. Minimise Expenses with a Mortgage Offset Account

    A house finance mortgage offset account could be a efficient software for lowering taxable earnings whereas saving on mortgage mortgage need funds. By depositing worth financial savings or getting your earnings compensated into a particular offset account related to your residence mortgage, you possibly can offset the curiosity charged in your mortgage steadiness. Not solely does this decrease the sum of curiosity payable in your property financial institution mortgage, however it could additionally speed up your route to receiving debt-absolutely free.

    6. Get Private Well being Insurance insurance policies

    Investing in private wellness insurance coverage insurance policies offers vital healthcare safety and can supply some tax rewards additionally. Devoid of personal clinic insurance coverage plan, for those who’re solitary and achieve much more than $90k for each yr, or you’re a family incomes much more than $180k a 12 months, you’ll pay again a minimal quantity a single for every cent Medicare Levy Surcharge on main of the required two per cent Medicare Levy that the majority taxpayers have to pay. Basic non-public well being care methods can cost lots lower than the only one for every cent Levy Surcharge on gross earnings, so for some males and ladies, discovering private effectively being insurance coverage could make good fiscal sense.

    Maximising Discounts to Access Fiscal Plans

    No 1 would love to fork out much more tax than they’ve to, which is why it’s so important to perceive the vital methods for maximising reductions and lessening taxable earnings. By making use of these 6 strategies, it’s possible to correctly minimise the sum of tax you’re essential to shell out, income which may go into your again once more pocket in its place!

    For extra fiscal data tailor-made to your one among a sort scenario, get in contact with the group at Home mortgage Specific.

    While all therapy has been taken in the getting ready of this publication, no guarantee is specified as to the precision of the data and no obligation is taken by Finservice Pty Ltd (House mortgage Categorical) for any glitches or omissions. This publication doesn’t represent personalised economical ideas. It won’t be related to private circumstances. Absolutely nothing in this publication is, or ought to actually be taken as, a suggestion, invitation, or advice to buy, promote, or maintain any monetary dedication in or make any deposit with any specific individual. You ought to search certified steering prior to taking any movement in relation to the issues dealt in simply this publication. A Disclosure Assertion is obtainable on ask for and no price of cost.

    Finservice Pty Ltd (Property finance mortgage Categorical) is authorised as an organization credit standing guide (Corporate Credit historical past Representative Amount 397386) to engage in credit score rating actions on behalf of BLSSA Pty Ltd (Australian Credit Licence quantity 391237) ACN 123 600 000 | Complete member of MFAA | Member of Australian Financial Problems Authority (AFCA) | Member of Option Aggregation Providers.

  • 25 First-Time Florida Home Buyer Grants and Programs in 2024: Ranked

    Expert Answer: Hey Johnny. We specialize in down cost help for Florida homebuyers so that you’re in luck.

    We’ve put collectively a listing of each Florida first-time homebuyer grant in the state in 2024 and our Florida mortgage consultants have ranked them for you!

    And keep in mind, in case you need assistance determining what you are eligible for, we’re blissful to assist!

    In Florida, as of 2024, first-time homebuyers have entry to 25 totally different applications that present alternate options to the standard 20% down cost.

    These applications embrace money grants, tax credit, and lowered mortgage charges, providing sensible options for these seeking to buy their first house.

    Remember, whereas every house help program has distinctive phrases, the overall {qualifications} embrace:

    Being a first-time house purchaser in line with this system’s definition.

    Completing a house purchaser training course.

    Adhering to specified earnings and buy worth limits.

    Purchasing a property in an accepted space.

    Using the house as your main residence.
    A large board with title Home Buyer Grants and Programs in Florida

    Florida Hometown Heroes Program

    The Florida Hometown Heroes Housing Program offers down cost and closing price help to first-time, income-qualified homebuyers who work or serve in the Florida group the place the house is being bought.

    The Florida Hometown Heroes Program presents substantial advantages and help for first-time homebuyers who work or serve in their native communities.

    Key advantages of this system embrace as much as $35,000 in help for down funds and closing prices, together with a decrease first mortgage rate of interest for eligible debtors.

    Additionally, no month-to-month mortgage insurance coverage premiums (PMI) profit these choosing FHA loans. This program is particularly tailor-made for buying a main residence in the group the place the borrower works or serves.

    To be eligible, candidates have to be first-time homebuyers employed in or serving the group the place they intend to buy the house. They should meet sure earnings limits primarily based on family measurement and location and have a credit score rating of at the very least 620.

    (*25*)FHA Loan Program

    FHA loans, backed by the Federal Housing Administration, are a tried-and-true resolution for homebuyers, notably these buying their first house.

    They require a decrease minimal down cost, as little as 3.5%, and are extra accessible to patrons with decrease credit score scores than standard loans.

    FHA loans additionally enable for larger debt-to-income ratios, offering extra flexibility in qualifying for a mortgage. Additionally, they provide the choice of a decrease rate of interest, making them a beautiful choice for these seeking to decrease upfront prices and month-to-month funds.

    Miami-Dade Advocacy Trust Grant

    The Miami-Dade Advocacy Trust grant’s Homeownership Assistance Program presents as much as $28,500 in no-interest, no-payment mortgage type for down cost and closing prices to first-time homebuyers in Miami-Dade County, primarily based on earnings.

    This mortgage is forgiven after 20 years, supplied the borrower continues to occupy the house.

    Eligibility features a requirement for candidates to contribute their very own funds towards the acquisition and to safe a mortgage via an accepted lender, guaranteeing a dedication to homeownership and monetary accountability.

    Hallandale Beach Community Grant

    The Hallandale Beach Community Grant, facilitated by the Hallandale Beach Community Redevelopment Agency, assists first-time homebuyers with as much as $100,000 for down cost and closing prices.

    This substantial help is aimed toward encouraging homeownership throughout the Hallandale Beach group reinvestment space.

    The help comes as a no-interest mortgage, forgivable after the borrower maintains the property as their main residence for at least ten years.

    To qualify, candidates are required to speculate $2,000 of their very own funds in direction of the down cost, amongst different eligibility standards, demonstrating a private dedication to homeownership in Hallandale Beach.

    Own a Home Opportunity Grant Program

    The Own a Home Opportunity Grant Program (OAHO) represents a major stride in direction of making homeownership extra attainable for residents throughout a number of Florida counties.

    Designed to reduce the monetary burden on homebuyers, this program extends a beneficiant provide of as much as 5% of the entire mortgage quantity.

    This help will be utilized in direction of a down cost or to cowl closing prices, immediately addressing two main monetary hurdles in the homebuying course of.

    Eligibility for the OAHO grant is prolonged to patrons in a variety of counties: Broward, Charlotte, Collier, DeSoto, Lee, Palm Beach, Sarasota, St. Johns, and Volusia.

    This broad eligibility standards be sure that a considerable variety of potential householders can profit from this system, fostering homeownership alternatives throughout various communities.

    To qualify for the OAHO grant, candidates should meet particular monetary standards, together with adhering to earnings and buy worth limits, guaranteeing that this system advantages those that want it most.

    Additionally, a credit score rating of at the very least 640 is required.

    Own a Home Opportunity Program

    The Own a Home Opportunity Program is a monetary help initiative designed to help first-time homebuyers in Florida.

    Targeting a number of counties, together with Charlotte, Collier, DeSoto, Lee, Sarasota, and particularly Palm Beach County, this system seeks to make homeownership extra accessible and reasonably priced.

    Eligible members in Charlotte, Collier, DeSoto, Lee, and Sarasota counties can obtain as much as $7,500 in help for down funds and closing prices.

    To handle the various financial landscapes throughout these areas, this system presents an elevated help quantity of $10,000 to patrons in Palm Beach County, recognizing the distinctive monetary challenges confronted by residents in this space.

    The monetary support supplied by the Own a Home Opportunity Program comes in the type of a zero-interest, deferred mortgage, including an additional layer of affordability for first-time patrons.

    The Good Neighbor Next Door (GNND) Program

    The Good Neighbor Next Door (GNND) Program is a U.S. Department of Housing and Urban Development (HUD) initiative to encourage group revitalization and homeownership.

    This program presents vital monetary help to eligible academics, regulation enforcement officers, firefighters, and emergency medical technicians (EMTs) once they buy houses in designated revitalization areas.

    Key options of the GNND Program embrace offering eligible members with a considerable low cost of fifty% off the checklist worth of houses situated in these areas. In trade, members should decide to utilizing the house as their sole residence for at the very least 36 months.

    This dedication is a part of HUD’s effort to strengthen communities and foster a way of funding and stability in these areas.

    HOME Homebuyers Program

    The HOME Homebuyers Program presents as much as $12,500 in down cost and closing price help as a zero-interest deferred mortgage to first-time homebuyers in Escambia County and Pensacola.

    This monetary help is designed to make homeownership extra accessible by easing the preliminary monetary burden, with out the strain of rapid compensation or curiosity accumulation.

    Eligibility standards embrace houses constructed after 1978, adherence to HOME worth limits, and location throughout the specified areas. This ensures this system helps fashionable, protected housing and stays centered on serving the local people.

    Through offering important monetary help and clear eligibility tips, the HOME Homebuyers Program considerably aids in selling homeownership, supporting the financial and communal development of Pensacola and Escambia County.

    SHIP First Time Homebuyers Program

    The SHIP First Time Homebuyers Program, supported by state funds in Pensacola and Escambia County, offers as much as $25,000 in down cost and closing price help.

    This help, decided by the borrower’s earnings, is delivered as a zero-interest deferred mortgage, which means there isn’t any curiosity accumulation through the deferment interval.

    A key eligibility issue is this system’s broad definition of a first-time purchaser, together with those that have not owned a house in the final three years. This flexibility makes it simpler for extra people to entry this system and pursue homeownership.

    VA Mortgage

    The VA mortgage is a 100% mortgage assured by the Department of Veterans Affairs and is particularly designed for active-duty navy members, veterans of the armed providers, and surviving spouses.

    VA loans don’t require mortgage insurance coverage and have a minimal credit score rating requirement of 620. Eligible patrons can make the most of VA loans to buy residential properties with 1-4 items throughout all 50 states and U.S. territories.

    Panama City Grant

    The Panama City Grant: Homeownership Assistance Program offers first-time homebuyers with as much as $50,000 to cowl closing prices, down funds, and mortgage funds.

    This monetary help is prolonged as a second mortgage, accommodating a various vary of house sorts to make sure broad accessibility.

    To be eligible, the acquisition worth of the property should not exceed $300,000, permitting for all kinds of housing choices inside this funds.

    This program goals to make homeownership extra attainable for first-time patrons in Panama City, supporting their journey in direction of proudly owning a house.

    USDA Mortgage

    The USDA mortgage is a 100% mortgage supported by the U.S. Department of Agriculture. It is particularly designed for houses in non-urban communities, which account for 91 % of the United States land mass.

    USDA mortgages are a wonderful choice for patrons with a minimal credit score rating of 580, as they permit 100% financing. Furthermore, USDA mortgage charges are ceaselessly essentially the most reasonably priced low-down-payment mortgage loans.

    FHFA First-Time Home Buyer Discount

    In 2024, first-time homebuyers will obtain a reduction on rates of interest for his or her loans from the Federal Housing Finance Agency (FHFA) to make housing extra accessible. To be eligible, you need to meet these standards:

    First-time homebuyers who’re eligible might obtain computerized mortgage charge reductions of as much as 1.75 proportion factors on standard 30-year fixed-rate mortgages, which might scale back month-to-month mortgage funds by as much as 20%.

    The quantity of mortgage charge reductions for first-time homebuyers will fluctuate relying on elements akin to credit score rating, the quantity of the down cost, the kind of property, and the mortgage program.

    Dare to Own the Dream

    Tampa’s Dare to Own the Dream program presents eligible homebuyers as much as $40,000 in help for down cost and closing prices.

    This help is supplied as a deferred-payment mortgage that’s utterly forgiven after 10 years of possession and occupancy.

    Applicants are required to collaborate with city-approved counseling companies, mortgage officers, and actual property brokers to make sure a complete help community all through the homebuying course of.

    A private monetary contribution in direction of the acquisition can be mandatory, reinforcing the customer’s funding in homeownership.

    Properties eligible for this program have to be inside Tampa metropolis limits and cross a metropolis inspection, guaranteeing security and compliance requirements are met.

    East Tampa CRA Down Payment Assistance Program

    The East Tampa CRA Down Payment Assistance Program targets first-time homebuyers in buying throughout the East Tampa group reinvestment space, providing as much as $50,000 in help.

    This zero-interest mortgage aids in protecting down cost prices and is forgiven after the house stays the customer’s main residence for seven years.

    Eligibility mirrors that of the DARE program, with the important thing distinction being the property’s location throughout the East Tampa CRA, guaranteeing centered help for homebuyers in this particular space.

    HomeReady

    HomeReady is a mortgage program that gives decrease charges and prices to low- and moderate-income house patrons and a 3% down cost choice.

    To be eligible for HomeReady, you need to have a minimal FICO rating of 620.

    When shopping for a HomePath property with HomeReady, you will get a $500 credit score for closing prices. The HomePath Ready Buyer program additionally presents a 3% money contribution to cowl your mortgage closing bills.

    Fannie Mae’s Standard 97% LTV Loan

    This program is designed for first-time homebuyers who may not have a big down cost. The Standard 97% LTV (Loan-to-Value) Loan by Fannie Mae permits patrons to finance as much as 97% of their house buy, which means they solely have to put down 3%.

    This program is much like the HomeReady mortgage however doesn’t have as many earnings restrictions. It requires at the very least one borrower to be a first-time homebuyer and has a minimal credit score rating requirement, which might fluctuate relying on the lender.

    Home Possible

    Home Possible is a mortgage program for low and moderate-income house patrons that enables a 3% down cost, much like HomeReady. It offers lowered mortgage charges and prices and contains fixed-rate and adjustable-rate mortgage choices.

    Home Possible requires a minimal FICO rating of 660 to qualify. It is a wonderful alternative for multi-generational households in search of a mortgage with a low down cost.

    The National Homebuyers Fund

    Homebuyers can make the most of the National Homebuyers Fund, a non-profit public profit company that gives money grants as much as 5 % of the acquisition worth.

    To be eligible, you need to decide to residing in your new house for at the very least 5 years. Sadly, renters can not apply immediately – solely their mortgage firm can apply on their behalf.

    Forgivable Mortgages

    Forgivable mortgages are a kind of mortgage that may be canceled after a house owner meets sure situations, akin to making common funds for an agreed-upon interval.

    In this situation, a first-time purchaser would use a standard mortgage to buy a house and make the down cost with a forgivable mortgage of $15,000, for instance.

    Suppose the customer resides in the house and meets their cost obligations for the agreed-upon time period, normally 5 years. In that case, the lender will forgive the $15,000 mortgage and launch their declare on the property’s title.

    Forgivable mortgages are a preferred software governments leverage to advertise homeownership, neighborhood growth, and native funding – all mandatory for a thriving economic system.

    If you may have ever come throughout cities providing incentives for people to maneuver there, forgivable mortgages are possible built-in into that technique.

    Discounted Homes from HUD

    The Good Neighbor Next Door Program (GNND) by the U.S. Department of Housing and Urban Development (HUD) presents repossessed houses to first-time patrons at a 50% low cost.

    This program is designed for academics, firefighters, regulation enforcement officers, and emergency medical technicians who wish to reside in the group the place they work. To apply for GNND, one can seek for eligible houses on the HUD web site and apply for a mortgage on-line.

    Down Payment Loans

    Down cost loans are loans from non-profit and group organizations that exchange a house purchaser’s down cost with borrowed money. Interest charges on these loans are normally in the one-percent vary and amortized over 30 years for ultra-low funds.

    To see if down cost loans can be found in your space, contact your municipal authorities’s housing administration, which might provide native connections.

    However, some mortgage applications don’t enable down cost loans, so patrons ought to test with their lenders earlier than making use of.

    Deferred Mortgages

    Deferred mortgages enable debtors to delay compensation till they promote or refinance their house. Municipal governments and native foundations usually provide them.

    They can present as much as $25,000 in funding for first-time homebuyers who meet sure standards, together with having an earnings under the realm common and a credit score historical past with a monitor file of on-time funds.

    Every session, Congress helps first-time house patrons by introducing laws to help renters in changing into householders. In the present session, Congress is predicted to current two important payments – a tax credit score and a money grant.

    The $15,000 First-Time Home Buyer Tax Credit

    The proposed $15,000 First-Time Home Buyer Tax Credit goals to help people buying their first house.

    This program, impressed by an analogous initiative from 2009, is designed to ease the monetary burden for first-time householders.

    Key Aspects:

    Eligibility – Targets first-time homebuyers.

    Refundable Credit – Offers a tax credit score of as much as $15,000.

    Purchase Period – Applicable for houses purchased after December 31, 2020.

    Tax Deductions – Includes the potential for claiming mortgage curiosity and credit for house enhancements.

    The $25,000 Down Payment Toward Equity Cash Grant

    In addition to the tax credit score, the Down Payment Toward Equity Act proposes additional monetary help.

    This grant is aimed toward first-generation house patrons and these from deprived backgrounds, providing as much as $25,000 to help house purchases.

    Elements of the Grant:

    Amount – Up to $20,000 for first-generation patrons, plus an extra $5,000 for patrons from deprived backgrounds.

    Usage – Covers down funds, closing prices, and actual property taxes and allows decrease mortgage charges.

    Legislative Status – Currently proposed, with expectations of reintroduction in the present Congressional session.

    Florida Homebuyer Programs and Grants FAQs

    We’ve answered some widespread questions that you might have whereas making an attempt to select a grant or program right here:

    How do I decide which Florida first-time homebuyer grant is true for me?

    Consider your location, earnings, credit score rating, and the kind of property you are in. Matching these elements with the precise necessities of every program might help slim down your choices.

    Can I apply for multiple grant program at a time?

    Yes, relying on the applications’ guidelines. Some might enable combining grants for higher help, however at all times test the precise eligibility necessities and restrictions.

    What are the advantages of finishing a house purchaser training course?

    Besides being a requirement for many applications, these programs present helpful info on the homebuying course of, monetary planning, and homeownership duties.

    Are there grants accessible for houses outdoors city areas?

    Yes, applications just like the USDA mortgage are particularly designed for rural areas, providing 100% financing and low charges to encourage homeownership in much less densely populated areas.

    How does the first-time homebuyer definition have an effect on eligibility?

    Most applications outline a first-time homebuyer as somebody who hasn’t owned a house in the previous three years. This broader definition permits extra people to qualify for help.

    What position does my credit score rating play in qualifying for these applications?

    Your credit score rating can affect which applications you are eligible for and the quantity of help you possibly can obtain. Programs usually have a minimal credit score rating requirement.

    Can I take advantage of these grants for any sort of house?

    Each program has its personal restrictions on the kind of properties eligible, akin to single-family houses, condos, or townhouses, and some have worth limits or location necessities.

    What occurs if I transfer out of my house earlier than the grant’s occupancy requirement is met?

    You might should repay the grant or a portion of it, relying on the precise phrases of this system. These necessities are designed to encourage long-term homeownership and group funding.

    How do earnings and buy worth limits have an effect on my eligibility?

    These limits make sure the applications help these most in want and fluctuate by location and family measurement. Staying inside these limits is essential for qualifying for help.

    Where can I discover extra details about making use of for these applications?

    Visit the web sites of the precise applications you are in or contact native housing authorities. They can present detailed info, software tips, and help all through the method.
  • What Is Smaller Business enterprise Personal loan And How To Locate Most effective Loan company For Rewarding Provide?

    The achievement of a company is based totally on adopting the frequent strikes in response to the sector. For creating the information, the group ought to give the newest market’s firms, and possibly, you skilled began out the small enterprise from compact diploma. And now you need to switch as for each the present must get the higher product gross sales.

    Thus modest group private loan is helpful to complete the merchandise.

    The place the smaller company private loan is optimized:

    .1. Acquiring gear:

    If you might be manufacturing enterprise, and need to enhance the gadgets then this fashion of private loan might be useful. The tiny enterprise loan company can provide the anticipated amount to bettering the enterprise depending on the earlier cash.

    2. Renting or acquiring property:

    Primarily, small firms are commenced on the leased property or personal compact place. But simply after receiving the achievements, it needs the large location to increase the productions. And additionally if you wish to begin out the modest small enterprise then the private loan can help to put money into or renting the home.

    3. Get began up the company:

    The enterprise enterprise private loan might be provided for a jogging enterprise or beginning up the brand new undertaking. If you might be scheduling to open the enterprise, then this number of financial institution loan can present the expected money to start up. The loan supplier calls for stable documentary proof to the surety of recovering the funds like shopper {qualifications}, the enterprise sort and idea of earnings, and plenty of others.

    How to seek out the right enterprise loan provider:

    If you might be residing within the united situation, then many Florida small company private loan loan suppliers are available to supply the money at economical curiosity premiums. The supreme approach to know in regards to the company is social media, search for engine. It is straightforward to acquire company’s feedbacks by the use of net web page evaluation, social assessments.

    Right after making use of the supplier, every particular person purchaser provides the constructive or destructive feedback that are helpful for the long term shopper to select the company. Hence a brand new consumer must usually want to acquire the lender’s site and do some exploration to get the feedbacks.

  • The 2-1 vendor-paid out buydown: A potent instrument for homebuyers and household sellers

    &#13
    &#13

    Today’s housing market is undeniably distinctive from what it was throughout 2021 and early 2022. Elevated need charges and residences sitting down in the marketplace place for extra time intervals of time have modified traditionally very low curiosity prices and a extremely popular present market characterised by bidding frenzies. Whether you might be at the moment a homebuyer, residence vendor, or each of these, you could shock what this suggests for you. It might signify that now’s a very good time to simply take fringe of a 2-1 vendor-paid out buydown.

    Buydown ideas

    What precisely is a buydown? It’s when factors—generally known as discounted elements, mortgage particulars, or pay as you go curiosity—are made use of to put money into down a mortgage’s curiosity value as a a single-time upfront fee. The worth of 1 explicit challenge equals a single % of the principal (unique mortgage quantity), that signifies that one level on a $100,000 mortgage would equal $1,000. When which is a gentle worth all through mortgage suppliers, the amount of cash that 1 degree will decrease a mortgage’s rate of interest can vary involving mortgage suppliers and relies on further parts similar to the private mortgage model and present prices. It’s additionally essential to bear in mind that there could possibly be buydown maximums.

    Then, there are numerous approaches for the cost of a buydown to be paid, together with borrower-compensated and seller-compensated. Just as they audio, debtors cowl the expense with a borrower-compensated buydown, and sellers shield the price with a seller-compensated buydown.

    The social gathering accountable for fee isn’t the one challenge that may differ—completely different buydown sorts are available. They might be eternal or momentary and make the most of to set-level and adjustable-rate mortgages. With a long run buydown, the fascination quantity will get bought down for your complete financial institution mortgage time period. In comparability, the curiosity quantity receives acquired down for distinct a long time of the mortgage phrase with a brief time period buydown. A 2-1 buydown is a well-liked brief time period software program.

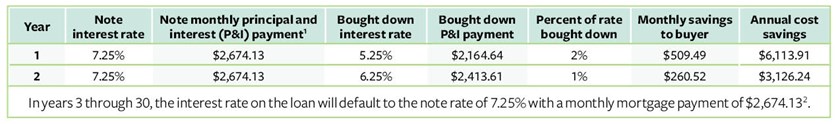
    Securing a home mortgage with a 2-1 buydown will enable for the curiosity payment to be diminished in the middle of the first 20 years of the private mortgage time period proper earlier than climbing to the lasting quantity, additionally acknowledged because the discover value, in calendar yr 3. The fascination degree is regularly diminished by 2% within the 1st yr, adopted by 1% within the 2nd 12 months.

    2-1 buydown illustration

    Here’s a 2-1 buydown instance for a 30-calendar yr fixed-fee mortgage phrase wherever the small print value $9,240.15:

    2-1 Buydown Chart

    Potential benefits of a 2-1 vendor-paid buydown

    Now that we now have coated some buydown necessities and reviewed an living proof, let’s simply take a more in-depth appear at how a 2-1 vendor-paid buydown could possibly be useful in a genuine property transaction proper now.

    For potential consumers, a 2-1 vendor-compensated buydown helps them ease into homeownership. First common funds are under their everlasting month-to-month fee, making the home mortgage cheaper upfront. And in consequence, they spend considerably much less curiosity across the way of life of the private mortgage, versus a mortgage devoid of a buydown that has the precise take be aware fascination payment and principal. A 2-1 seller-paid out buydown is often a risk-free method customers can make the most of shortly securing a cut back need payment and common month-to-month fee in a climbing degree setting.

    Sellers might revenue from a 2-1 buydown, a lot too. Presenting one on their dwelling itemizing could probably make it way more eye-catching to purchasers and assist it stand out in direction of different listings, primarily when need payment hikes are a reality. Or, if a purchaser requests for a vendor to produce only one and the seller accommodates the request, the shopper could possibly be way more very more likely to put money into the house. Numerous households are sitting on the sector for an extended time period of time, and a 2-1 vendor-paid out buydown could also be a unbelievable house-promoting method.

    Total, a 2-1 vendor-paid out buydown could possibly be a gain-earn for each equally homebuyers and property sellers. If you’re concerned about discovering way more about getting advantage of this robust instrument, join with an Evergreen monetary mortgage officer at the moment. We additionally give 1- and 3-2-1 buydowns. One explicit of our dwelling mortgage specialists can assist make clear the ins-and-outs so that you’re perfectly-informed and established up for good outcomes in your homeownership journey.

    Prices are as of 10/19/2022 and matter to change with out uncover, certain conditions apply. Not all customers will qualify for the phrases talked about. 1. Regular fee is principal and curiosity (P&I) solely, based mostly totally on order fee of $490,000 with a mortgage amount of cash of $392,000, 7.25% fastened degree, 30-yr expression, APR 7.551%, and 20% down fee. 2. Payment doesn’t embody taxes and insurance coverage coverage premiums. The exact fee quantity will likely be elevated. Some situation and county most financial institution mortgage quantity limitations may make the most of. The fee state of affairs is for instance capabilities solely. Talk to for current charges. Not all merchandise and options provided. Application is matter to enhance.

    &#13

  • Amazon, Mphasis workforce up to grow gen AI in lending and finance

    Mphasis introduced a collaboration with Amazon World-wide-web Companies to focus on enlargement of the know-how agency’s devoted AI enterprise, with concepts to broaden each of these its obtain and capabilities. 

    The New York-centered company and dad or mum to home mortgage technological innovation consultancy Digital Chance expects to faucet into AWS to set up its possess generative AI unit “as a dynamic platform for modeling enterprise use situations and buying proof of ideas.” Anticipating to higher help monetary companies features, which embrace dwelling lending, Mphasis reported it applications to simply take fringe of the multiyear settlement to afterward broaden into different industries.  

    “The Gen AI Foundry for Monetary Companies, led by Mphasis.AI, is our motivation to accelerating AI adoption and group modernization for our purchasers,” reported Mphasis CEO and dealing with director Nitin Rakesh in a press launch. 

    Greater utilization of generative AI and tools mastering functions stand to significantly strengthen info extraction and analysis, as completely as call-center interactions. In the fast foreseeable future, Gen AI Foundry goals to expedite sensible doc processing for brand spanking new monetary establishment accounts and house loans, as properly as in insurance coverage coverage guarantees processing and fraud investigation.  

    The technology of the foundry additionally will come on the heels of comparable AI-dependent merchandise rollouts this calendar 12 months exactly focusing on house mortgage corporations, along with an analytics module from Paradatec. 

    “Clients have suggested us they’re investing in their possess capabilities or third-social gathering models to automate advanced workflows,” defined Neil Fraser, the corporate’s director of U.S. operations, at merchandise launch, including that companies turned to corporations like Paradatec for help in pinpointing and cleaning data. 

    Extra not too way back, Rocket Mortgage mortgage unveiled its AI-dependent underwriting machine that it statements can pull essential details from borrower paperwork. 

    At the very same time, different mortgage corporations have jumped on the bandwagon with several types of AI-driven corporations, which incorporates A&D Mortgage, which launched a system for dealer companions. Newrez additionally entered into its personal partnership with Microsoft on the cease of final 12 months to enhance borrower engagement. 

    Mphasis will supply small enterprise shoppers potentialities to watch demos and check out proof of thought conditions in digital message boards at its data heart or at a AWS enterprise website, equally in New York Metropolis.   

    “AWS is delighted to collaborate with Mphasis to help the introduction of the Gen AI Foundry for the monetary knowledgeable companies sector. Mphasis’ expertise in AWS corporations and AI/ML capabilities, combined with their dedication to marketplace-specific cures, aligns seamlessly with our mission to allow buyer innovation with cloud computing,” talked about Scott Mullins, managing director and regular supervisor, AWS All over the world Economic Companies.

    Electronic Chance was initially launched in 2005 to help originators navigate due-diligence procedures. Mphasis, a world broad know-how options supplier, afterward acquired the corporate in 2013. 

  • What it means for customers and sellers


    Andrew Caballero-Reynolds | AFP | Getty Pictures

    The price at which residence worth ranges develop is slowing down.

    U.S. family prices amplified .6% from a month proper earlier than in February, in keeping with the .6% regular common month-to-month obtain within the round 8 a few years main as much as the Covid-19 pandemic, in accordance to a brand new Redfin investigation.

    Just earlier than the pandemic, it was extraordinary for charges to extend about fifty p.c a p.c every and each month, or to maximise all-around 5% or 6% per yr, mentioned Daryl Fairweather, the principle economist at Redfin.

    “We’re once more to that sample, even with these larger dwelling finance mortgage prices,” she talked about.

    More from Personalized Finance:
    What a $418 million settlement on residence-sale commissions might maybe indicate for you
    In 2023, listings on this time physique offered for $7,700 extra, evaluation finds
    What to learn about a couple of condominium and a co-op condominium

    A comparable growth appeared in Moody’s Analytics Household Price tag Index, defined Matthew Walsh, assistant director and economist at Moody’s Analytics.

    “Dwelling prices are appreciating on the similar tempo as upfront of,” he acknowledged. “It’s returned to the development that we noticed pre-pandemic.”

    Having mentioned that, the market at the moment is vastly distinctive from the sector two to eight many years again, authorities say. The widespread home is nonetheless unaffordable for most possible customers when stock has marginally enhanced however not ample to satisfy up with demand from customers.

    “The sentiment we’re acquiring from our brokers is that neither sellers nor potential consumers are happy with this present market,” Fairweather defined. “Sellers are dissatisfied … with provides that they are receiving. And customers are dissatisfied in hovering costs and climbing mortgage costs.”

    Stages of transactions are at ‘recessionary lows’ 

    Even although the housing present market has stabilized by way of promoting worth growth, a major variance regarding the sector these days and the pre-pandemic time frame is the comparatively very low variety of transactions, which is generally because of vital mortgage prices, defined Fairweather. Property finance mortgage prices peaked at virtually 8% previous 12 months, however are nonetheless in extra of 6%, in line with Freddie Mac info.

    In easy truth, the stage of transactions are at “recessionary lows” regardless of “a pop within the particulars in February,” Walsh mentioned.

    An extra issue impacting product gross sales is the very confined present of homes, he further.

    New listings climbed 5% for the period of the ultimate 4 months ended March 17, the foremost year-over-yr soar on condition that May probably 2023, Redfin uncovered. But “it is sort of a tiny restoration from a all-time low,” talked about Fairweather.

    “We’re not again to the place we ended up pre-pandemic,” she claimed.

    Supply growth is basically tied to a seasonal growth, economists say. Homeowners usually listing their households for sale in February primarily as a result of they favor to shift within the spring and summertime, Walsh claimed.

    And sometimes, lifetime happens. “Another issue is simply males and ladies needing to switch for probably a brand new profession or they’re having married, or there may be actually another vital lifetime get together,” Fairweather talked about.

    The payment lock-in impact is loosening its grip

    The home mortgage degree lock-in affect, additionally acknowledged because the golden handcuff affect, saved homeowners with extremely decreased dwelling finance mortgage charges from itemizing their households final yr: They didn’t need to finance a brand new dwelling at a significantly larger curiosity worth. Now, that’s loosening its grip available on the market place and barely boosting on the market supply, economists say.

    “It was certainly preserving people in location, however the extra time that passes, the less strong that affect will get,” Fairweather mentioned.

    Some potential consumers who skilled postpone itemizing their households “are coming to phrases with larger property finance mortgage charges,” since they arrive to really feel they’ll no prolonged postpone the go, Walsh outlined.

    Even although the quantity lock-in impact remains to be having fun with a operate in immediately’s minimal stock, it will fade extra round time, significantly because the Federal Reserve decides to attenuate charges in a while this calendar yr, Fairweather mentioned.

    House mortgage costs are additionally forecast to modestly decline this yr because the Fed trims fascination premiums, though home prices are possible to maintain on being flat or unchanged nationally, Walsh talked about.

    Homebuilder sentiment turns positive for the first time since July

    New builds are barely strengthening

    New-dwelling income are managing on the massive conclusion of the assortment observed pre-pandemic, averaging about 600,000 for every month, Walsh talked about. There had been 661,000 new households marketed in January, 1.5% further than in December, in accordance to the U.S. Census Bureau.

    Potential consumers irritated with the restricted present of current properties, are giving a elevate to the new-house present market. “Builders are actually benefiting from that,” he mentioned.

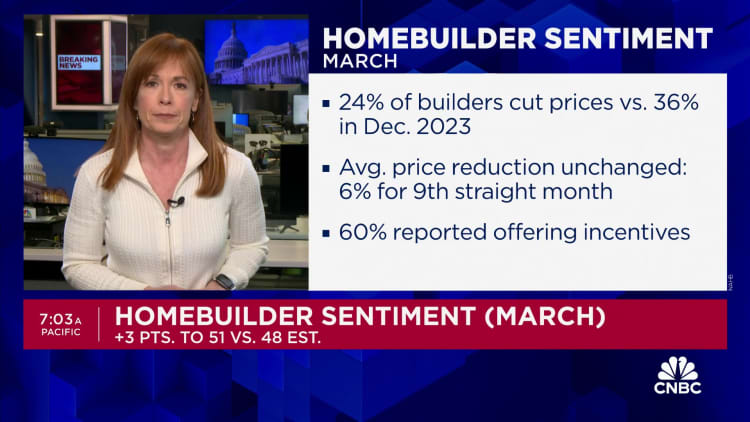
    Homebuilders may provide customers incentives that property homeowners may not, this sort of as mortgage price buydowns or price ticket cuts, Walsh extra.

    However, the rise is just not ample to bolster the acute housing present all through the nation. “It actually is heading to take us a while to make up for that hole, even though they’re creating greater than earlier than,” he mentioned.

    Don’t cross up these exclusives from CNBC Professional