Tag: and

  • Technology has allowed the home loan process to be easier and more convenient to you

    U.S. mortgage holders submit file ranges of home fairness: ICE

    By Didier Malagies
    •
    15 May, 2024

    U.S. home costs continued to climb in March as a persistent scarcity of houses on the market helped to buoy the housing market, in accordance to the Intercontinental Exchange (ICE) Home Price Index. And whereas potential homebuyers address the challenges of rising housing unaffordability, present householders are reaping the advantages of traditionally sturdy worth features. Nationwide fairness on mortgaged houses soared to a file $16.9 trillion in the first quarter of 2024, with $11 trillion out there for leverage whereas sustaining a 20% fairness cushion — additionally an all-time excessive. The ICE index confirmed that home costs elevated by a seasonally adjusted 0.42% month over month in March, marking the third consecutive month of above-average worth features, though this was a slight pullback from February’s 0.58% improve. On an annual foundation, home worth progress eased barely in March to 5.6%, beneath the upwardly revised achieve of 6% in February. “The current pattern of rising rates of interest has dampened homebuyer demand and allowed the stock of houses on the market to enhance,” Andy Walden, ICE’s vp of enterprise analysis technique, mentioned in an announcement.  “We’re nonetheless very a lot in a gap from a list perspective, however that deficit has fallen from 50% a yr in the past to 38% in March. Today, with 3.3 months of provide, stock continues to be traditionally low and indicative of a vendor’s market. This helps to preserve home worth progress resilient despite the fact that

  • Luxury Housing Market Inspired “Total Frenzy” in Vacation-Homes Boom Towns Like Aspen, Palm Beach and Lake Tahoe

    Luxury Housing Market Inspires “Total Frenzy” IN Vacation-Home Boom Towns like Aspen, Palm Beach and Lake Tahoe


    Written by: Julia Falcon

      During this time when individuals are hunkering down with their households in cramped properties, an expansive trip property appears extra preferrred than ever, particularly in mountain cities like Aspen, Colorado and Jackson Hole, Wyoming.

    After seeing vital drops in April and May, the luxurious market has rebounded in locations which are often standard for second properties. But it’s not simply single-family properties with extra sq. footage getting the love – brokers say they’re getting inquiries for condominium leases, too.

    In an interview with HousingWire, Sara Roberts, vp of promoting at Slifer Smith & Frampton Real Estate in Vail Valley, Colorado, stated that general, it’s this market’s busiest time of the yr.

    Like the remainder of the nation, open homes in Vail shut down in April and May, squeezing an already compressed shopping for season for the holiday space.

    “It is simply so uncommon. Summertime is often our busiest season, however that is completely different. Because we’re a seasonal resort we often have a busy summer season season and we’ll pull again in the autumn and then after all choose up once more in the ski season,” Roberts stated.

    “We’re not seeing that dip but,” Roberts stated. “By now, in August, we’d see folks leaving city and it’s going to be calming down, however we haven’t hit the height but. So it’s sort of loopy, it’s simply it’s been very, very, very busy.”

    Roberts stated that the Vail market brings in folks not solely from different components of Colorado, however from everywhere in the nation, together with folks from Texas on the lookout for an escape.

    Another pattern Roberts stated she was seeing was second properties changing into the brand new main house, and even consumers transferring up from smaller trip properties.

    “Maybe they’d a condominium right here and they might slightly now have a single household as a result of they need to spend extra time right here,” Roberts stated. “We’re seeing a number of visitors in the luxurious excessive finish market, the one household properties that often take a bit longer to promote appear to be the extra standard purchases taking place proper now. I believe the little two-bedroom condominium that you just use one or two weeks out of the yr is ok if you’re not residing in it full time, however now, folks need to come and keep longer in order that they’re on the lookout for these house places of work, more room, much less shared widespread space.”

    Year up to now by May, the Vail market was down 25% in closed gross sales quantity, however rebounded by July, closing that hole to 9.5% down over 2019 YTD totals.

    Roberts stated she expects to see a busy August and September, persevering with to shut that hole and possibly even surpassing 2019 totals for closed sale quantity.

    “It’s simply loopy to assume all these second properties that often stayed empty for a superb quantity of the yr are actually being occupied full time,” Roberts stated.

    Kelli Bennett, a RE/MAX Realtor who leads the Kelli Sells staff in Summit County, Colorado, stated the market this summer season was “unreal.” Summit County consists of ski resort cities Breckenridge and Keystone, and the curiosity in the world has saved everybody concerned in the actual property transaction very busy. Title brokers are booked as much as six weeks out, Bennett stated.

    “July showings in Summit County have been up 92% over final yr, so consumers need to go in robust and quick,” Bennett stated. “If consumers don’t have time to come back up right here, they should Facetime with their Realtor and get it off the market earlier than one other purchaser will get it.”

    Further north, in Jackson Hole, Wyoming, Latham Jenkins, an affiliate dealer at Live Water Jackson Hole, stated that “COVID-19 refugees” started flocking to this trip city in May. Jenkins stated not solely is the Jackson Hole buy market flourishing, however its rental market is off the charts, too.

    “Single-family properties with somewhat little bit of acreage round them [are in demand],” Jenkins stated. “We have seen in the $3 million plus phase, actually a record-breaking tempo during the last two months of pending listings.”

    As extra folks than ever are working from house, Jenkins stated that extra individuals are retreating to larger and extra relaxed life, which is what Jackson Hole has to supply. This additionally results in extra bidding wars.

    That mirrors a current Redfin report that discovered 46% of properties listed above $1.5 million obtained a number of bids in July.

    “Buyers name me up and say ‘I’ve been quarantined in my condominium in Manhattan now for 75 days,’” Jenkins stated. “So it’s fascinating you don’t really feel the consequences in these way of life markets such as you do in the dense city settings.”

    Another issue in this pattern is that many colleges are going digital on account of COVID-19. With telecommuting to work and now faculty, householders and college students might be wherever and nonetheless get their work performed.

    “I imagine pricing stress will come in as extra stock will get absorbed — our stock has been quickly absorbed to the purpose that almost all of my colleagues and I concern that in the months to come back,” Jenkins stated. “The purchaser demand will proceed, however the stock ranges shall be at historic lows.”

    Mountain cities appear notably standard proper now, as luxurious markets in extra coastal areas like South Florida aren’t seeing the identical escalation. A current article in the Miami Herald stated that the South Florida luxurious housing market suffered in the second quarter, because the variety of gross sales dropped as much as 55.6% yr over yr in one neighborhood, for instance.

    “It goes with out saying that transferring has been extra focused in the luxurious phase of the market, as these consumers have the means to maneuver into these way of life markets, and additionally dovetails with the need to reside in experiential markets,” Jenkins stated.


  • Mortgage forbearance is down 2 basis points to 5.9%, led my fnma and fhmc

    The U.S. forbearance charge measuring the share of mortgages with suspended funds fell barely to 5.9% final week, in accordance to the Mortgage Bankers Association.

    Though the speed fell 2 basis points, the decline has begun to gradual after two weeks of what MBA’s chief economist Mike Fratantoni referred to as “a flurry of debtors” exiting as they reached the six-month mark.

    The decline was largely pushed by a 5-basis-point drop in Fannie Mae and Freddie Mac loans that knocked the GSEs’ charge of forbearance down to 3.72% – the twentieth consecutive week the enterprises’ charge has fallen.

    However, the GSEs’ drop was offset by the speed for Ginnie Mae loans, which embrace loans backed by the Federal Housing (*2*), rising 3 basis points to 8.17%, and the forbearance share for portfolio loans and private-label securities (PLS) growing by 4 basis points to 8.90%.

    “There continues to be a gentle enchancment for Fannie Mae and Freddie Mac loans, however the forbearance share for Ginnie Mae, portfolio, and PLS loans all elevated. This is additional proof of the unevenness within the present financial restoration,” Fratantoni stated. “The housing market is booming, as proven by the extraordinarily sturdy tempo of dwelling gross sales final week. However, many owners proceed to battle, because the tempo of the job market’s enchancment has waned.”

    The Three Cs of Post-Forbearance

    Here is how to assist with questions that so many owners will probably be asking quickly.

    Presented by: Freddie Mac

    In a latest bid for stability, the FHA prolonged its preliminary forbearance request for single-family householders by means of Dec. 31. The Federal Housing Finance Agency adopted swimsuit, saying it will proceed to purchase certified loans in forbearance by means of Nov. 3.

    According to the MBA report, an estimated 3 million householders are in forbearance plans, with roughly 25.02% of complete loans in forbearance within the preliminary stage and 73.14% in a forbearance extension. The remaining 1.84% are forbearance re-entries, the MBA stated.


    The quantity of calls from mortgage debtors to the servicers dealing with their dwelling loans elevated final week to 8.9%, measured as a share of general servicing portfolio, from 8.2% within the prior week, the MBA report stated.

  • Australian organizations more and more convert to rescue courses

    “It’s evident that out of requirement, an rising number of companies are discovering the added advantages of Australia’s firm rescue choices. We have a number of the most useful laws within the setting: it’s each equally speedy and commercially concentrated, but it surely shouldn’t be a previous-minute or enforced conclusion.” 

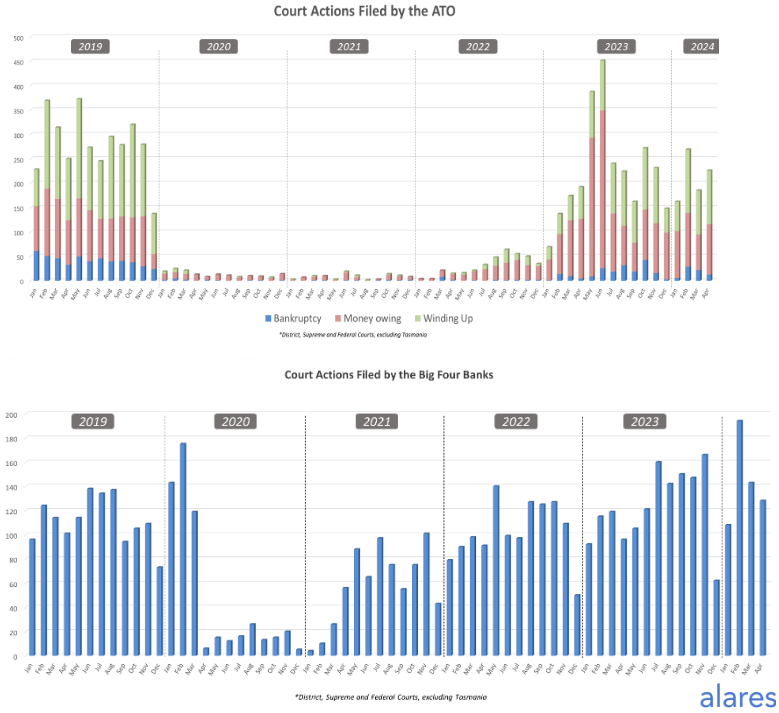
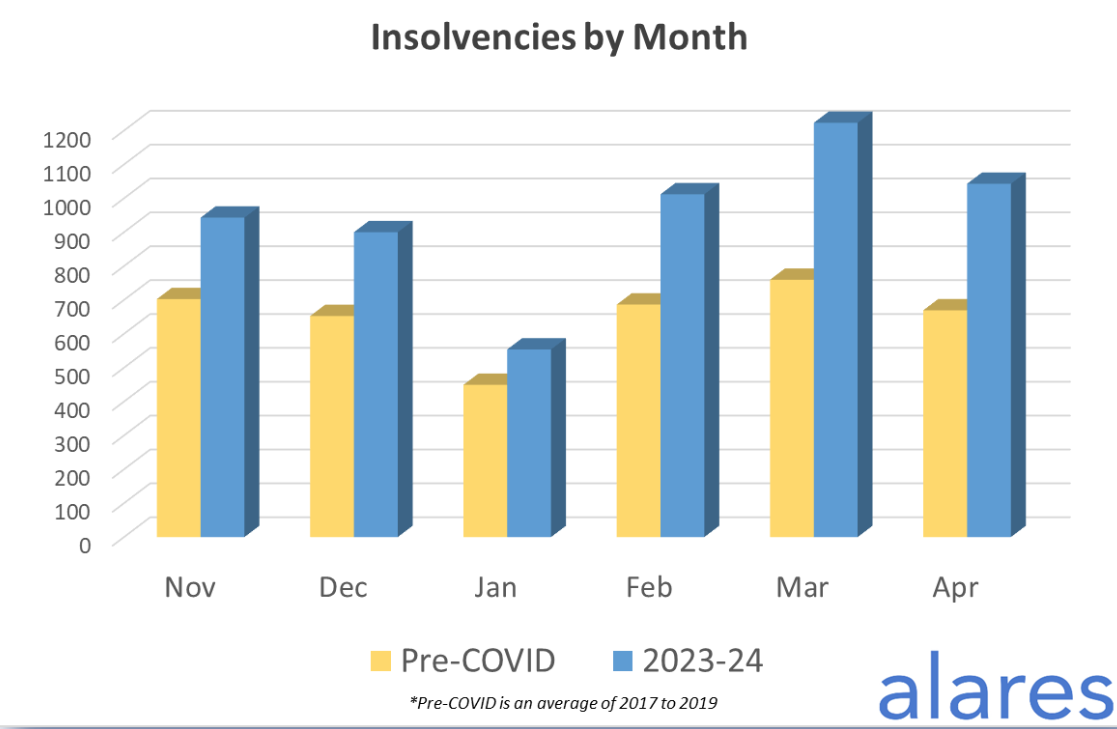
    The urgency is underscored by data from the Alares Monthly Credit Possibility Insights, which indicated that in April, SBRs constructed up about 14% of all insolvency appointments, with VAs shut powering. Court liquidations accounted for additional than 19%, pushed by energetic restoration makes an attempt by the ATO and vigilance from necessary banks.

    “As the ATO proceeds to function because of the file quantity of outstanding tax monetary debt, it’s considerably driving tiny enterprises into SBRs and bigger organizations into Voluntary Administrations,” defined Patrick Schweizer, author of Alares Month-to-month Credit ranking Chance Insights. “Our April report demonstrates that insolvencies remained 50% earlier talked about pre-pandemic ranges, reinforcing the lengthy anticipated catch up in insolvencies from the pandemic lows.”

  • Amy Donnelly joins Atom as BDM for Scotland and NI – Mortgage loan Finance Gazette

    Atom Bank has appointed Amy Donnelly as enterprise enchancment supervisor (BDM) for Scotland and Northern Ireland.

    Untitled-design-30.jpg

    Donnelly joins from Dunkeld House loan Property wherever she served as a home loan dealer.

    Beforehand, she has labored on the Lender of Scotland and doing the job for Halifax Intermediaries in a BDM place.

    In her new perform, Donnelly will probably be accountable for strengthening already-fashioned relationships with brokers in Scotland and Northern Eire and introducing new brokers to the lender.

    She will report back to Atom’s regional group enchancment supervisor Alex Hart.

    Commenting on her new position, Donnelly claims: “I’m completely delighted to be turning into a member of the group, and seem ahead to creating relationships with brokers in my space.”

    Hart provides: “Amy is a improbable addition to our BDM workforce, bringing each substantial sensible expertise and insights from her the most recent carry out as an adviser.”

  • self utilized having harder, extra disclosures and fh loan limits

    Initially-time home potential patrons require to know that that is obtainable

    By Didier Malagies
    •
    09 May, 2024

    An individual methodology that’s provided for very first-time home clients is precisely the place you possibly can set 1% down and the lender will provide you with the opposite 2% to a down fee. A complete of a 3% down on your own home. If you bought a 300,000 dwelling you’d put 3,000 down and when you purchased the seller to pay 3% of closing charges, you simply purchased a property for $3,000. What wouldn’t it worth to switch into yet one more rental? To begin with, Very final, and deposit? Now for the upcoming methodology. based mostly on wherever you reside, you would stand up to $5,250 for a down fee or closing charges. That is substantial and with the vendor shelling out closing charges, Now you possibly can see how the alternate options of receiving right into a property No liens, second mortgages, or something in any respect. This is an efficient prospect to not should do down fee steerage with a second lien out of your family with specified limitations there aren’t any constraints with the 1% down or as much as $5,250 to down fee or closing charges Be certain to allow me know the way I can allow you tune in and uncover at https://www.ddamortgage.com/weblog Didier Malagies nmls#212566 DDA Mortgage nmls#324329

  • Flood insurance policies and what you will need to know?

    Initial-time house potential patrons have to have to know that that is available

    By Didier Malagies
    •
    09 May presumably, 2024

    An individual software program that’s obtainable for very first-time property clients is strictly the place you can put 1% down and the monetary establishment will give you the opposite 2% towards a down fee. A total of a 3% down on your house. If you acquired a 300,000 dwelling you would put 3,000 down and if you acquired the seller to pay again 3% of closing bills, you simply bought a house for $3,000. What would it not expense to go into one other rental? To begin with, Final, and deposit? Now for the upcoming system. depending on the place you reside, you may stand up to $5,250 for a down fee or closing prices. That is very large and with the seller having to pay closing expenditures, Now you can see how the choices of buying right into a dwelling No liens, subsequent house loans, or something in any respect. This is a good prospect not to have to do down fee assist with a subsequent lien in direction of your dwelling with specific restrictions there are not any limitations with the 1% down or up to $5,250 in course of down fee or closing prices You ought to allow me understand how I can help you tune in and perceive at https://www.ddamortgage.com/weblog Didier Malagies nmls#212566 DDA Property finance mortgage nmls#324329

  • This Is Why Better Fascination Charges Are Fantastic For Homebuyers And Terrible For Sellers

    This Is Why Greater Fascination Charges Are Superior For Homebuyers And Bad For Sellers.

    You know a better curiosity worth often means a bigger fascination cost. That is a offered. Even so, as a shopper, elevated fascination prices do just a few points. They push consumers out of the housing present market, they stabilize family promoting costs, and so they push uneducated potential consumers out of the present market. And for sellers bigger need charges shift the trade absent from a vendor’s market again to a purchaser’s market place. 

    Here’s how.

    Why do merchants depart the housing sector with elevated fascination prices?

    The response is that the larger fascination prices end in a reduce in rents and return. An monetary funding property is rather like a enterprise it necessities to make enough income to incorporate costs, which incorporates upkeep bills, servicing service charges, and of system taxes. As fascination prices go up traders might want to demand extra lease per thirty day interval to handle charges. This implies that the over-all return on funding resolution decreases.

    Why do home charges stabilize with higher need prices?

    Lots of people right this moment are mystified once I inform them that curiosity charges have to extend earlier than housing charges can drop. They really feel the worth a buyer will pay for is a performance of his money circulate. So if incomes are falling, how can the associated fee he will pay again proceed to be the exact same?

    Higher curiosity premiums make it attainable for purchasers to qualify for extra households for the same month to month cost.

    A $200,000 dwelling at a 6% fastened-price house finance mortgage has a each month cost of $1458. A $200,000 family at a 6% adjustable-price home mortgage has a cost of $1453. That is $5 fewer on a month-to-month foundation, even whereas the customer’s income is 20% decrease. He can due to this fact manage to pay for a extra expensive dwelling.

    The bigger rates of interest create room for elevated bidding by clients. The greater charges additionally minimize down the motivation to develop to be an dealer buyer traders bid up costs towards would-be residence customers. Larger fascination charges, due to this fact, decrease competitors from merchants and make it attainable for more room for non dealer customers to outbid each different. Prospective consumers will pay for further costly residences and contend for them. The result’s that costs proceed to be concerning the an identical at the same time as incomes drop.

    Why do uneducated homebuyers go away the housing present market?

    This may be very uncomplicated. Potential consumers who actually do not need to “spend extra money” go away when the fascination costs go up. The reality is larger need prices by no means hurt the purchaser as outlined above, they stabilize and even reduce dwelling prices. Even higher for the potential consumers who preserve within the present market, the uneducated consumers leaving much more cuts down ranges of competitors in demand.

    You no extra time should compete with 20 bids for a property that doesn’t meet your loved ones’s have to-haves, needs, and desires. You could have the freedom to look at quite a lot of homes, weigh the execs and downsides, and bid at or beneath the inquiring price ticket. And which is the great thing about bigger need charges… normalcy within the housing market.

    So, if you wish to know your buying electrical energy at 3.5%, 4.5%, and even 5.5% give me a get in contact with at 727-543-1753. I can higher totally grasp your desires, necessities, and have to-haves. Alongside each other, we’ll develop a getting strategy that may contend regardless of charges and competitors.

    To grasp further about me, Dottie Spitaleri, check out
    https://www.ddamortgage.com/dottie.

  • Service fees & Questionnaires How Condos Are Distinctive and How to Tell What You Are Getting

    There is a major change in financing a SFR (one partner and kids dwelling), Condo and a PUD (Prepared Device Enhancement) and it is important that you’re educated upfront!

    A Solitary-Family members Residence (SFR) is meant for the use and occupancy of a solitary-household. They are Payment Straightforward Estates which is the most important want only one can have in precise residence. A Prepared Device Enhancement (PUD) can be a Rate-Very easy Estate like an SFR. Most have an curiosity in in style location(s) and facilities these as clubhouse, pool, entranceway, etcetera., and are part of a householders’ affiliation. 

    You pay out HOA dues to allow retain up the facilities. HOA’s even have what’s considered covenants which might be recorded and submitted with the situation. These format the laws and polices of the event. 

    For illustration, no leisure automobiles parked within the driveway, or no enterprise automobiles allowed on premises in a single day, and so on. A Condominium is genuine belongings property in which there’s an undivided curiosity in widespread in part of genuine belongings along with a special curiosity in space often known as a unit. A condominium proprietor shares possession along with different machine house owners as described by their “Condominium Plan”. It normally is made up of “airspace” within the partitions of their unit. This number of possession doesn’t generally include the true development. Financing will fluctuate for each belongings variety, significantly for condominiums. 

    Right right here is why. 

    When you get a condominium, you buy the inside machine. The exterior of the residence, in addition to all frequent locations, are shared amongst all rental proprietors within the progress. Condominiums should fulfill the subsequent wants at a minimal related to their possession and governance to be warrantable. No solitary entity owns extra than 10% of the fashions in a job, which embrace the developer, at the very least 51% of the models are proprietor-occupied, Less than 15% of the fashions are in arrears with their affiliation dues, there is no such thing as a litigation during which the home-owner’s affiliation (HOA) is called, Professional home accounts is 25 % or considerably much less of the entire making sq. footage. 

    To recap:


    No solitary entity owns much more than 10%At the very least 51% of the fashions are proprietor-occupiedFewer than 15% of the fashions are in arrears with their affiliation duesNo litigation during which the home-owner’s affiliation (HOA) is namedCommercial home accounts is 25 % or much less of the SQ FT

    With condos, you’ve to recall, it’s not simply your creditworthiness the monetary establishment has to be involved about. They even have to get anxious in regards to the fiscal and bodily well being and health of the general growth into which you might be searching for.

    Non-warrantable rental funding is unavailable through Fannie Mae, Freddie Mac, FHA, and VA so you should have to have to get along with your mortgage mortgage specialist to additional extra discuss different financing potentialities. Or give me a contact, (727) 543-1753. I might be content material to talk about your picks.

    How do I do know if the condominium is warrantable or not?

    The lender can have to mail a form referred to as a “rental questionnaire” to the condominium affiliation or administration enterprise. The questionnaire permits the monetary establishment to establish if the rental meets its specs for a private mortgage. If the wants are fulfilled, the mortgage firm can in flip ponder supplying a mortgage to the condominium buyer. 

    There are additional prices required for condominium financing. Each particular person condominium administration company costs expenses for finishing this selection and the service fees can range from affiliation to affiliation. They can vary from $150 – $800 typically rather more. These bills are non-refundable and will will want to be compensated in complete prior to the kind staying completed. There is an extra value that can be gathered by the title company at closing for the “Estoppel Letter”. This value is normally $150-$250. 

    These letters are ordinarily requested by title insurance coverage insurance policies suppliers when a tool is closing to assure that every one assessments are paid out up and to prorate evaluation contributions amongst a buyer and vendor identical to is carried out with taxes. If the title company doesn’t confirm the number of assessments that may be thanks, the brand new proprietor will turn out to be answerable for all previous assessments and might then make a assert in opposition to the title insurance coverage plan company for contribution. Not solely are there added fees however the premiums are normally larger for this sort of financial institution mortgage as completely as some mortgage firms could probably contain a bigger sized down fee particularly if it’s a subsequent dwelling or expenditure belongings. 

    It is right apply should you get with your property mortgage expert on the time of pre-qualification to make assured that you’re wholly conscious of what’s required and what you may assume via the lending system. 

    If you by no means have a dealer or mortgage firm to talk about to, give me a telephone
    (727) 543-1753.

    To study extra about me, Dottie Spitaleri, pay a go to to
    https://www.ddamortgage.com/dottie.

  • Why is your home finance loan payment heading up, 2022 taxes, HOAs, and insurance plan?

    Fed holds premiums common for the sixth straight time

    By Didier Malagies
    •
    02 May maybe, 2024

    The Federal Reserve ’s Federal Open up Markets Committee (FOMC) maintained its shorter-expression protection want payment fixed at quite a lot of 5.25% to five.5% for a sixth consecutive convention on Wednesday. “The Committee doesn’t count on will probably be appropriate to lower the goal fluctuate proper up till it has gained higher assurance that inflation is relocating sustainably towards 2%,“ the FOMC acknowledged in a assertion. “In addition, the Committee will carry on reducing its holdings of Treasury securities and firm monetary debt and company mortgage‑backed securities.“ In the course of their final assembly in March , policymakers indicated that they even now envisioned three fascination cost cuts in 2024. But with inflation remaining sticky and unemployment remaining underneath 4%, these expectations are turning into much less possible. Modern financial information hasn’t supplied the Fed assurance that inflation will go on to say no. Robust inflation data within the initially quarter, coupled with a sturdy labor trade , have postponed anticipations for the primary Fed value reduce. In April, Fed Chairman Jerome Powell, talking on the Washington Forum , designed it clear that cost cuts had been being not imminent as a result of energy of the monetary state. The financial system has maintained stunning momentum regardless of the most recent quantity of limited-term costs. With the unemployment payment beneath 4%, companies are steadily introducing workers and critical wage progress is observable as inflation eases. Although upward actions in inflation are noteworthy, considerable improvement in the direction of the Fed’s 2% consider has been made. “It’s unlikely that the long run plan cost switch can be a hike,” Powell instructed journalists on Wednesday all through the FOMC’s push assembly. “In get to hike the prices, we would want to must see persuasive proof that our coverage stance is not adequately restrictive to carry inflation sustainably right down to 2% above time. That is not what we’re in the meanwhile.” Whilst Powell emphasised the unlikelihood of future payment hikes, he additionally remained imprecise concerning the Fed’s future want payment trajectory. “We didn’t see improvement within the to begin with quarter. It seems that it’s going to simply take extra time for us to entry that place of confidence,” Powell mentioned. “I don’t understand how intensive it would take into account. … My non-public forecast is that we are going to get began to see improvement on inflation this yr. I don’t know that will probably be ample to decrease fees we must allow the information lead us on that.” In a brand new improvement, the Fed launched an easing of its quantitative tightening protection. Commencing in June, the level-setting system will decrease the roll-off payment of its Treasury securities from $60 billion to $25 billion for every month. This means that while the Fed is not going to begin advertising Treasurys in June, it would make it doable for much less of them to skilled. It is not going to alter its roll-off payment for home finance loan-backed securities (MBS), which is able to carry on being at $35 billion per thirty day interval, in accordance with Xander Snyder, senior business precise property economist at Initially American. “The FOMC didn’t alter the continuing passive roll-off of its MBS holdings however did bear in mind that any prepayments exterior of the persevering with $35 billion cap can be reinvested in Treasuries,” Mike Fratantoni, senior vp and chief economist for the Home loan Bankers Association, reported in a assertion. “We rely on home loan charges to fall later this calendar yr, however not as considerably or as quick as we beforehand had predicted.” In addition, Powell reiterated the Fed’s motivation to carrying forward the Basel III endgame polices in a manner that is reliable to Basel and additionally akin to what the jurisdictions in different nations are executing. Considering the truth that the March FOMC convention, Freddie Mac’s common 30-yr mounted mortgage payment has elevated from 6.74% to 7.17%. In advance of the up coming FOMC assembly on June 12, two supplemental inflation readings are anticipated. “While it is a danger, I by no means think about that we’ll see a lot alter in home loan charges pursuing this Fed meeting, given that the Fed has been ready to allow the details direct at this part within the cycle,” Realtor.com chief economist Danielle Hale mentioned in a press release. “In purchase to see home finance loan prices fall extra noticeably, the Fed would require to see way more proof that inflation is slowing.”  For homebuyers and sellers, this implies that housing affordability will proceed to be a greatest consideration, fairly probably driving family purchases in reasonably priced marketplaces, predominantly within the Midwest and South, in accordance to Hale.