Author: admin

  • House loan underwriting factors to latest loosening standards

    Late 2023 home loan origination info reveals adjustments in borrower traits that might level to a change in the way in which banks are underwriting these monetary loans, in accordance to a brand new Federal Reserve report.  

    Over a two-yr span in between the fourth quarters of 2021 and 2023, the median entrance-finish monetary debt-to-income ratio for brand new originations on the premier banks improved by 5 proportion particulars and now sits on the highest mark in above a decade at 27%, researchers on the Federal Reserve Lender of Philadelphia claimed. In the identical means, private loan-to-benefit ratios rose to 77% from 68% above the precise time frame. 

    Meanwhile, back-conclude DTI, which variables in all different cash owed owed by the borrower, inched up to 38% from 35%. But on the related time, credit score rating scores have remained in shut proximity to their related diploma, with the median of 770 on the conclude of 2023, a fall from 779 three a few years earlier. 

    “Originated mortgages hint at a possible modify within the probability answer of companies,” the scientists wrote. 

    In probably the most demanding lending setting in current background that has been marked by stock shortages and far much less alternate options for aspiring potential patrons, full origination amount fell to $45.2 billion, the least costly stage because the Philadelphia Fed commenced monitoring the information in 2012. The financial institution analyzes numbers from establishments with $100 million or further in consolidated belongings and private loan portfolios of elevated than $5 billion.

    In combination, the improves in DTI and LTV ratios shine the spotlight on affordability issues as homeownership bank card debt consumes a extra substantial share of debtors’ budgets, the report mentioned.

    “Year-conclusion particulars highlighted shifts in large lender underwriting strategies, largely associated to rising housing bills,” the Fed researchers famous. 

    Reflective of the affordability worries, the median loan measurement surged 8.5% from $279,431 in late 2021 to $305,550 on the shut of ultimate 12 months. The comparatively swift enhance in house finance loan quantities mirrors countrywide housing tendencies described universally across the earlier handful of a long time as annual price improvement strike report highs.  

    The Federal Reserve Lender of Atlanta additionally described affordability earlier this yr approaching previous all-time lows, with 40.5% of the median nationwide money stream anticipated to make typical month-to-month funds. 

    Still, at the same time as housing expenses go on to head upward along with want costs, lenders see an current pipeline of doubtless debtors targeting carrying out homeownership, regardless of the concerns provided by latest monetary traits.

    In spite of worries about alternative elevated hazard from higher DTI ratios and property finance loan funds, general borrower misery has confirmed no appreciable the latest spike. But common efficiency totally different all through distinct sorts of loan merchandise and options, with delinquencies of Federal Housing Administration-sponsored house loans climbing up to a two-year substantial cost of just about 11% within the fourth quarter, the House loan Bankers Affiliation not way back recognized. 

    Across the board, though, delinquencies keep nicely beneath pre-pandemic levels, with each the MBA and Philadelphia Fed reporting the amount of past-thanks monetary loans rising solely a bit of bit on a quarterly basis on the finish of 2023. 

  • Trip dwelling co-possession web site Pacaso adds decrease-priced listings

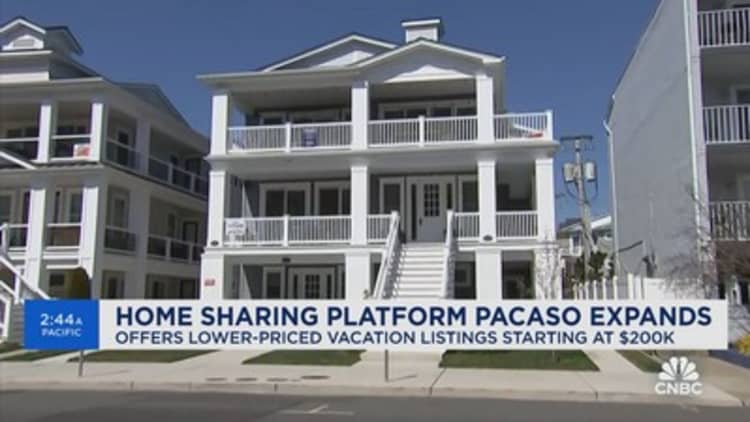
    Pacaso adds lower-priced vacation home listings for co-ownership

    Luxury getaway home co-possession system Pacaso is making an attempt to attraction to the lots, because it grows its enterprise all via a costly and aggressive section of the housing market place.

    The group, which launched in 2020 with multimillion-greenback residences detailed for co-ownership, is now introducing lots of further listings with share prices beginning off as very low as $200,000. Beforehand, shares had been nearer to fifty p.c 1,000,000 kilos, or higher.

    Pacaso lists shares of getaway homes, ceaselessly an eighth however generally extra substantial shares, after which facilitates the purchase, which embody financing if important. It additionally furnishes and manages the family, divvying up the homeowners’ time within the residence by an utility. It can take charges for equally the purchase and the administration.

    “You can handle a big quantity extra home once you spend money on a single eighth or a single quarter of it when in distinction to buying the entire matter, and we’re dwelling in an atmosphere correct now the place by housing affordability is an issue,” claimed Austin Allison, co-founder and CEO of Pacaso. “Property promoting costs are increased, curiosity charges are vital, so it’s actually positively robust for folks in the present day to afford the family of their goals.”

    Not like timeshares in resorts, precisely the place buyers receive the time, not the property, Pacaso householders can benefit from the house’s profit, which generally goes up above time.

    An illustration of Pacaso’s new decreased-priced household trip residence listings.

    CNBC

    “Our homeowners who’ve resold have benefited from about 10% appreciation above and out of doors of what they paid out for the underlying residence earlier. So the Pacaso shares generally hold monitor of with the underlying true property,” reported Allison.

    Wealthier potential patrons have been scooping up ski residences in Colorado and seaside homes in Hawaii, paying lots of of lots of of dollars for his or her shares. Pacaso usually takes a hefty charge — amongst 10% and 15% of the advantage of the property on the entrance cease — associated with aggregating the group of proprietors, facilitating the transaction, and atmosphere up the co-possession framework.

    Pacaso arrived at way over $1 billion in income previous yr, the enterprise defined.

    The company has, nonetheless, considered some backlash from communities that liken it to an Airbnb on steroids. There is even a site dedicated to battling the enterprise, recognized as “Prevent Pacaso Now.”

    Residents of Sonoma, California, handed an ordinance prohibiting Pacaso from functioning in that metropolis. In St. Helena, California, which prohibits timeshares, Pacaso achieved a settlement that guards its 4 properties by now there, however the agency shouldn’t be allowed to broaden to different properties.

    “We function in way over 40 markets nationwide and in solely a handful are we misunderstood,” argued Allison. “Our resolution is to work with policymakers and educate them on the specifics and features. Our perception is that in extra of time this can prevail. It hasn’t labored in Sonoma nonetheless and a smaller handful of communities who’ve handed ordinances to withstand the mannequin.”

    Pacaso can also be together with a brand new suite of providers to assist main homebuyers receive the dwelling-sharing design. About simply one-fifth of most essential homebuyers ultimate yr purchased with both buddy or relative, in accordance to critical property site Zillow.

    “Men and ladies at the moment are working with co-possession as a solution to be outfitted to afford properties that they often wouldn’t be able to afford to pay for. So, it is not simply happening within the trip residence space,” claimed Allison.

    Don’t overlook these exclusives from CNBC Pro

  • 20 Rapid Recommendations for Utilizing Large Gifts and Property for Mortgages

    If you strategy to make use of an inheritance windfall, a considerable asset like a auto or boat, or a considerable sum of {dollars} to help get a home, there are gadgets you could actually know proper earlier than heading on account of the mortgage mortgage system in 2024.

    20 Tips For Making use of Substantial Gifts and Belongings To Buy a Home

    The financial specs of procuring for a house may be irritating, particularly when coping with important sums of income from varied assets.

    No matter whether or not it may be current {dollars}, private monetary financial savings, or surprising arduous money, comprehension find out how to successfully doc these cash is vital for a simple property finance mortgage software program process.

    Below are 20 speedy tips for utilizing massive presents and property to buy a dwelling, nearly each created to help you confidently deal with your funds and fulfill monetary establishment conditions.
    An illustration convey the achievement of homeownership through large gifts and assets

    Gift Income for Your Property

    When acquiring reward earnings for your residence, make sure the donor presents a reward letter stating the wedding, the reward sum of money, and that compensation shouldn’t be predicted. This clarifies the supply of money to lenders, producing your property finance mortgage software program smoother.

    Selling Things to Obtain a House

    If you are providing personalised property to fund your home order, proceed to maintain in depth paperwork of the transaction, along with the merchandise marketed, the sale sum of money, and deposit receipts. This documentation assists collectors hint your useful resource of assets once more to a respectable sale.

    Making use of Your Dollars Stash

    Depositing massive quantities of money may be tough. Deposit it successfully prematurely of implementing for a mortgage and retain a historical past of wherever the arduous money got here from. A letter detailing the supply might presumably even be wanted to meet mortgage supplier inquiries.

    Bonus Money and Your Home mortgage

    A function bonus could be a appreciable increase to your dwelling-acquiring spending funds. Deliver your mortgage supplier with a fork out stub reflecting the bonus and maybe a letter out of your employer confirming it really shouldn’t be a mortgage however a reward.

    Successful Massive: Working with Unanticipated Money

    Unanticipated cash, like lottery winnings or lawful settlements, ought to be documented. A duplicate of the profitable ticket, court docket docket settlement, or lender assertion displaying the deposit can present as adequate proof for mortgage suppliers.

    Cashing Out Investments for Down Payment

    When utilizing investments for your down fee, provide statements demonstrating possession of the property forward of sale and the transaction doc. This aids mortgage suppliers verify the funds are yours to make use of.

    Freelance Earnings and Home Getting

    Freelancers ought to actually protect meticulous financial paperwork. Income deposited into your checking account should match the invoices you may have issued, delivering a really clear earnings path for mortgage suppliers.

    Wedding Presents Towards a House

    Related to different reward funds, doc wedding ceremony ceremony gadgets with letters from the givers, stating the reward’s character and that no compensation is anticipated. Financial establishment statements demonstrating the deposit will even be useful.

    Inheriting Funds for a Dwelling

    Inheritance cash ought to return with documentation, like a will or a letter from the property executor. Lender statements demonstrating the inheritance deposit will even be important.

    Refinancing vs. Buying: The Income Portion

    Have an understanding of that refinancing might maybe have distinct calls for regarding fund documentation. For occasion, assets for enhancements might should have invoices or contracts to current the cash’s use.

    Boosting Property Worth Ahead of Refinancing

    If you is perhaps utilizing specific cash for dwelling enhancements proper earlier than refinancing, proceed to maintain receipts and contracts. These show the developments ended up produced and compensated for, most certainly rising your private home’s worth and refinancing phrases.

    (*20*) Funds Among Accounts

    Usually going {dollars} regarding accounts? Present all account statements to show the transfers’ path. This transparency permits collectors sense safe concerning the useful resource and use of your funds.

    Significant Payments from Purchasers

    For self-used individuals acquiring huge funds, present the contract or bill related to the fee. This establishes the fee’s legitimacy as money stream alternatively than an off-the-cuff mortgage.

    Revenue from Authorized Settlements

    Doc authorized settlements with formal settlement recordsdata and lender statements displaying the deposit. This proof is essential for mortgage firms to confirm the funds are yours and not borrowed.

    Employing Tax Refunds for Your Household

    A simple approach to doc a tax refund is to present the tax return indicating the refund quantity and a financial institution assertion demonstrating the deposit. This may also help mortgage suppliers acknowledge it as actual financial savings.

    Disaster Reduction and Getting a House

    For catastrophe reduction assets, present the official letter or fee notification from the corporate, alongside with lender statements displaying the deposit. This confirms the funds’ origin and legitimacy.

    Revenue in New Accounts

    Newly opened accounts with massive deposits can increase ideas. Offer a obvious clarification and any appropriate documentation exhibiting through which the assets originated.

    Revenue from On the online Profits

    On-line product sales have to be documented with screenshots of the transaction, which embrace specifics of the marketed merchandise and the worth tag. Bank statements corroborating the deposit may steerage your assert.

    Mixing Gifts and Personal financial savings

    When mixing gadgets and personalised monetary financial savings for your down fee, doc each current with a letter from the donor. Assure your price financial savings are traceable to your earnings or different documented assets.

    Working with a Spend Elevate

    A pay again elevate can have an effect on your property finance mortgage software positively. Present the most recent pay stubs as proof of your new money stream stage, along with a letter out of your employer.

    FAQ: Mastering Your House mortgage Prep with Large Deposits and Presents

    How early must I deposit reward income prior to creating use of for a mortgage mortgage?

    Ideally, deposit reward earnings on the very least two to three months previous to beginning your private home mortgage software program to avoid complicating the verification process.

    Can I take advantage of money readily available for my down fee or closing expenditures?

    When it really is doable, cash deposits are extra sturdy to doc. Deposit any funds successfully in progress and hold an in depth historical past or clarification of its provide.

    What if I by no means have receipts for items I provided to fund my buy?

    Make a radical report of the sale, such because the merchandise, the sale day, and the customer’s particulars. A signed month-to-month invoice of sale may function proof.

    Do all current income assets desire a current letter?

    Sure, each single current made use of in direction of your dwelling order must have a corresponding reward letter from the donor, evidently stating the quantity and that it’s not a private mortgage.

    How do collectors have a look at large deposits from freelance get the job carried out?

    Loan firms take a look at them favorably if documented appropriately. Maintain a doc of all contracts, invoices, and corresponding lender deposits to show a dependable earnings provide.

    Are there any types of assets that may’t be used for a mortgage mortgage down fee?

    Yes, cash that may not be adequately documented or confirmed, borrowed funds with out having proper documentation of reimbursement circumstances, and particular varieties of economic loans might maybe not be acceptable.

    How can I doc a fork out increase for my residence finance mortgage software program?

    Deliver your most newest spend stubs displaying the elevated earnings and, if achievable, a letter out of your employer detailing the elevate.

    What actually ought to I do if my checking account exhibits a considerable, unexplained deposit?

    Present a printed clarification and any possible documentation to your lender. If it was a present, a letter from the donor could be demanded.

    Can I take advantage of cash from a brand new mortgage for my down fee?

    Generally, it’s really not advisable to tackle new bank card debt proper earlier than shopping for a dwelling. If you do, you’ll have to disclose this monetary mortgage and current in depth phrases to your mortgage supplier.

    How do catastrophe reduction funds affect my home mortgage software?

    Catastrophe reduction assets are normally seen as a reward and must not negatively impression your software if documented adequately, this form of as displaying the company’s award letter and deposit proof.

    Base Line

    Acquiring ready to get a home requires a considerable amount of methods, particularly when you may have a serious whole of funds from distinctive locations like gadgets or promoting gadgets.

    Sam, like lots of some others, felt confused at preliminary. But with the acceptable particulars, working with large deposits and items could be a clean facet of acquiring your residence.

    Each particular person step, from displaying precisely the place current {dollars} got here from to making use of cash from advertising something, helps you get nearer to proudly proudly owning a property.

    It actually is important to tell your mortgage supplier concerning the place all of your large deposits happen from. This method, they know you might be utterly prepared for a home mortgage.

    This guide provides you concepts and strategies to make assured you’ll be able to show your mortgage supplier every little thing they require to learn about your cash.

    When you totally grasp what to do with huge chunks of earnings, acquiring a residence feels significantly much less terrifying and extra thrilling.

    If you might be looking for assist or have ideas, reaching out to MakeFloridaYourHome is a wonderful subsequent part. We can help make sure you may have all you wish to swap your dream of a brand new residence into fact.

  • APM Economical Conditioning: March 2024

    Previous month noticed the get began of the Lunar New 12 months, which is the 12 months of the Dragon. It actually is an auspicious yr, as it’s believed that younger youngsters born this 12 months are destined for accomplishment. Some well-known Dragon toddlers: Keanu Reeves, Rihanna, Dr. Martin Luther King Jr, John Lennon and Peyton Manning.

    financial fitness march

    No make a distinction what 12 months you have been being born in, you could have some actually critical help shopping for a home this yr should you may be even now leasing! A invoice launched in 2021 might be handed quickly, which would supply a number of initial-time customers with as much as $25,000 in assist. Read via all about this invoice beneath. Other issues: methods to regulate a home remodel, essentially the most up-to-date on automobile insurance coverage plan pricing, and why chances are you’ll maybe need to confirm out your VantageScore.

    Residence Funding

    Down Payment Help Might Get Severe Shortly

    Even nonetheless the 20% down fee rule is not any much more than a fantasy, there are nonetheless loads of potential home purchasers who have to bump up their laborious money belongings upfront of buying their first property. If the Downpayment Towards Fairness Act passes this calendar yr, these initially-time prospects could get hold of a cash grant for as much as $25,000.

    This Act was designed to allow further Individuals purchase their properties and start making a protected cash foreseeable future. Although it actually continues to be within the will work, it was just lately declared that the Act is a part of President Biden’s 2024 Fiscal Yr funds proposal.

    Here are the fundamental ideas of this invoice.

    The Downpayment Toward Fairness Act will ship dwelling possession within the arrive at of further individuals, which incorporates folks with reduce incomes.
    The proposed plan affords as much as $25,000 to initially-time patrons. Initially-era homeowners qualify for $20,000, with $25,000 for potential patrons considered socially or economically disadvantaged. (1st-technology house homeowners are outlined as customers whose mother and father or guardians have by no means owned a dwelling, or customers who previously lived in foster care.)
    Grant funds might be utilised to go over down fee and shutting prices, and for looking for low value elements to decreased a mortgage’s fascination quantity.
    The money funding is shipped to qualifying prospects when a house order is finalized.

    At current, the invoice is nonetheless remaining considered by Congress and is subject material to dialogue and possible alterations previous to it may be permitted and signed into regulation. For updates, pay a go to to the Congress.gov web page showcasing the invoice’s historical past.

    Supply: themortgagereports.com

    Insurance protection

    Automobile Insurance insurance policies Pricing Climbs More than 25%

    If you have just lately been given your automobile insurance coverage renewal discover, you possibly can have felt rear-ended by your new premium. According to new data, drivers all through the nation are having to pay an regular of $212 for vehicle insurance coverage protection, which is above 25% from 2023 premiums.

    When inflation is nonetheless having fun with an element in rising value ranges, different elements are driving up driving charges. A single essential indicator: the place you reside. If you occur to be in some extent out inclined to regular disasters, your charges have been being most completely impacted. For living proof, California drivers noticed their insurance coverage prices head north due to newest abuses meted out by Mother Character, as purely pure disasters harm autos and repairs are getting much more expensive.

    Other states’ motorists often aren’t off the hook. Louisiana and Florida drivers are weathering far more than hurricanes across the earlier couple of a very long time, they’ve been forking over the most important share of their paychecks in the direction of automobile insurance coverage. Louisiana drivers shell out an typical of 6.53% of their earnings for auto insurance coverage though Florida drivers are tailgating them and spending 5.69%. Missouri gained the prize for the premier 12 months-more than-yr enhance in premiums, with drivers paying throughout 40% far more to make sure their rides than they did earlier yr.

    A handful of states’ drivers aren’t struggling as terribly. For occasion, Massachusetts drivers admire a few of the nation’s most cost-effective charges, as level out regulation prohibits the usage of age as a rating facet for surroundings insurance coverage insurance policies pricing. They are paying out simply 1.76% of their earnings in the direction of insuring their cars. Wyoming drivers have been the one situation through which protection costs fell, with common prime quality pricing slipping by an individual buck (hey, it actually is much better than little or no!).

    Resource: cbsnews.com

    In the News

    Inflation’s Down however Not Out

    Current data from the U.S. Labor Office built-in an unpredicted rise within the Customer Cost Index (CPI), which performs an enormous job in inflation. January’s CPI posted a 3.1% annual improve —a bigger leap than anticipated—whereas month to month features better as properly.

    Core CPI portions (which don’t include energy and meals fees) rose 3.9% every year previous month, which was the exact same as December. On a daily basis, CPI rose .3% last month instantly after mounting .2% in December. Core CPI rose .4%, up from the .3% purchase the previous thirty day interval.

    Even though over-all price ticket pressures have moderated, relieving some purchasing pressure, discovering inflation completely again to common might be much more difficult than economists anticipated. The inflation slowdown in extra of the earlier 12 months occurred alongside a stable monetary system, bucking predictions that the U.S. financial local weather must expertise a financial downturn to convey down charges. The huge query is no matter whether or not this pattern will go on in 2024.

    When The Federal Reserve hiked curiosity fees many durations in 2023 to rein in inflation, associates of the Reserve at the moment are attempting to establish whether or not or to not provide the decreased curiosity prices predicted for this 12 months. Not way back, Fed officers are hinting that the decrease charges won’t get there as earlier than lengthy as hoped, as they need additional proof that the battle on inflation has been actually gained forward of reducing need fees.

    Source: axios.com

    Credit score and Purchaser Finance

    FICO Rating, Satisfy VantageScore

    Probabilities are you occur to be at the moment accustomed to the ideas of credit score rating scores, together with methods to take care of your funds and credit score historical past accounts for an even bigger rating. Even so, chances are you’ll maybe not be accustomed to VantageScore®, a substitute for FICO.

    VantageScore was created in 2006 as an alternate to plain credit score historical past scoring. It procedures credit score historical past and cash habits in any other case, giving way more people the capability to ascertain a superior credit score historical past score. Two teams that VantageScore assists: increased schooling school college students and new immigrants. 

    VantageScores are extensively made use of by credit score historical past card issuers, with 9 of the ten largest banking corporations making use of this credit score rating score. Due to the actual fact your following credit score historical past utility might be processed together with your VantageScore, it is a major introduction. 

    VantageScore considers 4 important funds administration elements when calculating your score.

    Very influential: Total credit score rating use, concord and provided credit score historical past
    Remarkably influential: Credit mix and encounter
    Reasonably influential: Payment historical past
    Considerably much less influential: Age of credit score rating background and new accounts opened

    Related to FICO, VantageScore scores you on a spread from 300 to 850. Scores of 499 and beneath are regarded Inadequate, and scores above 781 are graded Outstanding.

    If you’d prefer to see your VantageScore, there are quite a few strategies to do that. Numerous credit standing card issuers, like Chase and Capital One explicit, give their cardholders completely free accessibility to this data and info. You may additionally check out the VantageScore website for much extra choices.

    Resource: cnbc.com

    Did You Know?

    How To Keep Tabs on a Reworking Venture

    If you might be arranging a significant remodel this yr, you possibly can be eager to know methods to handiest deal with the job. Using the companies of a bonded, licensed contractor is an obligatory first motion. The 2nd stage? Monitoring the function because it progresses, if attainable, to make sure all staff are adhering to your major contract.

    The unlucky reality about transforming is that it truly is ceaselessly tough to establish if a contractor is decreasing corners with sub-par parts, workmanship, or each equally. Here are some instances to look at out for, collectively with approaches for challenge-solving.

    Your contractor is working with low-high-quality components. This could occur when inflation causes the substance costs to rise quickly after you’ve signed off on the problem, however your contractor feels pressured to proceed to be within the preliminary value vary. One technique to cease this state of affairs is to ask for a radical estimate that describes the precise grade and mannequin of every product. When these get there at your own home, double-look at to guarantee they match your agreed-upon estimate. A distinct system: go over the probability of climbing costs mid-project together with your contractor earlier than carry out commences, collectively with a contingency program.

    Some parts are lacking or you shouldn’t match. Make sure your rework comprises all of the options you have compensated for. If you are lacking electrical retailers, constructed-in cupboards, or different features, it’s time to blow the whistle. Another crimson flag: tiles that by no means match or are a a little bit bit distinct form or color. This may essentially imply that they ended up purchased from salvage or discounted warehouses.

    Drawers aren’t opening effortlessly. You could properly presume that your drawers are buying trapped on something, however it may be usually since they’re as properly small—a frequent cash-saving tactic.

    Gaps throughout house home windows or doorways. These might be introduced on by improper set up or cheaper substitutes.

    If you discover (or suspect) that your contractor is slicing corners, proper listed below are some strategies to decide on.

    If you location proof simply earlier than function is completed, select pictures of your issues.
    Ask for components invoices and evaluate them to your genuine packages.
    Upcoming, timetable a meeting with the contractor.
    Be geared as much as make clear your concerns politely and generate proof of things that require to be modified.
    Maintain in thoughts that your contractor could properly have manufactured an real error. Most will upkeep, swap or redo one thing you are not happy with.

    If you occur to be not geared up to seem to an association, herald a second contractor or an unbiased inspector to judge the carry out and provide estimates for rectifying issues. Other methods: in quest of licensed data or calling the purpose out workplace surroundings or regulatory board that issued your contractor’s license.

    Supply: lifehacker.com

    Nevertheless hoping to find out in case your reworking methods make sense on your fiscal picture? We have a terrific publish that handles the home renovations with the perfect return on expense in addition to a completely free E guide with renovation funding fundamentals.

  • Respectable Restoration For Home loan Rates, But Large Volatility Likely Ahead

    House loan premiums round matched their finest concentrations in months yesterday, however managed to remodel factors all-around at the moment.  One might argue that the broader bond trade (which dictates costs) started to remodel factors yesterday morning and that the one motive charges moved larger was the in a single day bond present market motion.  

    So these days was presumably a brand new restoration or a continuation of yesterday’s restoration, however none of that points now.  Wherever we could also be this afternoon, we could be someplace fully totally different tomorrow afternoon.  Whilst that’s legit each single day {the marketplace} is open, it really is a an important deal bigger model of legit proper now.

    Why?

    Tomorrow early morning marks the launch of the Customer Rate Index (CPI).  Of all of the month to month monetary evaluations, this one has probably the most potential to lead to volatility for charges.  

    Is volatility awful or nice?  

    It is essential to completely grasp that volatility is a two approach avenue.  A extremely minimal trying by means of on CPI would in all probability press charges significantly decrease though a extraordinarily superior trying by means of would do the reverse.  Additionally, it’s also doable for the information to string the needle and go away charges about unchanged, however the stage is that the vary of potential outcomes is loads wider than atypical.

  • Tuscan Capital appoints new regional income director for the Midlands – Home loan Finance Gazette

    Rebecca-Salt-pic-620x330.jpg

    Salt has greater than a decade’s information in the industrial finance sector, equivalent to roles at Aldermore Bank and Bibby Financial Solutions.

    Most just lately Salt labored with the bridging employees at Stream Lender.

    She joins the shorter-term lending professional to do the job with corporations and advisers all through the Midlands, supporting their shorter-phrase finance shoppers, boosting and producing interactions, and delivering support.

    She will report back to product sales director Jaxon Stevens and do the job out of the lender’s Birmingham workplace atmosphere.

    Salt’s appointment follows the new announcement of Katie Wilsher-Garratt as Tuscan’s new regional product gross sales director for the Home Counties, and the loan supplier claimed this was ingredient of its over-all product gross sales employees restructure, designed to offer wider help to dealer and middleman associates all through the area.

    Salt suggests: “There has been a considerable improve to each enterprise and family enhancement in the Midlands not too way back, and that is established to go on into the long term, so I’ll be working with corporations to current how Tuscan’s highly effective assortment of quick-expression home finance can meet the calls for of landlords and builders, and their ongoing tasks.”

  • Pure Retirement lifts fairness release LTVs up to 48%   – Home finance loan Method

    Pure Retirement has lifted mortgage-to-worth ratios on a single of its fairness release ranges on new authentic developments and additional progress borrowing.  

    The lender states its Basic life time residence loans now permit for an applicant aged 70 can receive LTVs up to 38% (up 2%), and candidates from 80 can entry LTVs up to 48% (additionally, up 2%).  

    These loans carry no upfront bills, no association bills and seem with cost-free valuations.  

    The group provides that for current Vintage customers, association charges on new extra improvements have been scrapped and shoppers can even accessibility extra developments at up to 90 many years of age for the youngest borrower — offering completion takes place on or forward of age 89 a very long time in addition to 364 days.  

    Pure Retirement head of merchandise Chris Buchanan claims: “Our Traditional merchandise has repeatedly been a number one life time residence loan answer, and the improved LTVs available, up to 48%, will open up up the Common merchandise to extra women and men and provides them better possibility and worth subsequent our the newest willpower to take out the association cost throughout the fluctuate.”  

  • explode.com – Implosion Information Decide-ups: Not Uncovered

    &#13

    &#13

    &#13

    &#13

    &#13

    &#13

    &#13

    &#13

    property&#13

    info&#13

    inventory&#13

    about &#13

    search&#13

    &#13

    &#13

    &#13

    &#13

    &#13

    &#13

    &#13

    &#13

    &#13

    Look for IEHI info archive:

    &#13

    &#13

    &#13

    &#13

    &#13

    &#13

    &#13

    Enter your analysis situations&#13

    &#13

    &#13

    &#13

    &#13

     &#13

    &#13

    &#13

    &#13

    &#13

    &#13

    &#13

    &#13

    World-wide-internet&#13

    &#13

    &#13

    &#13

    &#13

    IEHI&#13

    &#13

    &#13

    &#13

    &#13

    &#13

    Submit search type&#13

    &#13

    &#13

    &#13

    &#13

    &#13

    &#13

    &#13

    &#13

    &#13

    &#13

    &#13

    &#13

    &#13

    Information merchandise not discovered!&#13

    &#13

    &#13

    &#13

    &#13

    &#13

    &#13

    &#13

  • The Gains of Rapid Onboarding and Offboarding for Property finance loan Lenders

    fired employee

    The course of of onboarding or offboarding in a house finance loan lending agency is a minefield. In an market with inflexible details regulation, cash assist distributors are beneath the gun to get their employees members in and out of the method as quickly as possible to take care of workflow relocating and information protected.

    The key obstacle that slows down a modify in work is technologies-centered. For a few years coordinating IT permissions controls with HR processes has put an enormous drag on the tactic. Luckily for us, applied sciences is catching up. Let’s think about a glimpse at how robotic method automation (RPA) is benefiting the onboarding and offboarding process for property finance loan collectors.

    RPA Technological know-how for Property finance loan Creditors

    Robotic System Automation (RPA) is an rising engineering simply these days utilized to the home loan and financial professional providers subject. Up-and-coming in group firms for the previous 10 years, RPA know-how is eventually reaching the size the place by it may be executed by smaller and medium-sized companies. RPA may be described as a set of program bots or artificial intelligence (AI) employees that do automated get the job executed by staying programmed or by “studying” how processes must goal using empirical proof collected from methodology data. It’s a again again-conclude improvement useful resource that standardizes HR and IT cooperation, among the many different points, in a powerful manner.

    How It Performs

    The automated bots within the RPA course of journey onboarding and offboarding processes to be extra rapidly than ever. Identity is the necessary to securing any enhance in work through RPA. Leveraging an id firm and integration with an energetic itemizing (Advertisement), this automation can authenticate new hires and nullify earlier accounts routinely. RPA eliminates human-activated stop-gaps in procedures like acquiring e-mail, preserving paperwork, and updating databases paperwork. Business enterprise process workflows happen instantly and authorizations get immediate focus by notifying HR and IT with out having the need for inside communication. With permissions controls constructed into the RPA processes, supplying entry to a brand new property finance loan employees or booting any person off the tactic after they depart will get to be a a single-move course of. Entry Small enterprise Systems or ABT, a California-based largely mortgage loan software program enchancment enterprise, has taken the applied sciences and built-in it as facet of their merchandise MortgageWorkSpace. The result’s a cloud-based largely do the job setting that adapts swiftly and particularly addresses the obstructions current within the financial professional providers atmosphere.

    More rapidly and Much extra Efficient

    The effectivity of RPA is unquestionable. Staff members are energetic. They overlook notifications. They don’t consistently prioritize correctly. They merely simply have incomplete data and details to see the even greater image so human-driven processes go little by little. With RPA, the process or the “bots” see the numerous {photograph} that exact individual workforce can not. From human strategies to IT, the RPA workflow handles a the overwhelming majority of the work and boosts any human intervention important to maneuver ahead. Anything happens in minutes as an alternative of the aged manner, which took many hrs of full of life perform. With a program geared as much as get a brand new loan officer on their very first day of perform, there isn’t a lengthier a time gap for new hires. They can get acquainted with the function setting organising on day only one.

    Positive features Beyond Velocity

    However timeliness is definitely acknowledged, there are additional added advantages of RPA that go additional than mere pace. Accuracy enhances since units sort out the knowledge entry and there isn’t a area for human mistake. Exiting financial institution loan officers, who’ve a excessive turnover cost, aren’t any for an extended interval a hazard administration menace. The methodology is secured and they only can’t simply take delicate particulars with them on the best way out. Eventually, it’s only a individual a lot much less issue for your occupied employees members to do. HR and IT staffers get to endlessly clear away actions within the process from their to-do lists.

    The actual reality is that onboarding and offboarding are gradual within the mortgage loan complete world as a result of they’re information-intensive procedures. The delicate cash information of clientele and associates are usually not capable of be compromised so we’ve got extended skilled the labor depth of endeavor it manually. In the determine of efficiency there are a number of approaches to velocity up the method, however in the long term the answer is to go substantial-tech and take into consideration a different that has RPA doing work in your side.

    Mortgage loan companies that put into follow new automation technological innovation expertise the added advantages in worker pace, precision, and safety. For much more data cease by MortgageWorkSpace, compose to us at gross sales@myabt.internet, or fill out this type.

  • In depth Information and facts That Will Enable You Purchasing A International Countrywide Home finance loan

    Difficult Cash Loan corporations in Miami: Specific Details That Will Assistance You Acquiring A International Countrywide Mortgage

    Specific Info That Will Assist You Obtaining A Overseas National Mortgage

    If you might be resident of another state and you need to get your particular person residence within the US, you possibly can borrow international nationwide home loan to buy the dwelling of your want. You can join with it an monetary funding property or dwelling to your trip.

    Undoubtedly, for buying a property will create some obstacles if you’re non-citizen of US. But at present, you’ll uncover quite a few mortgage lenders or lending companies which are presenting residence loans to foreigners for buying their particular person family or residence. Foreigners may get hold of from federal authorities backs at minimal-interest charges and down funds.

    Don’t neglect that the wants for getting a home loan change in line with the residential place of the candidates.

    International Nationwide Mortgage Qualification

    For getting a worldwide nationwide mortgage, you should have a official earnings proof in your home on account of letterhead of the corporate which embody different particulars in regards to the job goal in your nation.

    Creditors will confirm your belongings using lender assertion of the previous a single or two a number of years and additionally a reference letter from the monetary establishment. Also, the lenders verify the consumer’s standing to validate that there is no harmful or authorized document of their nation.

    Also, banking corporations have to have you ever to deposit a 20% of the general property price as down cost. Unique banking establishments have distinctive standards for down cost. You can inquire by contacting a acceptable loan firm. Each and each loan firm grants mortgage in accordance to their phrases and procedures. So it’s important to review in regards to the biggest loan suppliers and specs proper earlier than closing the supply with one.

    For loan acceptance, a guidelines of paperwork is required to submit. If you might be on the lookout for a abroad nationwide home loan, it’s best to guarantee that you’ve the following paperwork.

    You should carry a replica of your visa and passport. A copy of your associate is required as completely doesn’t matter if she or he is the co-applicant or not.
    Evidence proof of your main cope with by the use of some utility month-to-month invoice, and so on.
    A resume that reveals the document of employment of on the very least 10 a number of years.
    Two reference letters from the permitted lender.
    Most latest credit score statements within the type of a letter. At the very least two credit standing references are anticipated.
    A fast software program observe from the applicant describing the useful resource of prosperity.
    Money Evidence Needed:

    If Self-Employed: A letter from CPA specifying the cash of earlier two a few years.
    If Used: A letter from the HR division of your group exhibiting the wage of prior two a number of years.